Contents7 sections
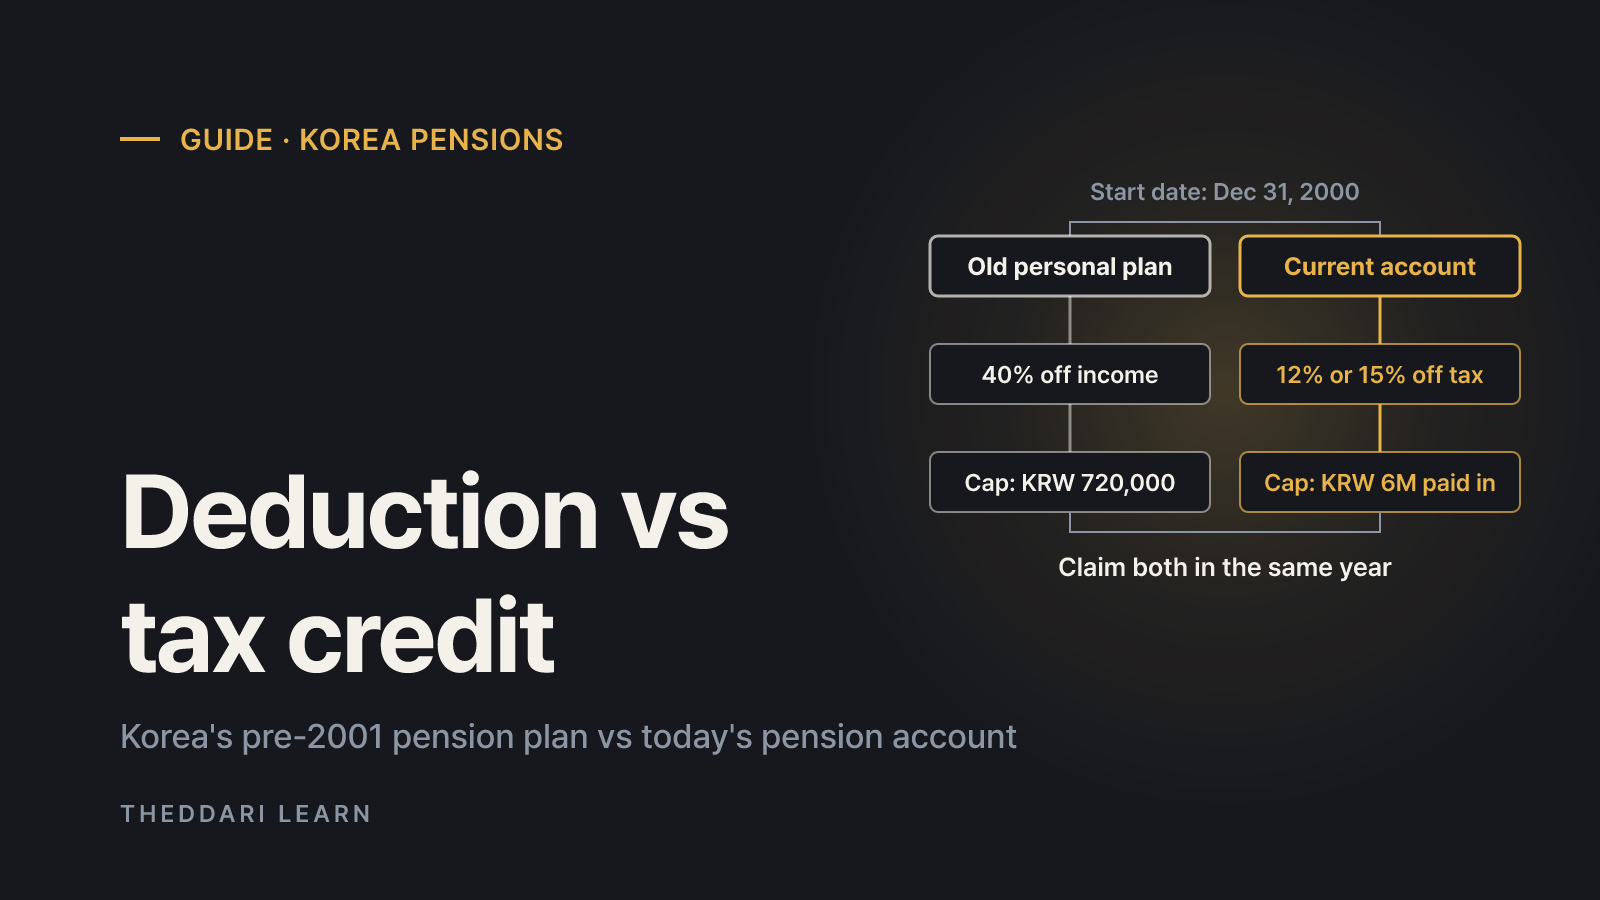
Korea personal pension savings plans opened on or before December 31, 2000 are an older, now-closed product that still affects some Korean residents' year-end tax settlement. They give an income deduction of 40% of the year's contributions, capped at KRW 720,000. Pension savings accounts opened from 2001 onward work differently: they give a tax credit of 12% or 15% of contributions, taken directly off the tax you owe. As of October 2026 no one can open the old plan, but people who still pay into one can keep claiming it, and they can claim the modern pension tax credit in the same year.
This guide is for Korean tax residents, including foreign residents who file in Korea, who see both plans on their statements and are not sure which rules apply. It is based on the Korean statutes and National Tax Service (NTS) guidance. It does not describe US IRAs, UK pensions or any other country's system.
What the old Korea personal pension savings plan is
The old plan was set up under Article 86 of the Restriction of Special Taxation Act. It let a resident who joined by December 31, 2000 deduct 40% of that year's contributions from global income, with any deduction above KRW 720,000 limited to KRW 720,000. The article was deleted on January 1, 2013, but transitional rules keep it alive for existing contracts. That is why Korean year-end settlement forms still have a separate line for personal pension savings opened before 2001.
Article 80 of the Enforcement Decree set the product rules at the time:
- Opened on or before December 31, 2000
- Holder aged 20 or older when joining
- Contributions paid for at least 10 years (special periods applied to some older holders)
- No more than KRW 3 million per quarter across all providers
- Paid out as an annuity for at least five years, starting at age 55 or later, after the contribution period ends
- Sold by bank trust departments, investment trust companies, insurers, Korea Post insurance, and agricultural or fisheries cooperative life mutual aid
Not sure which plan you have? Check the contract start date rather than the product name. If the contribution certificate from your bank or insurer shows a start date on or before December 31, 2000, it is the old income-deduction plan, whether it is called a personal pension trust or personal pension insurance.
How much the deduction is worth
The deduction equals 40% of contributions, capped at KRW 720,000, so you hit the cap at KRW 1.8 million a year. Because it reduces taxable income rather than the tax itself, the actual saving is the deduction multiplied by your marginal rate. NTS lists Korea's basic income tax rates from 6% (up to KRW 14 million of taxable income) to 45%, with 15% up to KRW 50 million and 24% up to KRW 88 million. In the 15% bracket, a full KRW 720,000 deduction saves KRW 108,000, or about KRW 118,800 once local income tax (10% of national income tax) is added. In the 24% bracket it saves KRW 172,800 before local tax.
How it differs from today's pension tax credit in Korea
Modern pension savings accounts fall under the pension account tax credit in Article 59-3 of the Income Tax Act. NTS says the credit rate is 15% if global income is KRW 45 million or less (KRW 55 million of total salary for wage earners only) and 12% above that. Eligible contributions are capped at KRW 6 million for pension savings and KRW 9 million combined with retirement pension accounts such as an IRP. The FSS FinLife comparison page shows the effective rates including local tax as 16.5% and 13.2%.
Who qualifies
- Old personal pension savings
- Contracts opened by Dec 31, 2000 (closed to new members)
- Current pension savings account
- Opened from Jan 1, 2001 (still available)
Type of relief
- Old personal pension savings
- Income deduction from global income
- Current pension savings account
- Tax credit against tax payable
Rate
- Old personal pension savings
- 40% of contributions
- Current pension savings account
- 12% or 15% (13.2% or 16.5% with local tax)
Limit
- Old personal pension savings
- Deduction capped at KRW 720,000 (reached at KRW 1.8M paid)
- Current pension savings account
- KRW 6M contributions; KRW 9M with retirement pension
Maximum effect on KRW 6M of pension savings
- Old personal pension savings
- KRW 720,000 x your marginal rate
- Current pension savings account
- KRW 990,000 at 16.5% or KRW 792,000 at 13.2%
Annuity payouts
- Old personal pension savings
- Earnings tax-free if paid as agreed
- Current pension savings account
- Pension income tax of 5% (under 70) down to 3% (80+), plus local tax
Early cancellation
- Old personal pension savings
- Earnings taxed as interest income
- Current pension savings account
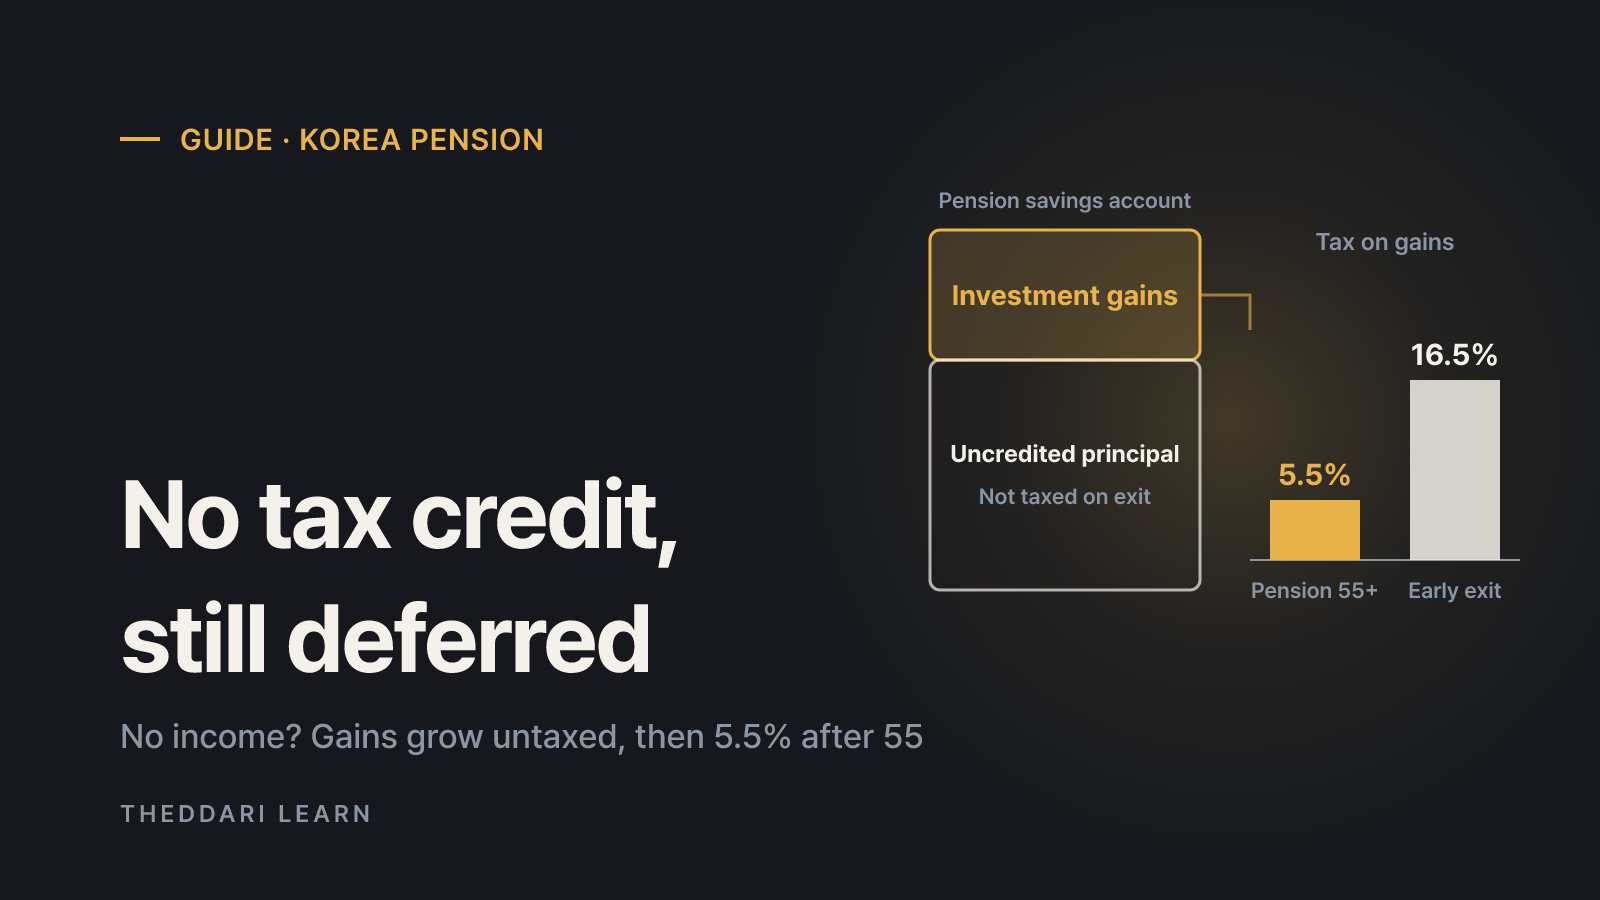
- 15% other income tax on credited contributions and gains
Moving providers
- Old personal pension savings
- Transfer to another provider's personal pension plan is not a cancellation
- Current pension savings account
- Transfers between pension accounts do not count as new contributions
A deduction grows with your tax bracket, while a credit gives roughly the same rate to everyone in the same band. The old plan's small cap means even high earners save a modest amount each year. The modern credit has a much larger contribution limit, so in won terms it is often bigger, but it cannot reduce your tax below zero. For holders of the old plan, the real question is not which product to pick but whether to keep the old contract running.
Claiming both at Korean year-end tax settlement
Because the deduction and the credit rest on different provisions with separate limits, an eligible resident can claim both. A wage earner with total salary of KRW 55 million or less who pays KRW 1.8 million into an old plan and KRW 6 million into a new pension savings account would calculate a KRW 720,000 income deduction and a KRW 900,000 tax credit (15% of KRW 6 million, before local tax) separately.
- 1
Confirm the start date and product type
Use your provider's contribution certificate or the NTS Hometax simplified year-end data to see whether each contract is a pre-2001 personal pension plan or a post-2001 pension savings account.
- 2
Check whose name is on the contract
Both benefits apply only to contracts in the taxpayer's own name. Money you paid into a spouse's or parent's plan does not count.
- 3
Enter each on its own line
Put the old plan under other income deductions and the new account under the pension account tax credit. Never list the same contribution twice.
- 4
Exclude a cancelled contract
If you cancelled a plan during the year, compare your provider's records to make sure that year's contributions are not claimed.
Taxes and risks before cancelling or cashing out
Under Article 86, annuity payouts made as agreed are free of income tax on the plan's earnings. Cancelling before the contribution period ends, or taking a lump sum after maturity, makes those earnings taxable as interest income. A rule that clawed back 4% of contributions on cancellation within five years no longer bites, since every old plan is more than 25 years old. The Enforcement Decree exempts cancellations after events in the prior six months such as a natural disaster, leaving your job, closing a business, illness or injury needing three months or more of treatment, or the provider's suspension or bankruptcy; death and emigration are also exempt. NTS has ruled that an intra-group job transfer where severance carries over is not a qualifying departure.
For modern accounts, NTS withholding guidance says credited contributions and gains withdrawn outside a pension are taxed separately at 15% as other income, unless the withdrawal is for medical or other unavoidable reasons. Pension payouts are withheld at 5% under age 70, 4% from 70 to 79 and 3% from 80, and lifetime annuities that cannot be cancelled are taxed at 3% for payments from January 1, 2026. If private pension income is KRW 15 million a year or less you may choose separate taxation; above that you choose between global taxation and a 15% separate rate.
Tax treatment is not the only risk. Old trust and insurance plans may now carry low crediting rates or fees, so read the annual statement. Fund-type pension accounts can lose value, and interest-rate or inflation releases can move bond and equity funds. You can check upcoming release dates on Theddari's economic calendar.

If you hold ETFs inside a pension account, it can help to see which market stories are being discussed, while judging separately whether a popular theme suits money you plan to hold for decades.
Checklist for holders of the old plan
- Confirm the contract start date is on or before December 31, 2000.
- Check whether you actually paid in this year; if not, there is no deduction, only the tax-free annuity benefit.
- Claim the old deduction and the pension account credit on separate lines.
- Before cancelling, ask your provider to estimate the interest income tax and check for a qualifying exemption.
- When switching providers, confirm it is a plan-to-plan transfer rather than a cancellation and new purchase.
- For modern accounts, factor the 15% tax on non-pension withdrawals into any plan to take money out early.