Contents8 sections
CoreWeave (Nasdaq: CRWV) is an AI cloud company that builds data centers packed with Nvidia GPUs and rents that computing capacity to AI labs, large tech firms and enterprises, mostly under multi-year contracts. It is usually grouped with the "neoclouds" rather than general-purpose clouds like AWS or Azure. As of October 2026, this guide uses the company's second-quarter 2026 results (quarter ended June 30) and its 10-Q to explain how the business makes money, why customer concentration matters, and why its debt makes the stock so sensitive to interest rates. The short version: demand and contracts are growing fast, but the capacity to serve them is being built largely with borrowed money.
What does CoreWeave do?
Founded in 2017 and listed on Nasdaq in March 2025 (company release), CoreWeave started life as a bitcoin miner, according to Reuters. Today it bundles GPU servers, high-speed networking and powered data center space into capacity that customers use to train and run AI models. It also sells software such as Weights & Biases for experiment tracking and its SUNK scheduling platform, but renting GPU capacity remains the core of revenue.
Scale is usually measured in power. At the end of Q2 2026, CoreWeave had about 1.5 GW of active power and roughly 3.7 GW of contracted power. The gap between the two is capacity still to be built, which is why heavy capital spending is likely to continue.
Revenue
- Q2 2026
- $2,575M
- Q2 2025
- $1,212M
Operating income (loss)
- Q2 2026
- $(49)M
- Q2 2025
- $19M
Interest expense, net
- Q2 2026
- $640M
- Q2 2025
- $267M
Net loss
- Q2 2026
- $(626)M
- Q2 2025
- $(290)M
Adjusted EBITDA (margin)
- Q2 2026
- $1,510M (59%)
- Q2 2025
- $753M (62%)
A 59% adjusted EBITDA margin looks strong, but EBITDA sits before depreciation and interest. GPUs lose value quickly, so depreciation and amortization was $1,393 million in the quarter, and interest ate roughly a quarter of revenue. That is how a company can be EBITDA-positive yet lose money at both the operating and net lines.
How the GPU cloud model works: contracts and backlog
Almost all revenue is contracted. The 10-Q says revenue tied to customer commitments was 98% of Q2 2026 revenue. A customer commits to a block of GPU capacity for several years, and CoreWeave uses that commitment to justify buying hardware and leasing data center space. That makes revenue look predictable, and it also means stranded capacity if a commitment slips.
Management put the revenue backlog at about $104 billion at quarter-end and said it signed more than $25 billion of net new commitments early in Q3. The filing's remaining performance obligations (RPO) figure is $103.7 billion, already net of expected service credits and delivery delays (Convexity's 10-Q breakdown). The recognition schedule is:
- 41% within the 24 months ending June 30, 2028
- 39% between months 25 and 48
- The remaining ~20% between months 49 and 78 (out to late 2032)
Note the unit: CoreWeave discloses a 24-month bucket where peers such as Oracle use 12 months, so near-term comparisons are not apples to apples. On the earnings call the CFO said more than half of the backlog sits in contracts where delivery has started, and he expected that to exceed two-thirds by year-end. Tracking that ratio tells you how fast paper contracts turn into billed revenue.
Customer concentration: three clients, 72% of revenue
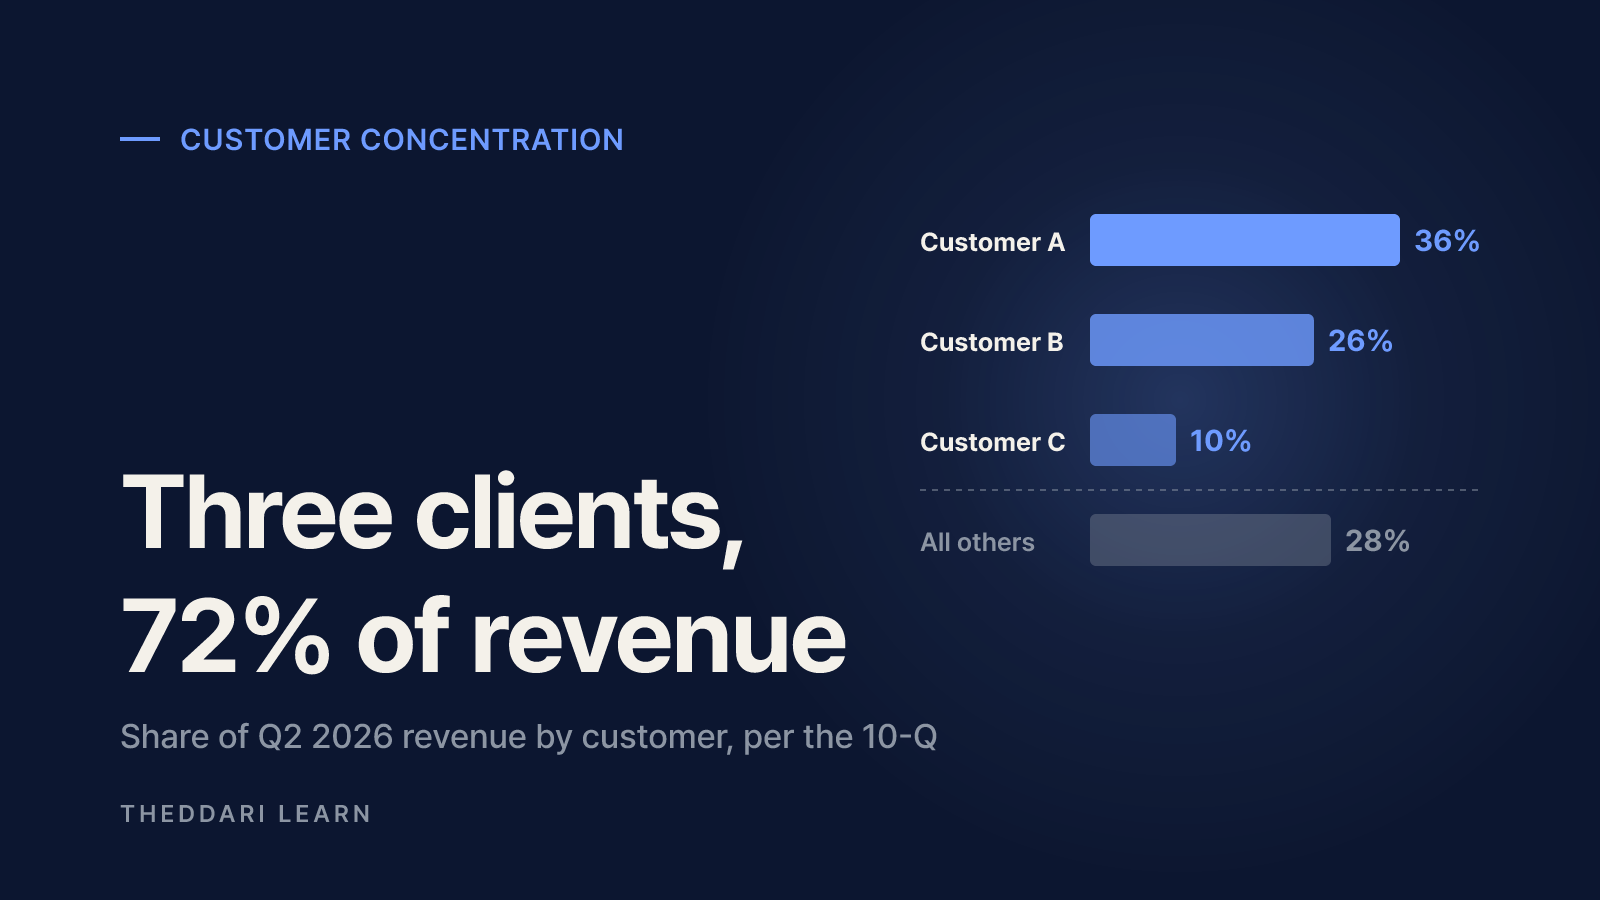
The 10-Q's significant-customer table shows three customers above 10% of Q2 2026 revenue: Customer A at 36%, Customer B at 26% and Customer C at 10%, or 72% combined, with everyone else sharing the remaining 28%. A year earlier a single customer was 71%. That looks like diversification, but the filing warns that the letters may represent different companies across periods, so you cannot assume the same client simply shrank. Customers A and B also each held 32% of accounts receivable.
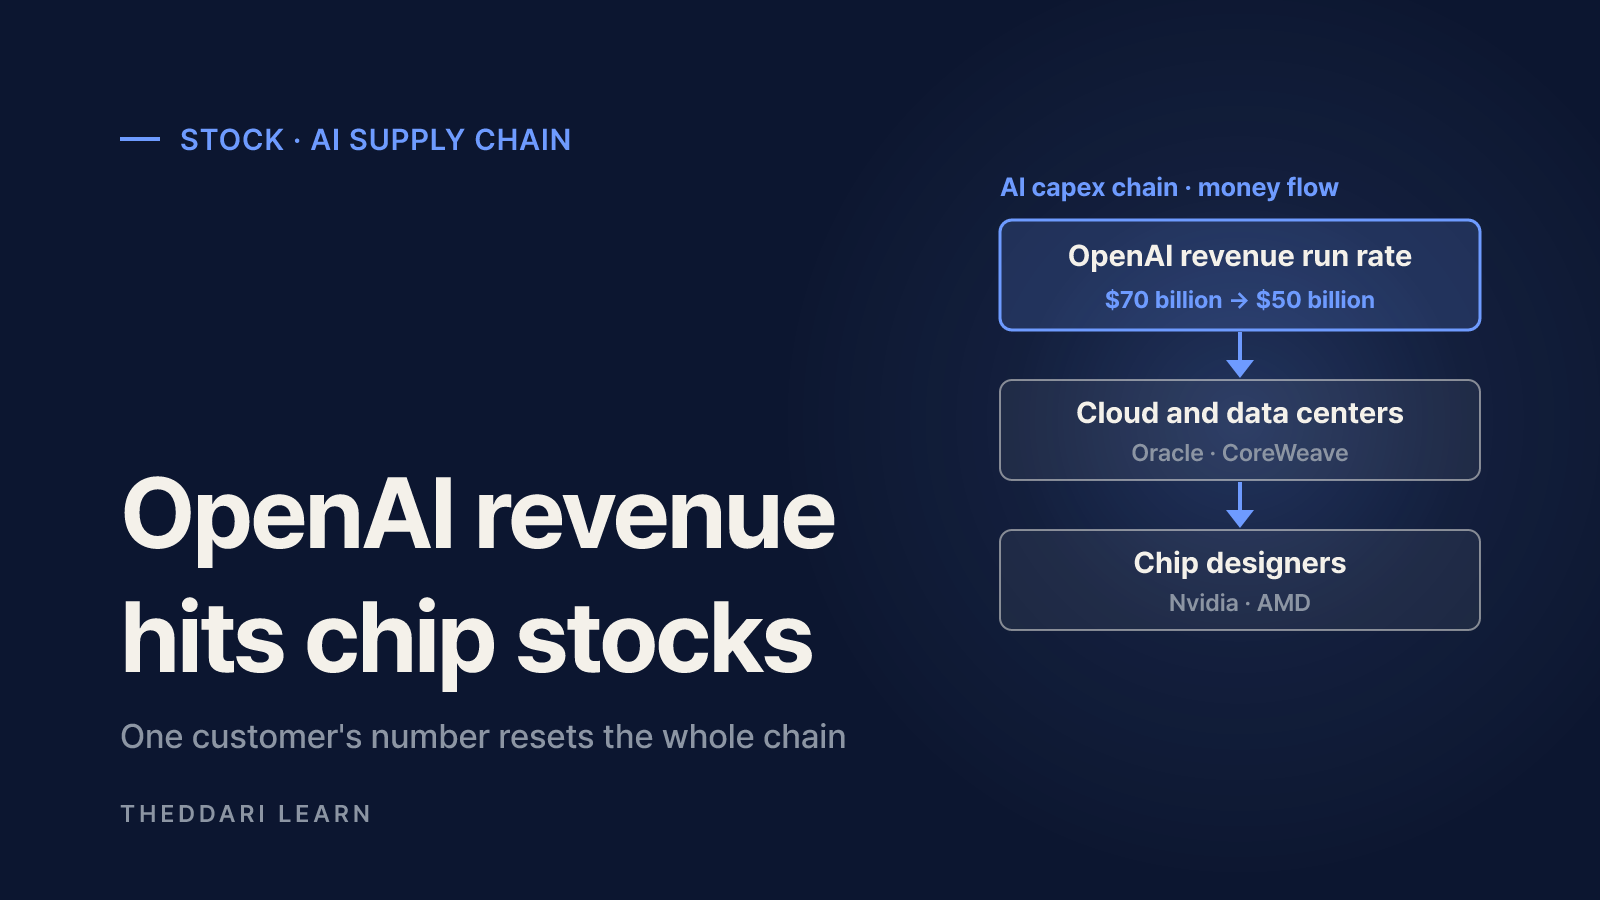
Named customers in the filing include OpenAI, under a master services agreement signed in May 2025, and Meta, which initially committed up to about $21.0 billion. The Q2 release also lists expanded work with Databricks, Cognition and Runway ML and new enterprise names such as Caterpillar. Big, well-funded counterparties are a credit strength, but several AI labs are themselves loss-making buyers of compute. Reuters notes that revenue growth at firms like OpenAI and Anthropic, while still fast, has softened, and any funding squeeze there would flow straight into CoreWeave's contracts.
The practical risk is less a customer walking away than a contract being delayed or resized. The GPUs and data centers are already financed, so even a few quarters of slipped revenue leaves interest and depreciation running at full speed.
CoreWeave debt and interest-rate sensitivity
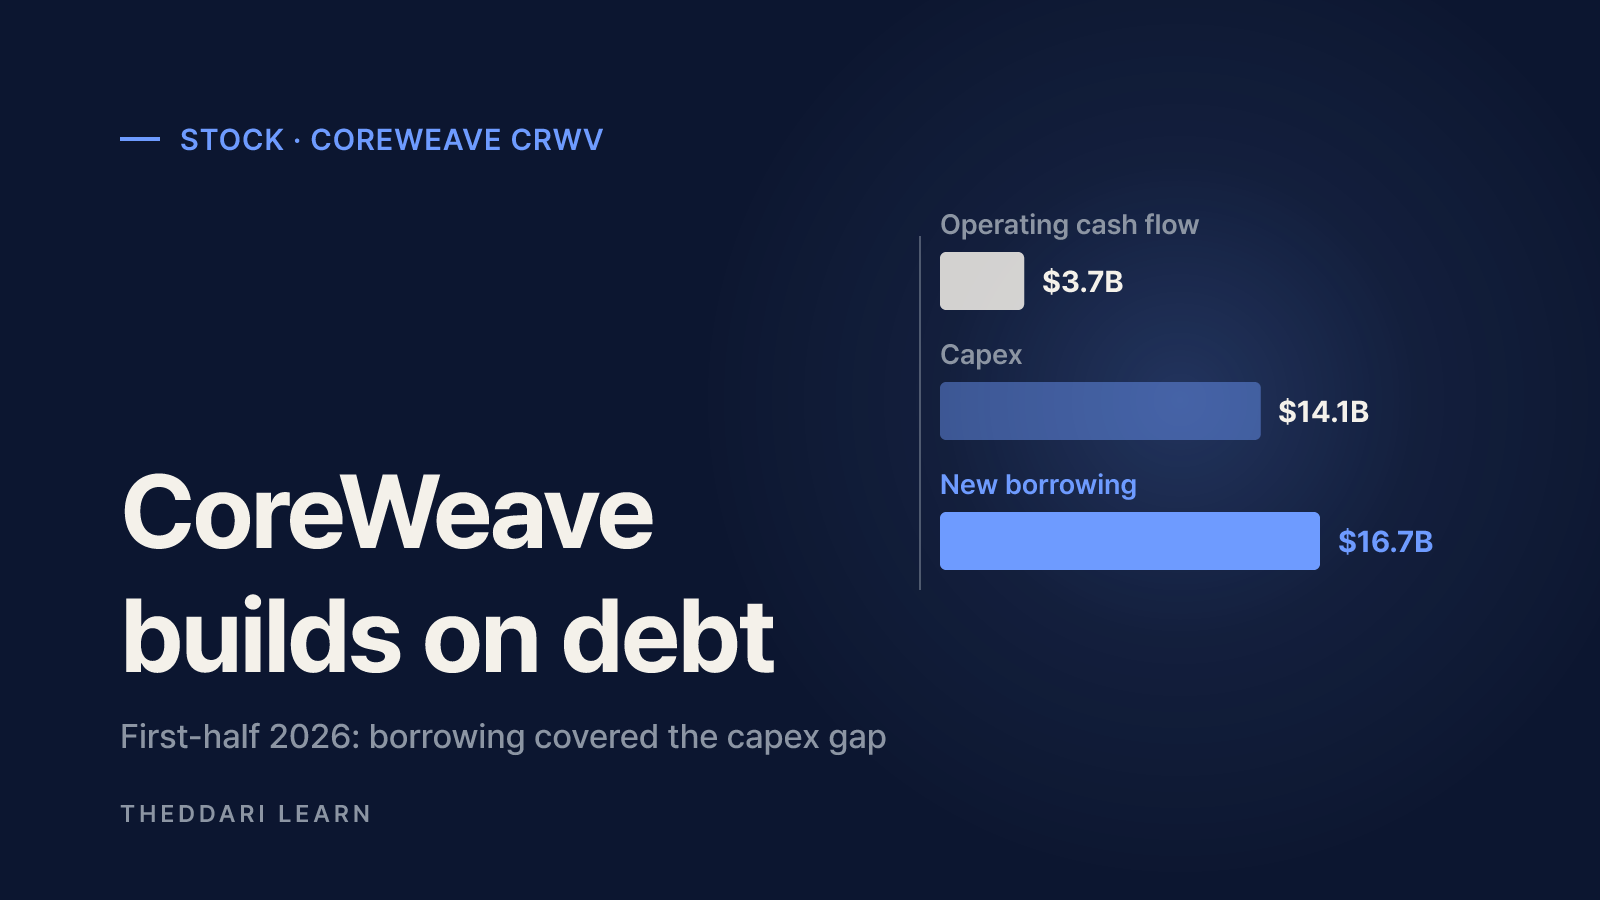
Cash flow is the central debate. In the first half of 2026, operating cash flow was $3.7 billion, but purchases of property and equipment were $14.1 billion. Borrowing filled the gap: $16.7 billion of new debt, or about $11.5 billion net of $5.2 billion in repayments. Reuters puts full-year 2026 capex guidance at $35 billion to $39 billion (Reuters analysis).
Total debt
- Amount
- ~$35.1B
- Note
- Recourse plus non-recourse; up ~$13.7B in six months
Operating lease liabilities
- Amount
- ~$16.3B
- Note
- Data center space
Stockholders' equity
- Amount
- ~$5.0B
- Note
- Against $77.07B of total assets
Principal due by end-2028
- Amount
- ~$15.0B
- Note
- Rest of 2026 plus 2027 and 2028
Senior note coupons
- Amount
- 8.5%–9.75%
- Note
- Convertibles carry 1.75%
Q2 interest expense of $640 million was about 25% of revenue and grew 140% year over year, faster than revenue's 112%. Coupons of 8.5% to 9.75% are high-yield pricing, and rating agencies classify the debt as speculative grade. When rates rise or sentiment toward AI infrastructure sours, CoreWeave's cost of new money jumps. In the week Reuters reported on October 16, 2026, after hyperscalers hinted at data center delays and slower capex growth, the stock fell more than 15%, its 2030 bond yields rose about 500 basis points to near 16%, and credit default swap spreads reached roughly 1,200 basis points.
Management's case is project finance: each cluster is front-loaded with capex, but contracted revenue repays the asset-level debt over the contract, leaving an unlevered asset. The CFO said the weighted average cost of debt had fallen by almost 300 basis points, and part of the borrowing is non-recourse. On September 17, 2026, CoreWeave announced an at-the-market program for up to 35 million shares and $3.0 billion of convertible notes due 2033, citing a goal of moving toward an investment-grade credit profile. For shareholders, that trades lower leverage for dilution.
What to watch in CRWV earnings
- 1
Backlog in delivery
Focus on the share of backlog where delivery has started and the 24-month recognition slice, not just the headline total. New contracts that deliver late add debt before revenue.
- 2
Operating income vs. interest
Q2 showed a $49 million operating loss against $640 million of interest. Operating income overtaking interest expense is the line that shows debt can be serviced from operations.
- 3
Operating cash vs. capex
Strip out customer prepayments (the rise in deferred revenue was about 37% of first-half operating cash) and compare what remains with capital spending.
- 4
Active vs. contracted power
How fast the gap between 1.5 GW active and 3.7 GW contracted closes reveals construction delays, power bottlenecks and component shortages.
- 5
Customer table and funding terms
Compare the number and weight of 10%+ customers each quarter, plus coupons on new debt. New notes pricing well below 8.5% to 9.75% would signal the credit market sees less risk.
Use the theddari earnings calendar to track CoreWeave's next report date and the economic calendar for US data that moves rates, such as inflation and jobs releases. These tools organize schedules; they do not predict price direction, so confirm dates against CoreWeave's investor relations site.

The bull and bear debate
Bulls point to a backlog above $100 billion, demand that still exceeds supply, and Nvidia's support: a $2.0 billion equity investment at $87.20 a share in January 2026 and, per Reuters, an agreement to buy unsold capacity through April 2032. A Moody's vice president told Reuters that CoreWeave does not buy chips speculatively and has multiple financing avenues.
Bears point to expensive junk-rated debt, circular financing between Nvidia, neoclouds and AI labs, and dependence on a handful of buyers. Reuters cites Gartner's forecast that 80% of neocloud providers will cease independent operations by 2030. CoreWeave reported 2025 revenue of $5.1 billion and a net loss of $1.2 billion and has never posted an annual profit. Insider sales drew attention too, though most of the CEO's sales ran under prearranged Rule 10b5-1 plans.
Put together, CoreWeave is one of the most direct listed plays on AI compute demand, but it meets that demand by borrowing ahead of revenue. That is why CRWV reacts not only to AI headlines but to Treasury yields, credit spreads and the financial health of its largest customers. Before forming a view, read the latest 10-Q's customer table, debt maturity schedule and cash flow statement yourself, and track the metrics above quarter by quarter.