Contents7 sections
- What an Ethereum staking ETF is and how it differs from a spot ETH ETF
- How staking rewards reach shareholders
- Reading staking rates, fees and the real fund-level effect
- Risks specific to staking: queues, liquidity and slashing
- Checklist before comparing ether ETFs
- Frequently asked questions
- Sources and references
An Ethereum staking ETF is a spot ether fund that stakes part of the ETH it holds and passes the net staking rewards to shareholders, either as cash distributions or by keeping them in the fund. Its price exposure is essentially the same as a regular spot ETH ETF, but it adds a variable income stream along with risks that a plain spot fund does not carry: validator queues, penalties, slashing and operator failure. This guide uses the official product pages of Grayscale and BlackRock as of October 23, 2026, plus ethereum.org, to explain how the two fund types differ and how to read the staking numbers issuers publish. It describes US-listed products; availability elsewhere depends on local rules.
What an Ethereum staking ETF is and how it differs from a spot ETH ETF
Ethereum runs on proof of stake. According to ethereum.org, staking means depositing ETH to activate a validator, which proposes blocks and checks other validators' work in exchange for rewards. A single validator needs at least 32 ETH and can hold up to 2048 ETH. A plain spot ether ETF keeps its ETH with a custodian and does nothing else with it. A staking ETF assigns part of that ETH to validators run through its custodian and node operators.
Two paths exist in the US market. Grayscale added staking to its existing funds, now named Grayscale Ethereum Staking ETF (ETHE) and Grayscale Ethereum Staking Mini ETF (ETH). BlackRock instead launched a separate product, the iShares Staked Ethereum Trust ETF (ETHB), with a fund inception date of February 18, 2026, listed on Nasdaq. All three disclose that they are not registered under the Investment Company Act of 1940, so they do not carry the same protections as 40 Act ETFs and mutual funds.
Holdings
- Spot ETH ETF (no staking)
- Ether held by a custodian
- Ethereum staking ETF
- Ether, part of it staked with validators
Return drivers
- Spot ETH ETF (no staking)
- ETH price minus expenses
- Ethereum staking ETF
- ETH price minus expenses plus net staking rewards
Extra income
- Spot ETH ETF (no staking)
- None
- Ethereum staking ETF
- Variable staking rewards that can be zero
Distributions
- Spot ETH ETF (no staking)
- Usually none
- Ethereum staking ETF
- Cash payouts or rewards retained, depending on the fund
Added risks
- Spot ETH ETF (no staking)
- Price, custody, tracking
- Ethereum staking ETF
- Plus queues, penalties, slashing and operator risk
Documents to read
- Spot ETH ETF (no staking)
- Prospectus
- Ethereum staking ETF
- Prospectus, staking policy and staking metrics
Staking does not cushion a price decline. Annual staking rewards are a few percent at most, while ether can move more than that in a single day. Decide first whether you can tolerate ether's volatility; the staking layer is a secondary question.
How staking rewards reach shareholders
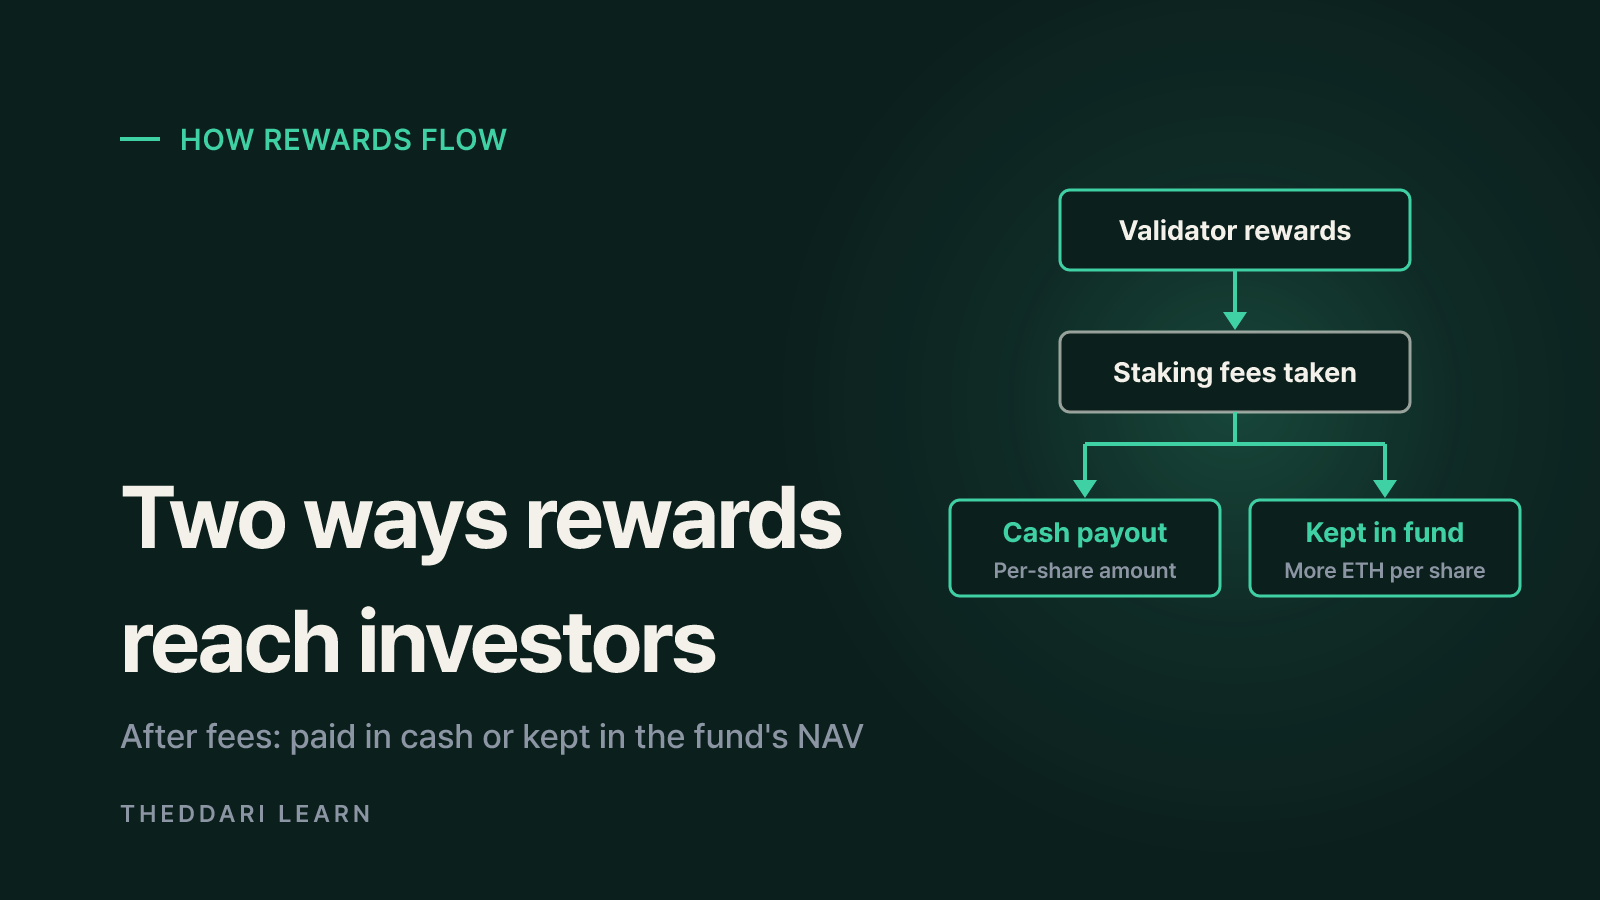
There are two delivery routes. With cash distributions, the fund sells the ether it earned and pays a per-share amount to holders of record. With accumulation, rewards stay in the fund and increase the ether behind each share, which shows up in NAV rather than as cash. A fund can change its approach, so the current prospectus is the authority.
- 1
Validators earn rewards
Validators funded by the trust's staked ETH propose and attest to blocks and receive protocol rewards in ether. The rate changes with network conditions.
- 2
Staking fees are taken
The sponsor, custodian and node operators keep a share of gross rewards. The gap between the gross and net rates on Grayscale's pages reflects that share.
- 3
Rewards are paid out or retained
Net rewards are sold and distributed in cash, or kept in the fund. Grayscale and iShares publish record dates, payable dates and per-share amounts.
- 4
The sponsor fee is charged separately
The sponsor fee applies to the whole fund. BlackRock notes that the ether per share declines over time as ether is sold to pay the sponsor fee and expenses.
The amounts vary. Grayscale's ETHE page lists distributions from $0.083178 per share in January 2026 to $0.032017 in October 2026, and the ETH Mini page shows payouts in September and October 2026. ETHB lists monthly payouts too, including $0.035466 per share in October 2026. Past payouts reflect past reward rates, staking levels, ether prices and costs, so they are not a schedule of future income.
Reading staking rates, fees and the real fund-level effect
Headline staking rates are easy to misread. Grayscale describes its gross rate as the average over the prior 60 days annualized on a 360-day basis, and says its net rate is a percentage of staked assets only, not a fund-level return. A rough fund-level estimate is staked percentage times net rate, which you then compare with the sponsor fee. The table below applies that arithmetic to figures shown on the issuer pages on October 23, 2026.
Sponsor fee
- ETHE
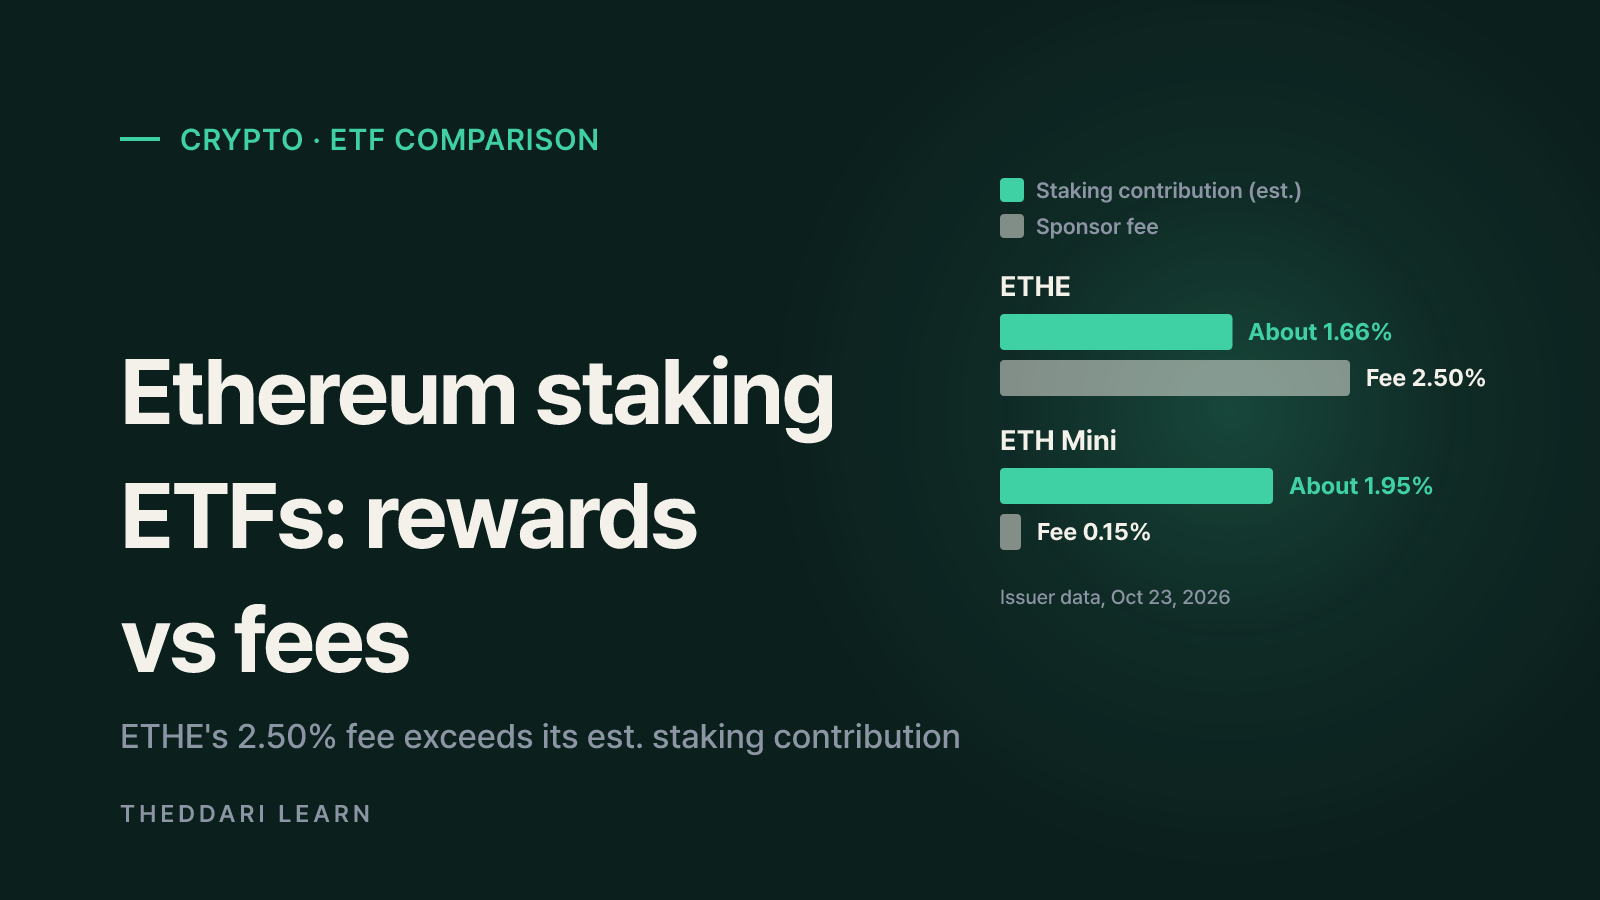
- 2.50%
- ETH Mini
- 0.15%
- ETHB
- 0.25% (0.12% during a 12-month waiver)
Staked share of fund
- ETHE
- 82.22%
- ETH Mini
- 80.23%
- ETHB
- Not shown on product page
Gross reward rate (staked assets)
- ETHE
- 2.63%
- ETH Mini
- 2.59%
- ETHB
- n/a
Net reward rate (staked assets)
- ETHE
- 2.02%
- ETH Mini
- 2.43%
- ETHB
- 30-day staking rewards rate 1.55%
Share of gross lost to staking fees
- ETHE
- About 23%
- ETH Mini
- About 6%
- ETHB
- n/a
Estimated fund-level contribution
- ETHE
- About 1.66%
- ETH Mini
- About 1.95%
- ETHB
- Different definition
Contribution minus sponsor fee
- ETHE
- About -0.84%
- ETH Mini
- About +1.80%
- ETHB
- n/a
For ETHE, 82.22% staked at a 2.02% net rate works out to about 1.66% of fund assets, which is less than the 2.50% sponsor fee. For the ETH Mini, the same arithmetic leaves about 1.80% after its 0.15% fee. These are simplified estimates from trailing averages. They ignore taxes, brokerage costs and bid-ask spreads, and every input changes daily. The point is narrower: a high staking rate on a fact sheet does not tell you whether rewards cover the fund's cost.
ETHB reports a 30-day Staking Rewards Rate of 1.55%, which may be calculated on a different basis from Grayscale's staked-asset rates. Before comparing funds, read each metric's definition: the look-back window, the annualization method and whether it is measured on staked assets or the whole fund.
Risks specific to staking: queues, liquidity and slashing
Staked ether cannot be withdrawn instantly. Ethereum.org explains that new validators wait in an activation queue that can range from hours to weeks depending on demand, and that exits pass through a similar rate-limited queue. BlackRock's ETHB disclosure adds that the trust's ether cannot be sold or transferred during activation, exit and withdrawal; that queues can stretch to days, weeks or months; and that ether earns no rewards while queued for activation or during withdrawal.
- Redemption liquidity: large redemptions must be met from unstaked ether first, which is why funds keep part of their ETH unstaked.
- Penalties and slashing: offline validators lose small amounts of ETH, and provable misbehavior such as signing two conflicting blocks destroys part of the stake.
- Operator and custody failure: issuers warn that security breaches, smart contract bugs or validator or custodian failure could cause a complete loss of staked ether or rewards.
- Variable rewards: rewards depend on network conditions, can fall to zero and may not be paid every month.
- Policy changes: sponsors may reduce or stop staking if legal, regulatory or tax conditions change.
In short, choosing a staking fund over a plain spot ETH ETF trades additional variable income for additional fees and operational risk on the same ether exposure.
Checklist before comparing ether ETFs
- Confirm in the prospectus that the objective includes staking rewards, and note the share of ether that may be staked.
- Check whether rewards are distributed in cash or retained, and how often distributions occur.
- Write down the sponsor fee and the staking fee separately; the gross-to-net gap shows the staking fee.
- Check each metric's basis, then estimate staked percentage times net rate minus the sponsor fee.
- Read the queue, slashing and operator risk sections and note the custodian and node operators.
- Confirm tax treatment in your jurisdiction and whether your broker offers the fund.
For readers trading ether in Korean won, domestic exchange prices can differ from global prices, the so-called kimchi premium. That gap matters when you compare a dollar-based ETF NAV with a local ETH quote, and the theddari kimchi premium page tracks it.

Staking policy changes and new fund launches often surface first in crypto chat channels. The theddari crypto Telegram trends page shows what is being discussed, which you can then verify against issuer filings and official product pages.
The core difference is simple: an Ethereum staking ETF adds net staking rewards on top of spot ether exposure and charges for it in fees and staking risk. Compare the staked percentage, the fee, the reward basis and the payout method together rather than relying on a single headline rate.