ChatGPT Debt Payoff: Can AI Build Your Repayment Plan?
Use ChatGPT for debt payoff planning wisely: what to ask, snowball vs avalanche, privacy settings to check, and when to call a credit counselor instead.
目录9 个章节
- What AI does well and where it falls short
- ChatGPT debt payoff prompts that get useful answers
- Debt snowball vs avalanche: what the AI's advice really means
- Limits of an AI debt repayment plan and privacy risks
- When to talk to a person before trusting the chatbot
- Track rate events and AI news on theddari
- A final checklist before you follow an AI plan
- 常见问题
- 来源与参考资料
核心要点
- ChatGPT is useful for listing debts, building a budget draft and comparing payoff orders, but it cannot see your loan terms, fees or credit report.
- The snowball and avalanche methods both start with every minimum payment; they differ only in where extra money goes first.
- Re-check any AI-generated payoff schedule against your lender's statements, because wrong assumptions about APR or payment type are common.
- Leave out names, account numbers and Social Security numbers, and review ChatGPT's Data controls or use Temporary Chat.
- If you are already behind on payments, contacting your creditors or a reputable nonprofit credit counselor usually comes before any chatbot plan.
ChatGPT debt payoff planning works best when you treat the chatbot as a spreadsheet assistant, not a financial counselor. It can turn a messy list of credit cards and loans into a clear table, compare the snowball and avalanche methods, and draft a monthly budget in seconds. What it cannot do is read your loan agreement, see your credit report or know your lender's current terms. This guide, based on official sources checked in October 2026 and written mainly for readers in the United States, explains what to type, how to verify the output, and when a human counselor or your creditor should come first.
What AI does well and where it falls short
Large language models are good at structure. Give them your balances, APRs and minimum payments, and they can sort the debts, calculate how much money is left after fixed expenses, and lay out several payoff orders side by side. They can also suggest spending categories to trim and write a list of questions to ask your card issuer before you call.
The weak spot is verification. A chatbot only knows what you type. If you forget a balance transfer fee, a deferred-interest promotion that is about to expire, or the fact that one loan has a variable rate, the plan will quietly leave it out. Models can also slip on arithmetic, for example by treating an annual rate as a monthly one or assuming every loan amortizes the same way. They may describe hardship programs or lender policies that have changed. That is why every AI answer about your debt should be treated as a draft you check, not a decision.
Listing debts and balances
- How useful AI is
- High
- Where to verify
- Statements, lender apps
Comparing snowball vs avalanche
- How useful AI is
- High
- Where to verify
- Re-run the same numbers yourself
Monthly interest and payoff dates
- How useful AI is
- Medium (math errors happen)
- Where to verify
- Lender's amortization schedule
Fees, promos and consolidation terms
- How useful AI is
- Low
- Where to verify
- Card agreement, written loan offers
Hardship or relief eligibility
- How useful AI is
- Low
- Where to verify
- Your creditor, a nonprofit counselor
ChatGPT debt payoff prompts that get useful answers
The quality of the answer depends on the quality of the inputs. Asking how to pay off $30,000 of debt only gets you generic advice. List each debt separately with its balance, APR, minimum payment, whether the rate is fixed or variable, and any promotional end date. Then give one realistic number for how much you can put toward debt each month. Use labels like Card A or Loan B instead of lender names; the math does not need them.
- 1
Describe each debt in numbers only
Write one line per debt, such as: Card A, $10,000 balance, 16% APR, $300 minimum. Add fees or promotional rates you know about, because the model cannot look them up for you.
- 2
Set a realistic monthly debt budget
Subtract rent, utilities, groceries, insurance and a small emergency buffer from take-home pay. A plan built on an amount you cannot actually pay will fall apart in the first tight month.
- 3
Ask for both methods side by side
Try: after paying every minimum, show a month-by-month table if extra money goes to the smallest balance first, and another if it goes to the highest APR first, with total interest for each.
- 4
Make the model show its assumptions
Ask which payment structure and monthly rate conversion it used and to print the formula. Then calculate the first month's interest on one debt yourself; if it does not match, the whole table is off.
- 5
End with questions for your creditors
Ask for a checklist of things to confirm by phone, such as whether a lower rate is available, whether a hardship plan exists, and how a payment change would be reported.
Debt snowball vs avalanche: what the AI's advice really means
Almost any chatbot will recommend one of two strategies. Both start by paying every minimum on time and differ only in where extra money goes. The CFPB's guidance explains that the highest interest rate method (often called the avalanche) eliminates your costliest debts first and can save money over time, even if progress feels slow. The snowball method targets the smallest balance first so you see progress quickly, but you may pay more overall because larger or more expensive debts wait. In both, once a debt is gone you roll its payment into the next one.
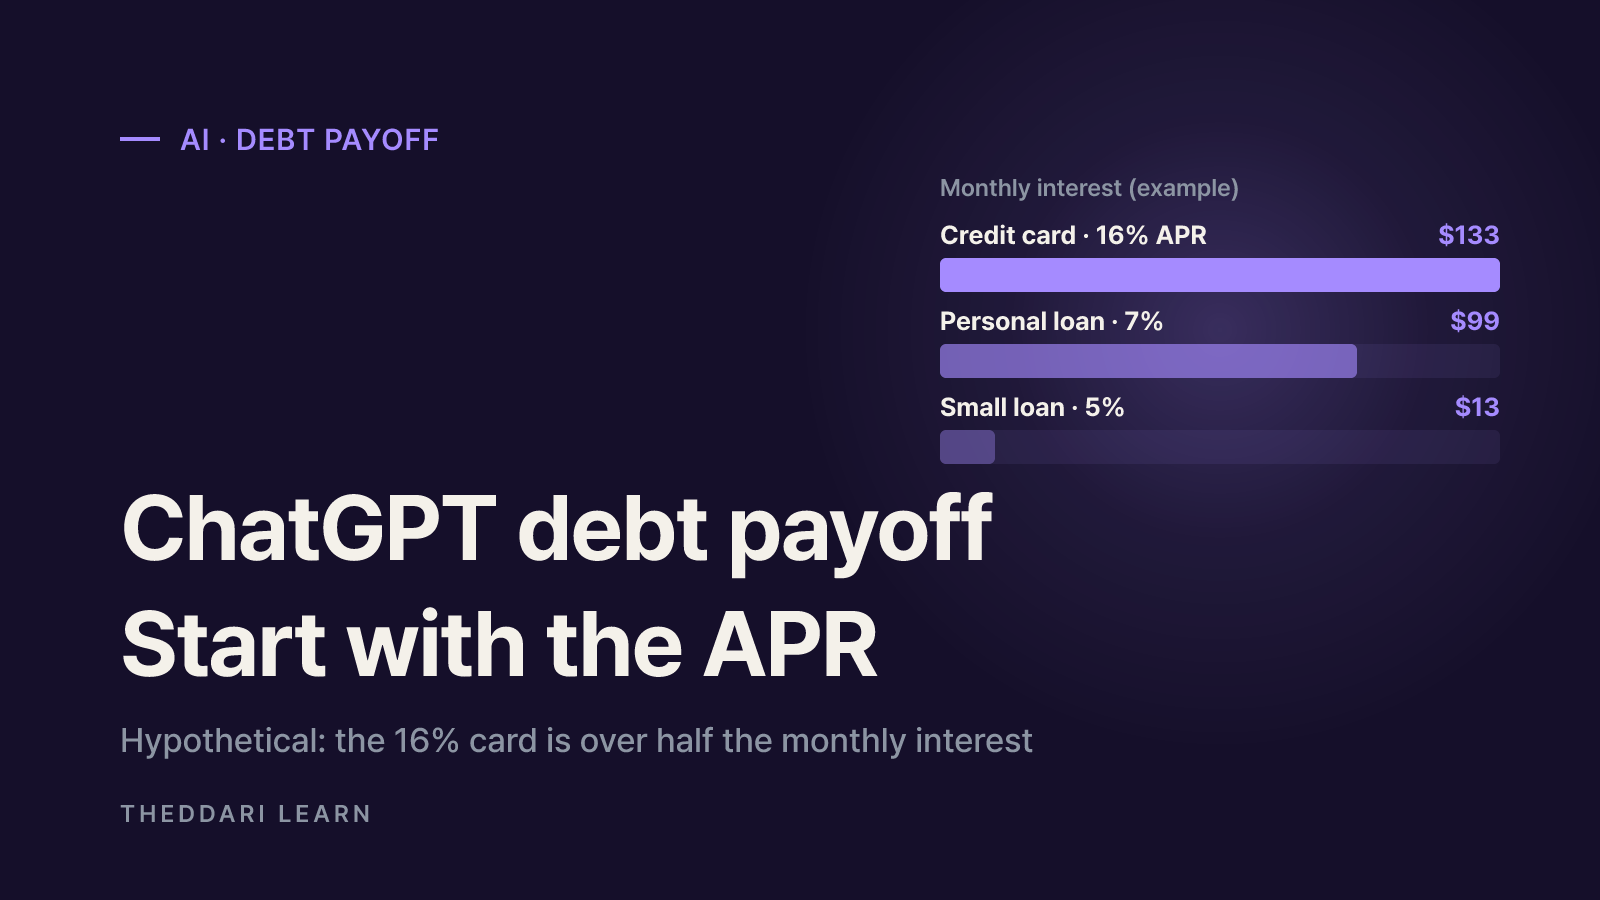
Here is a hypothetical example to make the difference concrete. Suppose you owe $30,000 in total: a $10,000 credit card at 16% APR, a $17,000 personal loan at 7%, and a $3,000 small loan at 5%. Using simple monthly estimates, the card costs about $133 a month in interest ($10,000 × 16% ÷ 12), the personal loan about $99 ($17,000 × 7% ÷ 12), and the small loan about $13 ($3,000 × 5% ÷ 12). More than half of the monthly interest comes from the card, even though it is only a third of the total balance.
Snowball (smallest balance)
- Extra money goes first to (example)
- $3,000 small loan, then card, then personal loan
- Upside
- A quick first payoff builds momentum
- Trade-off
- The 16% card keeps charging interest longer
Avalanche (highest APR)
- Extra money goes first to (example)
- 16% card, then personal loan, then small loan
- Upside
- Usually lower total interest
- Trade-off
- The first payoff takes longer
Real accounts are messier than this table. A 0% promotional balance can jump to a high rate on a specific date, some loans carry fees, and credit card minimums change as balances fall. The AI will only reflect those details if you include them, so confirm the terms before you lock in an order.
Limits of an AI debt repayment plan and privacy risks
Accuracy limits
- Chatbots may not know current rates, product terms or recent policy changes. Confirm facts with official or lender sources.
- Variable-rate balances change when benchmark rates move, so a payoff date is an estimate, not a fixed outcome.
- Unless you mention it, the model will not account for late payments already on your credit report, co-signed loans or upcoming expenses.
- If the AI suggests a consolidation loan or balance transfer, treat it as a new borrowing decision and compare real written offers.
Check your ChatGPT data settings
OpenAI's Data controls page (checked October 2026) says that turning off Improve the model for everyone under Settings > Data controls means new conversations will not be used to train OpenAI models, although they still appear in your history. Temporary chats do not appear in history, do not create memories and are not used to improve models, but may be retained for up to 30 days for safety purposes. The page also notes that if you submit thumbs-up or thumbs-down feedback after opting out, the whole conversation may be used for training. Whatever your settings, keep names, Social Security numbers, account numbers and banking screenshots out of the chat.
Be wary of anyone who contacts you claiming an AI or a new government program can wipe out your debt. The FTC says only scammers collect fees before settling any debt, promise to settle all your debts, or enroll you without first reviewing your finances.
When to talk to a person before trusting the chatbot
If you are already missing payments or cannot cover your minimums, a payoff order is not the first problem to solve. The FTC's debt guide recommends calling your creditors before a debt collector gets involved, asking about lower payments or a lower rate, and getting any agreement in writing. It also describes nonprofit credit counseling, where a counselor reviews your whole financial picture and may suggest a debt management plan for unsecured debts. Such plans require regular, on-time payments and can take 48 months or more.
The same guide flags the risks of other options an AI might mention. Debt settlement programs often tell you to stop paying creditors, which can add late fees, hurt your credit and still leave some debts unsettled; forgiven amounts may also be taxable. Consolidation loans carry their own costs, and some put your home on the line. Bankruptcy information can stay on a credit report for 10 years. For readers in Korea, the Credit Counseling and Recovery Service runs separate programs based on how long payments are overdue (30 days or less, 31 to 89 days, or 90 days or more), so check its official comparison rather than relying on a general answer.
Track rate events and AI news on theddari
If you carry variable-rate debt, knowing when central banks announce rate decisions helps you anticipate when your interest costs might be reviewed. theddari's economic calendar lists scheduled releases; it does not predict where rates will go. To follow changes in AI tools and their data policies, browse the AI channel trends on theddari and confirm anything important in the company's own help pages.

A final checklist before you follow an AI plan
- Did you confirm each balance, APR, minimum payment, fee and promo end date from your statements?
- Did you share only anonymous numbers with the chatbot?
- Did you check the model's assumptions and recompute the first month's interest yourself?
- Are all minimum payments covered before any extra payment goes to a target debt?
- If you are behind, have you contacted your creditors or a reputable nonprofit credit counselor?
- Have you compared any consolidation or refinancing idea using real written offers?
Used this way, an AI chatbot can make the first step of facing your debt less overwhelming. The accuracy of the plan still depends on the numbers you feed it and the checks you run afterward, and when payments are already slipping, a conversation with your creditor or a qualified counselor should come before a conversation with a chatbot.
常见问题
Is it safe to give ChatGPT my debt balances and interest rates?
Which saves more money, the debt snowball or the debt avalanche?
Can I trust the payoff date ChatGPT calculates?
Should I follow an AI suggestion to consolidate my debt?
What should I do first if I'm already behind on payments?
来源与参考资料
- 1CFPB: How to reduce your debt (snowball vs highest interest rate method)(在新标签页中打开)www.consumerfinance.gov
- 2FTC Consumer Advice: How To Get Out of Debt(在新标签页中打开)consumer.ftc.gov
- 3OpenAI Help Center: Data controls in ChatGPT(在新标签页中打开)help.openai.com
- 4Credit Counseling and Recovery Service (Korea): Debt adjustment program comparison(在新标签页中打开)www.ccrs.or.kr
相关文章
 AI
Anthropic's Riemann Hypothesis Proof: Is It Verified?
On November 20, 2026, Anthropic researcher Levent Alpöge said he had proved the Riemann Hypothesis with Claude. A day later the Lean and Mathlib communities certified the formal proof. What that means, what is still missing, and a checklist for judging big proof claims.
 AI
AgentRoboCritic: Can Frontier AI Agents Control Robots?
A November 2026 arXiv study from Carnegie Mellon, UIUC and Bosch scores every action a frontier AI agent sends to a robot. Here is what it found about recovery, grasping, alignment, zero-shot success and latency, and how far to trust it.
 AI
Inkling 2 Mini vs Inkling 2 Small: Specs, Local Use, Limits
Thinking Machines released Inkling 2 Mini on November 20, 2026: a 26.4B-parameter open-weights model with a ~20GB checkpoint that runs on 32GB Macs. Here is how it compares with Inkling 2 Small and what to check before you deploy it.