Pension Savings Account Korea No Income: Should Homemakers and Non-Earners Open One?
No income means no tax credit, yet a Korean pension savings account still offers tax deferral, 3.3-5.5% pension tax and tax-free principal (Oct 2026).
目录8 个章节
核心要点
- Korean tax residents with no income can open and fund a pension savings account (yeongeum jeochuk), but they get no 13.2-16.5% tax credit because there is no income tax to reduce.
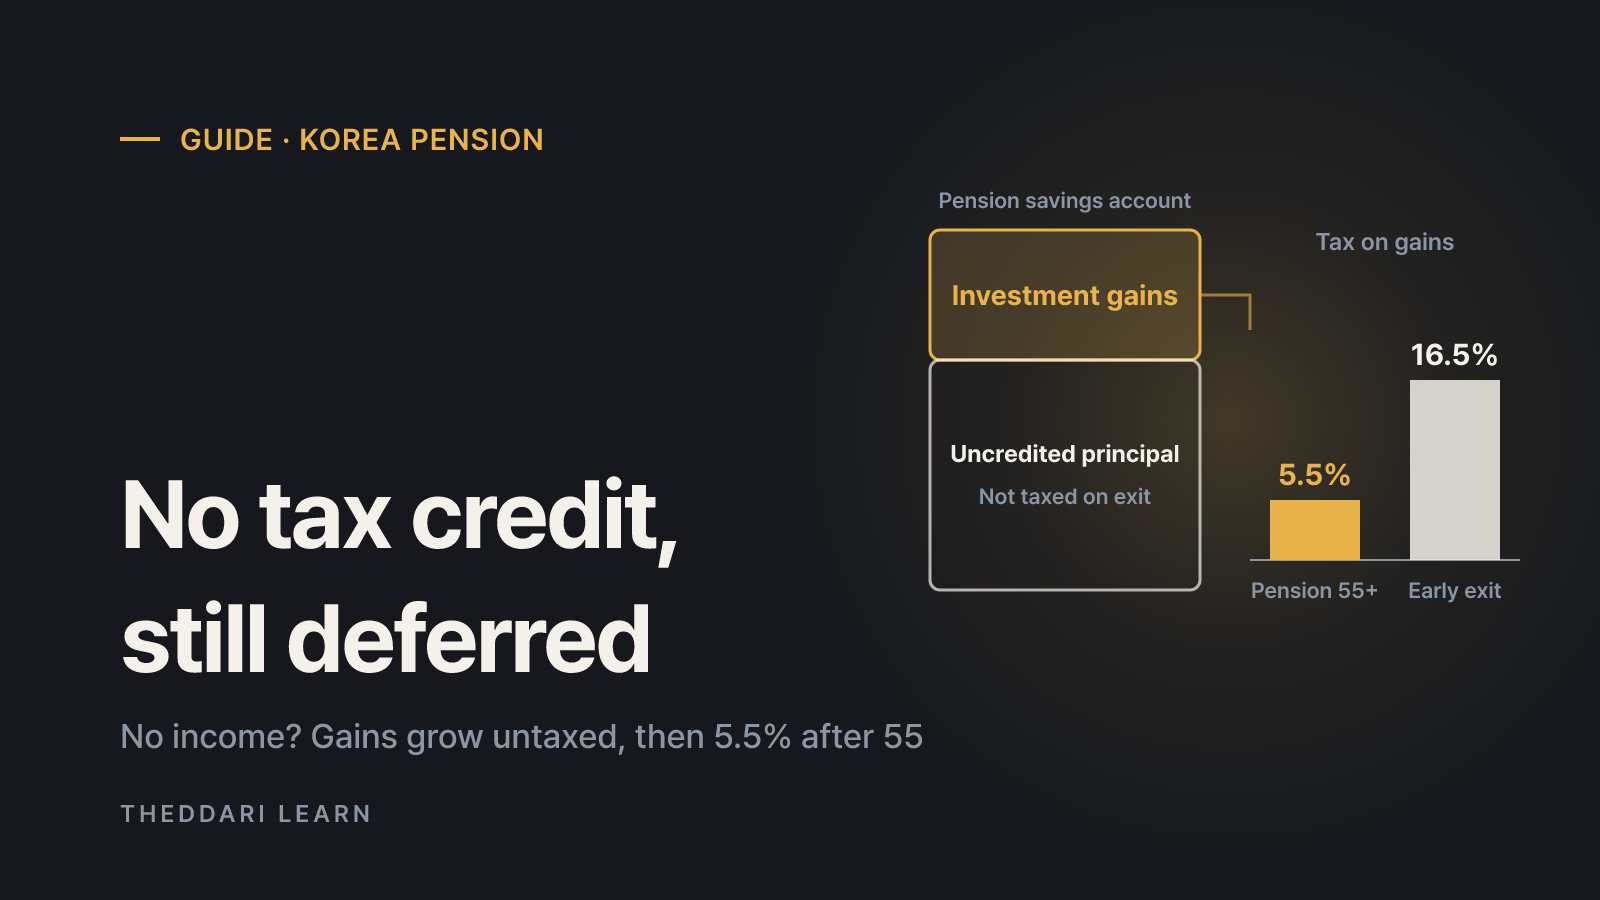
- Investment gains inside the account are not taxed until withdrawal, and gains paid out as a pension after age 55 are taxed at 3.3-5.5% including local tax.
- Contributions that never received a credit are 'tax-excluded' principal: they come out first and are not taxed, even before age 55.
- If you start earning later, you can ask the provider to reclassify old uncredited contributions as that year's payment and claim the credit then.
- Gains withdrawn early are taxed at 16.5%, and pension savings insurance products can charge surrender deductions in roughly the first seven years.
Short answer on a pension savings account Korea no income setup: you can open one, but you will not get the headline tax refund. What you still get is tax deferral on investment gains, a low 3.3-5.5% tax if those gains are paid out as a pension after age 55, tax-free access to the principal you put in, and the option to turn old contributions into a tax credit if you start earning later. The trade-off is a 16.5% tax on gains taken out early and, for insurance-type products, surrender costs. This guide covers Korean tax residents and reflects rules checked against National Tax Service (NTS), Ministry of Government Legislation and Financial Services Commission (FSC) pages as of October 2026.
Pension savings account Korea no income: who can open one
A Korean pension savings account, called yeongeum jeochuk, is a tax-qualified account sold by brokers, banks and insurers. The NTS pension income guide sets two main contribution conditions: total payments into all pension accounts must stay within KRW 18 million a year (with separate room for maturing ISA transfers), and you must stop contributing once you have applied to start pension payouts. Nothing in those conditions requires wages or business income, so homemakers, job seekers and early retirees can all open and fund an account.
The tax credit is where income matters. According to the government's Easylaw guide, up to KRW 6 million of annual pension savings contributions earns a credit of 16.5% if total salary is KRW 55 million or less (or other comprehensive income is KRW 45 million or less) and 13.2% above that. A credit can only reduce tax you owe. The Korea Taxpayers Association notes that any credit exceeding computed tax is treated as not taken. That uncredited money does not vanish; it becomes a 'tax-excluded' balance, which is the key to why the account can still make sense.
A spouse cannot borrow your account for their credit
The credit is personal. Money paid into an account held by a spouse or dependant is excluded from the earner's credit. Households usually fill the earning spouse's own pension accounts first, because that is where the refund is, and then direct spare long-term savings to the non-earning spouse's account.
Four benefits that remain without the tax credit
1. Tax deferral on gains
In a regular brokerage account, ETF distributions and dividends are taxed at source each time they are paid. Inside a pension savings fund account, the same income is not taxed until you withdraw it. Easylaw states that contributions above the credit limit receive no credit but still get deferral until withdrawal and lower tax when taken as a pension. Money that would have gone to tax stays invested, so the gap can widen over long periods. If the account earns nothing, there is nothing to defer, so the size of this benefit depends entirely on investment results.
2. Low pension tax after 55
Gains withdrawn after the account is five years old, after age 55 and within the annual pension limit are taxed as pension income. The NTS withholding page sets the national rates below; the figures here add the 10% local income tax surcharge.
Pension payout, under 70
- Rate incl. local tax
- 5.5%
- Notes
- After 55, account 5+ years old, within limit
Pension payout, 70 to 79
- Rate incl. local tax
- 4.4%
- Notes
- Lower rate applies if age and life-annuity tests overlap
Pension payout, 80 and over
- Rate incl. local tax
- 3.3%
Life annuity that cannot be cancelled
- Rate incl. local tax
- 3.3%
- Notes
- For payouts from Jan 1, 2026 (previously 4.4%)
Early or excess withdrawal
- Rate incl. local tax
- 16.5%
- Notes
- Other income, taxed separately
Withdrawal for an unavoidable reason
- Rate incl. local tax
- 3.3-5.5%
- Notes
- Death, emigration, 3+ months of medical care, etc.
As an illustration, take KRW 10 million of gains. Paid out as a pension before 70, the tax is KRW 550,000. Withdrawn early, it is KRW 1.65 million, three times as much.
3. Uncredited principal comes out first and tax-free
The NTS treats partial withdrawals as coming from three layers in order: tax-excluded amounts, then deferred severance pay, then credited contributions plus earnings. For someone with no income, almost all contributions sit in the first layer. That means you can pull out up to your principal in an emergency without tax, while the gains stay invested for retirement. The withdrawal-order rule is why a non-earner's account is less illiquid than it looks.
Contributions with no tax credit
- Pension payout (55+, within limit)
- Not taxed
- Early withdrawal or closure
- Not taxed
Investment gains
- Pension payout (55+, within limit)
- Pension tax 3.3-5.5%
- Early withdrawal or closure
- Other income 16.5%
(For comparison) credited contributions
- Pension payout (55+, within limit)
- Pension tax 3.3-5.5%
- Early withdrawal or closure
- Other income 16.5%
4. A later credit if you return to work
Article 118-3 of the Income Tax Act Enforcement Decree lets an account holder ask the provider to reclassify contributions from earlier years that never received a credit as payments made in the current year. The provider treats that amount as withdrawn first and re-paid on the request date, and it becomes eligible for that year's credit. Someone who saved KRW 12 million while out of work could, after finding a job, convert KRW 6 million and fill that year's pension savings credit limit without putting in fresh cash. The converted sum still counts toward the KRW 18 million annual contribution cap.
Opening early also starts the five-year clock needed for pension treatment. The FSC points out that moving to another provider through an account transfer, rather than closing and reopening, keeps the original opening date.
Downsides and risks
- 16.5% on early gains: taking out more than your principal before 55, or above the pension limit, is taxed as other income at 16.5%, which can be higher than what a regular account would have cost.
- Annual pension limit: the limit is account value divided by (11 minus the payout year), times 120%. In year one that is 12% of the balance; anything above is taxed as an early withdrawal. The limit disappears from year 11.
- Insurance surrender costs: the FSC warns that pension savings insurance closed within roughly seven years can incur surrender deductions, and early balances can sit below what you paid in because of fees.
- Fund losses: fund and ETF accounts are not principal-protected and are not covered by deposit insurance. The FSC's 29.3% one-year return for funds and ETFs in 2025 reflected a strong stock market and is not a long-run expectation.
- KRW 15 million threshold: if taxable private pension income exceeds KRW 15 million a year, you choose between comprehensive taxation and a 15% separate rate plus local tax.
- Long lock-up: the tax advantages need you to wait until after 55, so money for housing, education or other goals within five to ten years usually belongs elsewhere.
Withdrawals for reasons the NTS classes as unavoidable are taxed at pension rates. These include natural disasters, the holder's death or emigration, three or more months of medical care for the holder or a dependant, hospitalisation of 15+ days due to a disaster, bankruptcy and the provider's business suspension. Evidence must reach the provider within six months.
Who it suits and who it does not
| Situation | What to weigh |
|---|---|
| Non-earner with spare savings and 10+ years until 55 | Enough time for deferral and low pension tax to matter |
| Career-break homemaker likely to return to work | Today's contributions can be converted to a credit later |
| Household where the earner has unused credit room | Fill the earner's own account first for the refund |
| Thin emergency fund or money needed within 5 years | Principal is tax-free to withdraw, but losses and surrender costs still bite |
| Low tolerance for losses | Insurance products protect principal but assume you hold long-term |
Steps before you open an account
- 1
Separate emergency and short-term money
Keep several months of expenses and anything needed within five years outside the pension account.
- 2
Choose the product type
Pension savings funds allow flexible payments and self-directed ETFs; pension savings insurance requires regular payments and offers principal protection. Compare fees and returns on the FSS integrated pension portal.
- 3
Record uncredited contributions
Note what you paid each year without a credit and confirm with the provider that the tax-excluded balance is recorded before any withdrawal.
- 4
Request conversion when income starts
In the first year you earn, ask the provider to convert earlier uncredited contributions to that year.
- 5
Plan payouts after 55
Check the yearly limit and the KRW 15 million threshold before choosing how long to spread payments.
If you invest through ETFs in a pension fund account, rate and inflation releases can move both bond and equity funds. TheDdari's economic calendar shows when those releases land, and the stock Telegram trends page summarises what market channels are discussing. Neither tool forecasts returns; they help you review a regular investment plan with the schedule in view.

Bottom line
For a Korean resident with no income, a pension savings account is not a refund account; it is a tax-deferral account. You keep deferral on gains, 3.3-5.5% tax on pension payouts after 55, tax-free first access to uncredited principal, the option of a later credit conversion and an early start on the five-year rule. If you may need gains before 55, might cancel an insurance contract early or cannot accept losses, a regular brokerage account or deposit can be the better fit. Korean tax rules change often, so recheck NTS and provider guidance right before you open the account or withdraw.
常见问题
Can a stay-at-home spouse with zero income open a Korean pension savings account?
Can my working spouse claim the credit for money paid into my pension savings account?
Is it tax-free to withdraw uncredited contributions before 55?
If I get a job later, can I still get a credit for money I put in while unemployed?
Does this apply to foreigners living in Korea?
来源与参考资料
- 1National Tax Service: Scope of pension income (contribution rules and withdrawal order)(在新标签页中打开)www.nts.go.kr
- 2National Tax Service: Withholding on pension income(在新标签页中打开)www.nts.go.kr
- 3Ministry of Government Legislation Easylaw: Pension savings(在新标签页中打开)www.easylaw.go.kr
- 4Korea Law Information Center: Income Tax Act Enforcement Decree Article 118-3(在新标签页中打开)law.go.kr
- 5Financial Services Commission: 2025 Pension Savings Account white paper (June 18, 2026)(在新标签页中打开)www.fsc.go.kr
- 6Korea Taxpayers Association: Pension account tax credit guide(在新标签页中打开)www.koreatax.org
相关文章
 投资指南
Stock Market Circuit Breakers and Sidecars: US vs Korea
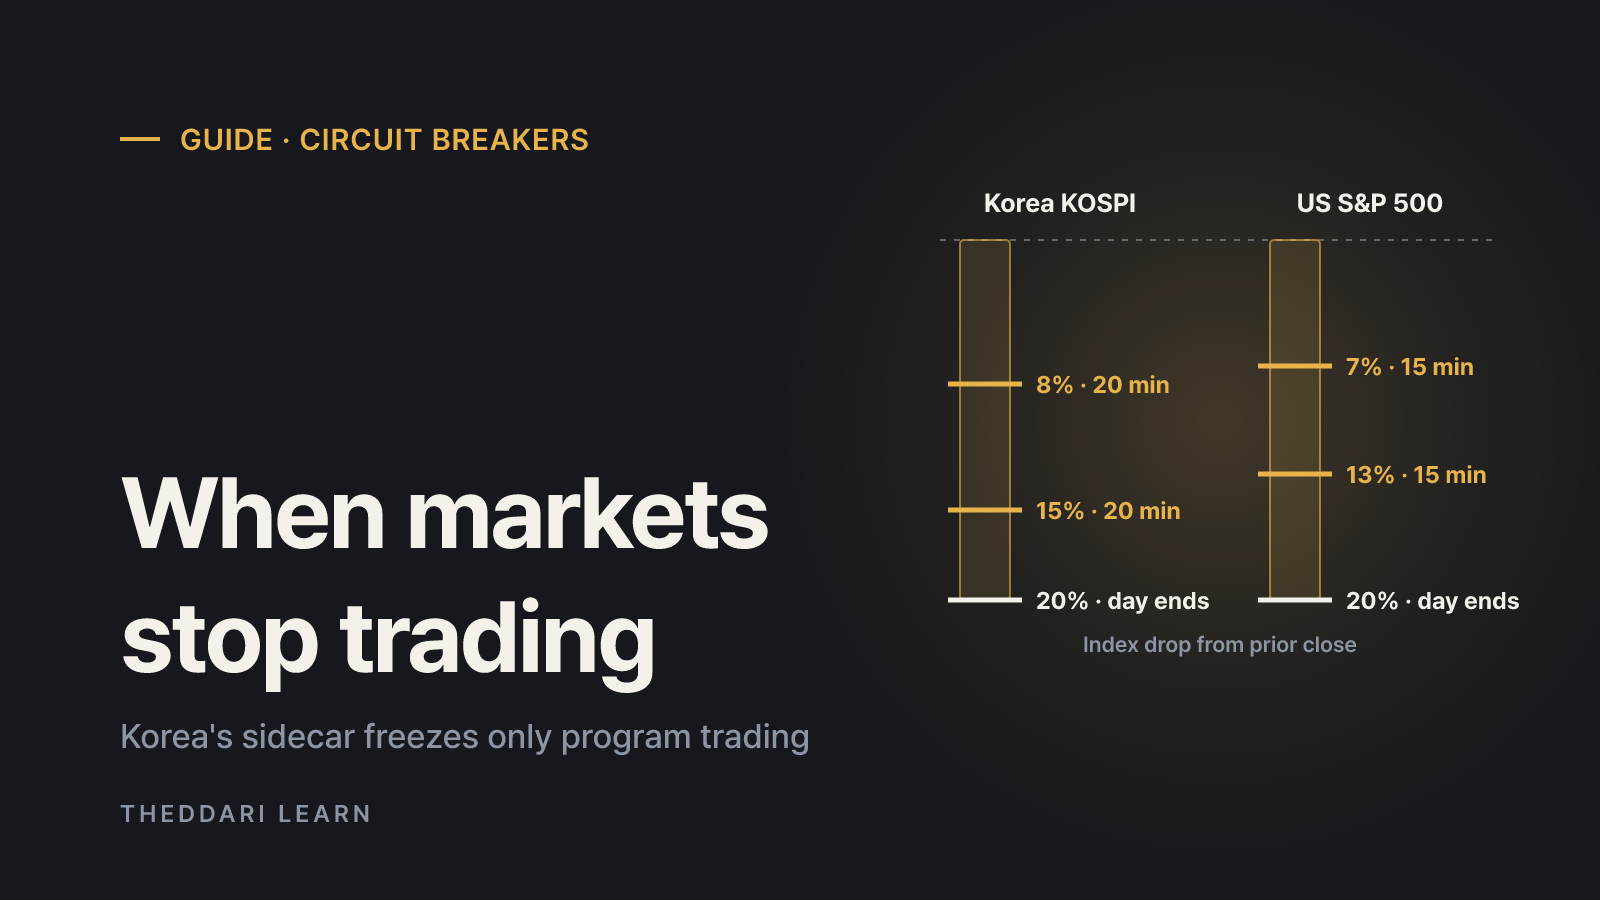
US market-wide circuit breakers halt all trading when the S&P 500 drops 7%, 13% or 20%. Korea uses 8%, 15% and 20% thresholds plus a sidecar that freezes only program trading. Here is how each rule works and what happens to your orders.
 投资指南
Pension Withdrawal Order in Korea: How IRP Money Is Taxed
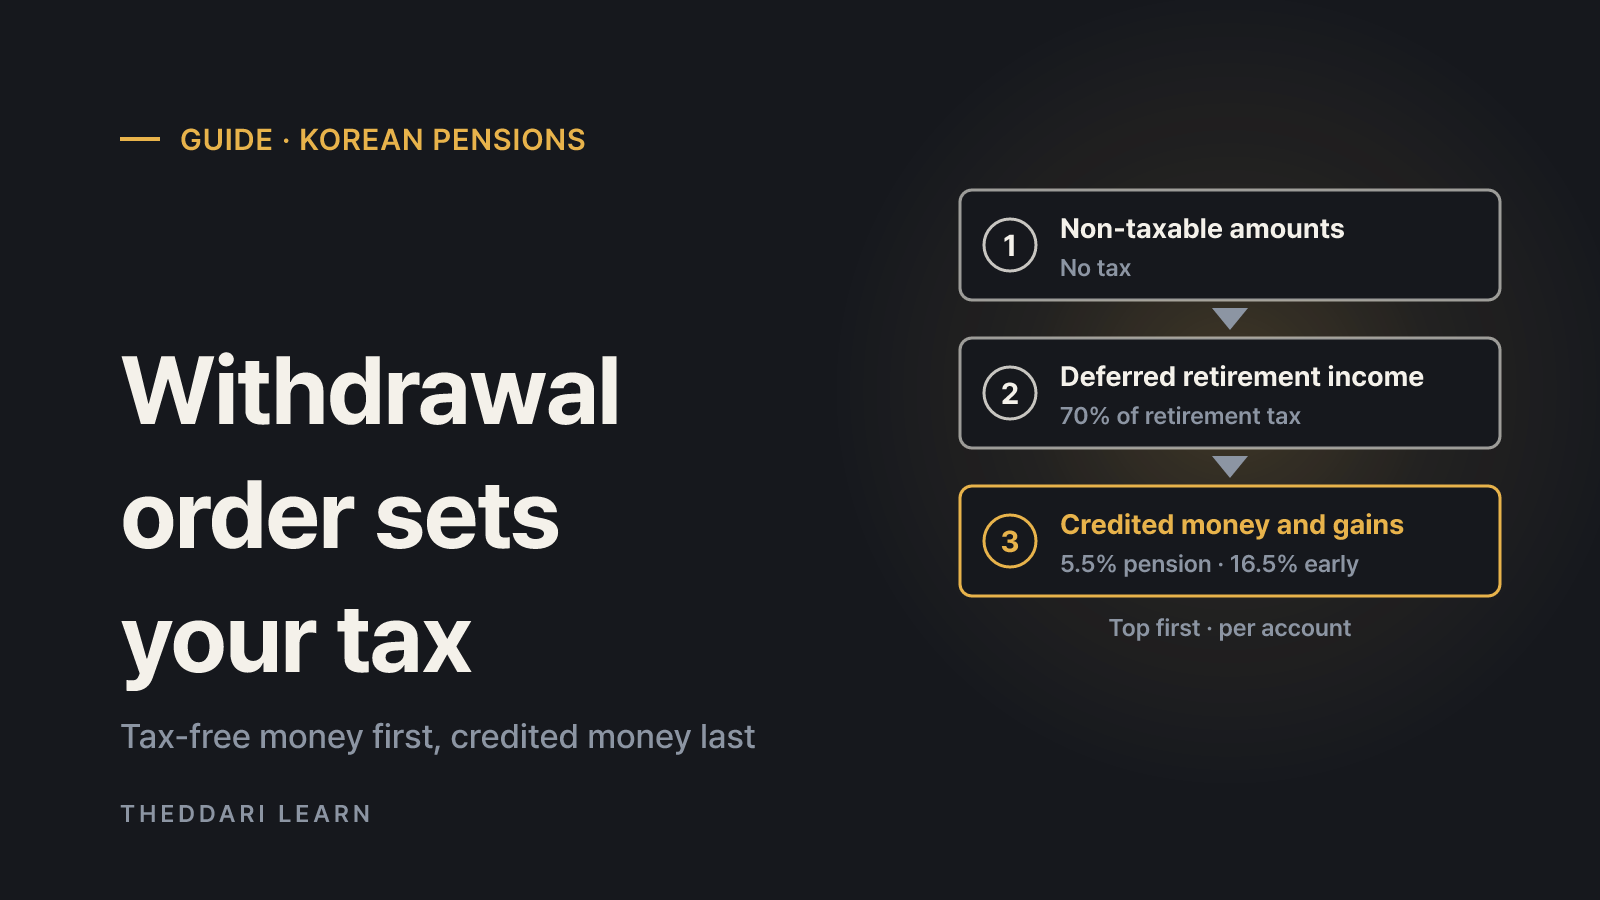
When you take part of the money out of a Korean pension savings account or IRP, the law decides which money left first, and each part is taxed differently. A November 2026 guide to the withdrawal order, rates and exceptions for Korean tax residents.
 投资指南
How to Buy ETFs in Singapore: CDP vs Custodian and Fees
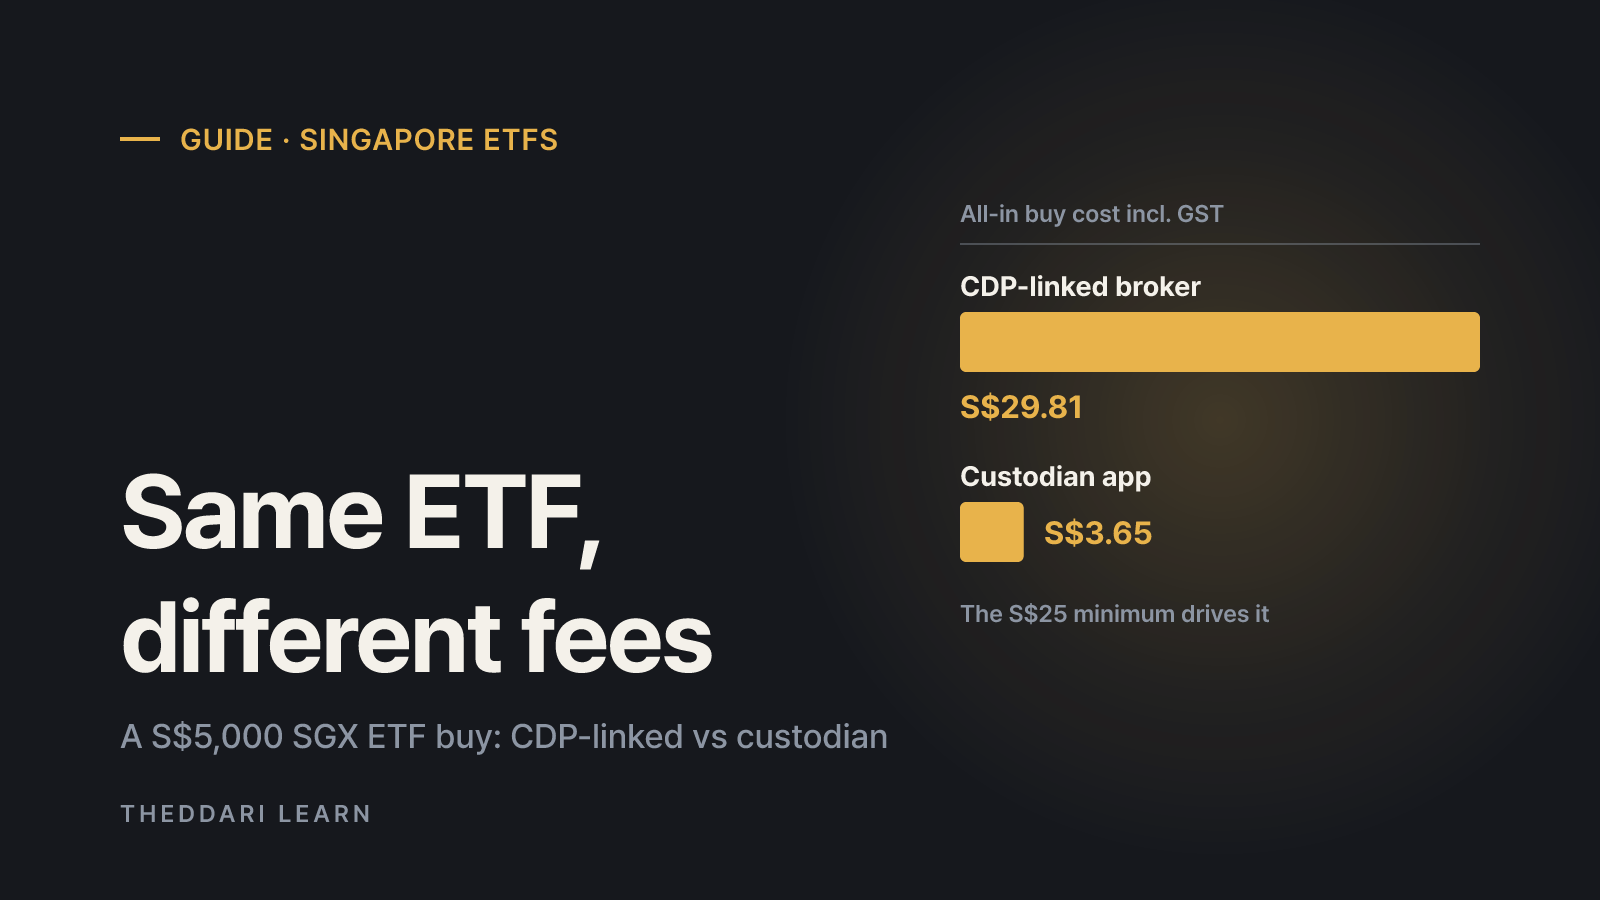
A practical guide for Singapore residents: how SGX-listed and US-listed ETFs are held, what the CDP rule changes of July 2026 mean for custodian accounts, and what a trade really costs at different order sizes.