2 Million Won Monthly Dividend Income: Capital and Korea Tax
How much capital you need for 2 million won a month in dividends at 3–10% yields, plus Korea's 15.4% dividend tax, the 20M won threshold and 2026 rules.
目录9 个章节
- How to calculate the capital for monthly dividend income
- Capital needed by dividend yield
- Korea dividend tax: 15.4% withholding and the 20M won threshold
- What changed in 2026: high-dividend separate taxation
- Do not forget national health insurance
- Risks of chasing high yield to cut the capital
- Run your own numbers step by step
- 常见问题
- 来源与参考资料
核心要点
- Capital needed = annual dividend target ÷ dividend yield. 2 million won a month before tax (24 million won a year) needs 600 million won at 4% and 480 million won at 5%.
- Korean residents have 15.4% withheld from domestic dividends (14% income tax plus 1.4% local tax), so 2 million won gross becomes about 1.69 million won a month.
- To net 2 million won a month you need about 28.37 million won a year before tax, or roughly 567 million won of capital at a 5% yield.
- If interest plus dividends exceed 20 million won a year, the excess is added to your other income and taxed at progressive rates of 6–45% plus local tax.
- From 2026, dividends from qualifying high-dividend listed companies can be taxed separately at 14–30%, but only if you apply, and funds and ETF distributions are excluded.
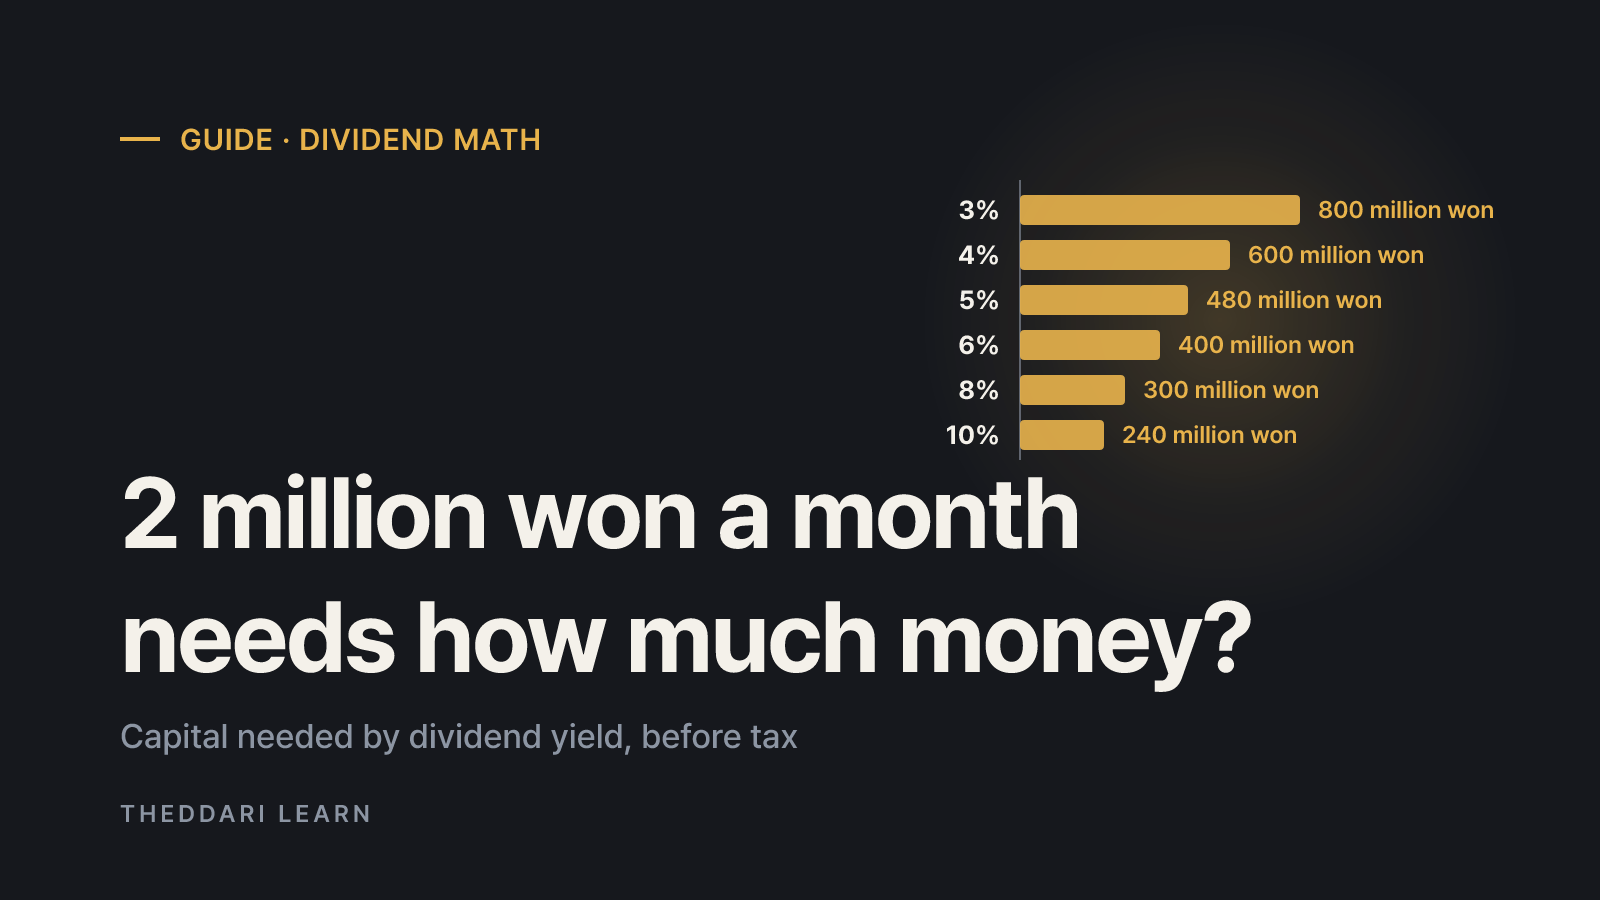
To earn 2 million won of monthly dividend income before tax, you need about 600 million won at a 4% yield, 480 million won at 5%, or 400 million won at 6%. If you want 2 million won to land in your account after tax, the bar rises to roughly 567 million won at 5%. This guide uses Korean tax rules as of October 2026 and applies to Korean tax residents receiving dividends from Korean companies and Korean-listed funds. It walks through the formula, a yield-by-yield table, the 15.4% withholding tax, the 20 million won financial income threshold and the high-dividend separate taxation that started in 2026.
Two points matter most. First, 24 million won a year of dividends is already above the 20 million won line that triggers comprehensive taxation. Second, a higher yield lowers the capital you need on paper, but it also raises the odds of dividend cuts and capital losses. Taxes, health insurance and the durability of the payout belong in the same calculation.
How to calculate the capital for monthly dividend income
The formula is simple: capital needed = annual dividend target ÷ dividend yield. Two million won a month for 12 months is 24 million won a year. At a 4% yield, 24 million ÷ 0.04 = 600 million won. Dividend yield here means the dividends paid over the last year divided by today's price. It describes the past, not a promise about future payouts.
For an after-tax target, adjust for withholding first. Korean residents have 15.4% withheld from domestic dividends, made up of 14% national income tax and 1.4% local income tax. To keep 24 million won after tax, you need 24 million ÷ 0.846 ≈ 28.37 million won of gross dividends. Divide that gross amount by the yield to get the after-tax capital requirement.
The examples assume a flat payout every year and only the 15.4% withholding. Comprehensive taxation, foreign withholding, fees, currency moves and dividend changes will all shift real results.
Capital needed by dividend yield
The table compares the capital needed for 2 million won a month on a gross basis and on a net basis. The net column only reflects the 15.4% withholding.
3%
- Capital for 2M won/month (gross)
- 800 million won
- Capital for 2M won/month (net)
- ≈ 946 million won
- What this range usually means
- Large caps and broad index funds
4%
- Capital for 2M won/month (gross)
- 600 million won
- Capital for 2M won/month (net)
- ≈ 709 million won
- What this range usually means
- Balance of income and dividend growth
5%
- Capital for 2M won/month (gross)
- 480 million won
- Capital for 2M won/month (net)
- ≈ 567 million won
- What this range usually means
- Common for high-dividend stocks and ETFs
6%
- Capital for 2M won/month (gross)
- 400 million won
- Capital for 2M won/month (net)
- ≈ 473 million won
- What this range usually means
- Payout durability matters more
7%
- Capital for 2M won/month (gross)
- ≈ 343 million won
- Capital for 2M won/month (net)
- ≈ 405 million won
- What this range usually means
- Often inflated by price drops
8%
- Capital for 2M won/month (gross)
- 300 million won
- Capital for 2M won/month (net)
- ≈ 355 million won
- What this range usually means
- Check covered-call or REIT structures
10%
- Capital for 2M won/month (gross)
- 240 million won
- Capital for 2M won/month (net)
- ≈ 284 million won
- What this range usually means
- High risk of cuts and capital erosion
The gap between a 3% and a 10% yield is 560 million won of capital on a gross basis, but that saving is not free. High yields usually come from paying out a large share of earnings or from a share price that has already fallen. A 3% portfolio and a 10% portfolio are not equally stable, so compare them with that in mind.
Decide whether your goal is gross or net
Most popular videos and posts about earning 2 million won a month quote gross figures. Gross 2 million won becomes about 1.69 million won after withholding. If your budget is based on cash you can spend, use the net column, and expect your gross financial income to reach about 28.37 million won, which brings comprehensive taxation into play.
Korea dividend tax: 15.4% withholding and the 20M won threshold
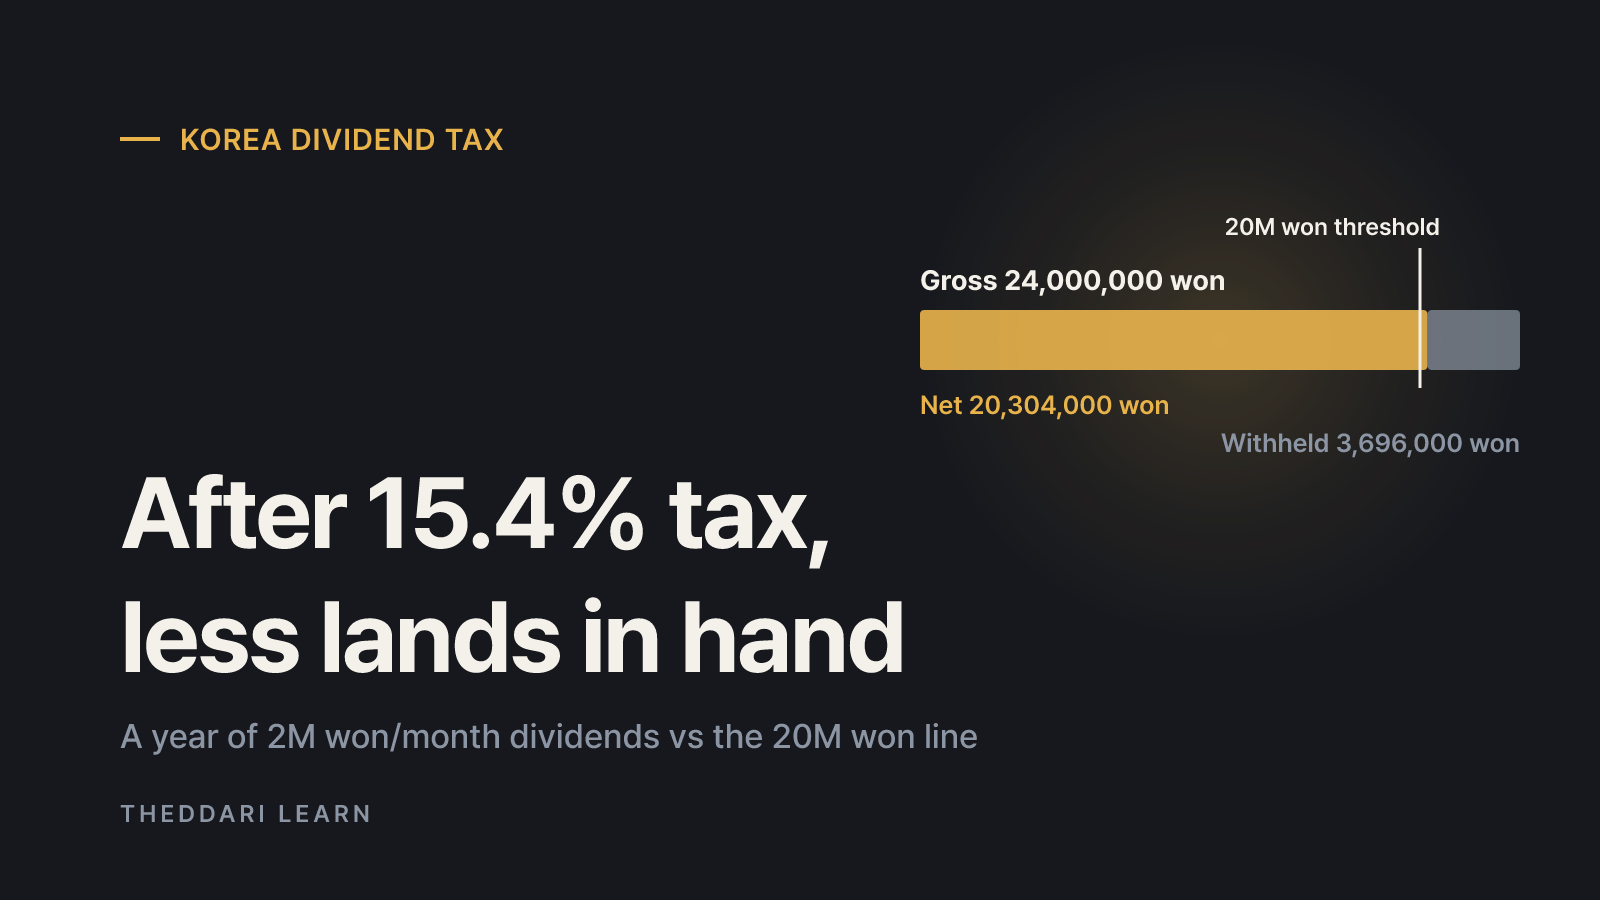
According to a March 2026 National Tax Service release, when interest and dividends together are 20 million won or less a year, they are taxed separately at 14%. Above that, the income is combined with wages and other income and taxed at 6–45%, with local tax on top. You report it in the comprehensive income tax filing each May for the previous year.
Target 2M won/month gross
- Gross dividends per year
- 24,000,000 won
- 15.4% withheld
- 3,696,000 won
- Net per year
- 20,304,000 won
- Net per month
- ≈ 1,692,000 won
Target 2M won/month net
- Gross dividends per year
- ≈ 28,370,000 won
- 15.4% withheld
- ≈ 4,370,000 won
- Net per year
- 24,000,000 won
- Net per month
- 2,000,000 won
Stay at the threshold
- Gross dividends per year
- 20,000,000 won
- 15.4% withheld
- 3,080,000 won
- Net per year
- 16,920,000 won
- Net per month
- ≈ 1,410,000 won
Under comprehensive taxation, the first 20 million won is still calculated at 14% and only the excess is added to your other income at progressive rates. Tax already withheld is credited. A retiree with little other income may owe little extra, while someone with a high salary may see the excess taxed at a much higher rate.
The threshold is per person
The 20 million won test applies to each individual. If spouses each receive 12 million won a year in their own names, each stays under the line and the 14% withholding is final, while the household still collects 2 million won a month gross. Moving money to a spouse can raise gift tax questions, so check gift tax allowances and reporting first.
What changed in 2026: high-dividend separate taxation
For dividends paid from 1 January 2026, Korea introduced a special separate taxation rule for dividends from high-dividend companies. The National Tax Service says that dividends from qualifying listed companies can be taxed apart from other income at lower rates, even when your total financial income exceeds 20 million won, provided you apply when filing.
| Qualifying dividends | Tax (local tax extra) |
|---|---|
| Up to 20 million won | 14% |
| 20 million to 300 million won | 2.8 million won + 20% of the excess over 20 million |
| 300 million to 5 billion won | 58.8 million won + 25% of the excess over 300 million |
| Above 5 billion won | 1,233.8 million won + 30% of the excess over 5 billion |
- Which companies: listed companies that did not cut dividends and have a payout ratio of at least 40%, or at least 25% with dividends raised 10% or more year on year. Companies disclose their status on the Korea Exchange KIND system.
- How long: it covers dividends paid in 2026 through 2029, reported in the May filings from 2027 to 2030.
- Not automatic: you must submit a separate taxation application with your filing. Once applied, those dividends are also excluded from the 20 million won test.
- Exclusions: according to Maeil Shinmun, funds, REITs and equity ETF distributions do not qualify even if the underlying holdings do.
Say all of the roughly 28.37 million won needed for a net 2 million won a month came from qualifying companies. With separate taxation, national tax would be 2.8 million won plus 20% of about 8.37 million won, or roughly 4.47 million won, with local tax added. That helps high earners most. Investors with little other income may do better under ordinary comprehensive taxation, and the National Tax Service lets you choose the better option.
Do not forget national health insurance
Many retirees planning dividend income are registered as dependents on a working child's health insurance. Under National Health Insurance Service rules, a dependent's total income from business, financial assets, pensions and wages must be 20 million won or less a year, or 10 million won or less if their property tax base is above 540 million won and up to 900 million won. Both spouses must qualify.
Gross dividends of 24 million won break that limit, which can move you into the regional subscriber category with monthly premiums. A Maeil Shinmun report from 13 October 2026 notes that applying for separate taxation does not automatically remove dividends from the health insurance income count, and that guidance on this point had not been finalized. Leave premiums out and your budget can be badly off.
Risks of chasing high yield to cut the capital
- Dividend cuts: when profits fall, payouts usually fall first. If a 300 million won portfolio at 8% has its payout cut by a quarter, gross income drops to 1.5 million won a month.
- Yield illusion: a sharp price drop makes the trailing yield look high. Check earnings and payout ratios to see whether last year's dividend can be repeated.
- Return of capital: some fund and ETF distributions partly hand back your own money. If the net asset value keeps sliding while you collect, your principal is shrinking.
- Inflation: a flat 2 million won buys less every year. Without dividend growth, a pure high-yield portfolio may not protect long-term living costs.
- Concentration: high yields cluster in financials, telecoms and energy, so one sector shock can hit both income and price.
Dividend decisions usually arrive with earnings reports. Tracking your holdings' report dates and big macro events such as rate decisions makes payout changes less of a surprise.

Run your own numbers step by step
- 1
Set a net target
Start from the cash you actually need each month and divide by 0.846 to find the gross target. A net 2 million won a month needs about 28.37 million won a year gross.
- 2
Use a conservative yield
Base the math on several years of average payouts and payout ratios rather than today's yield, so a cut does not break the plan.
- 3
Check the 20M won line
See whether gross interest plus dividends exceed 20 million won and what rate the excess would face with your other income. Consider gift tax before splitting assets with family.
- 4
Check high-dividend status
Look up whether your holdings are disclosed as high-dividend companies on KIND, then compare separate and comprehensive taxation before the May filing.
- 5
Add health insurance
Confirm whether you keep dependent status, and estimate regional premiums with the National Health Insurance Service calculator.
In short, 2 million won a month needs 480–600 million won at a 4–5% yield before tax, or about 567–709 million won after tax. You can follow market chatter on the stock Telegram trends page. Tax rates and health insurance rules can change, so recheck the National Tax Service and National Health Insurance Service before acting.
常见问题
How much tax is withheld on Korean dividends?
Is the 20 million won threshold measured before or after tax?
Does the 2026 high-dividend separate taxation remove the threshold problem?
Do these rules apply to foreign investors or US dividend stocks?
Is a 10% yield a safe way to cut the capital needed?
来源与参考资料
- 1National Tax Service (Korea): Separate taxation of dividends from high-dividend companies, press release (9 March 2026)(在新标签页中打开)www.nts.go.kr
- 2National Health Insurance Service: Income and asset requirements for dependents(在新标签页中打开)www.nhis.or.kr
- 3Maeil Shinmun: Dividend separate taxation tops out at 30%, health insurance is separate (13 October 2026)(在新标签页中打开)www.imaeil.com
相关文章
 投资指南
Stock Market Circuit Breakers and Sidecars: US vs Korea
US market-wide circuit breakers halt all trading when the S&P 500 drops 7%, 13% or 20%. Korea uses 8%, 15% and 20% thresholds plus a sidecar that freezes only program trading. Here is how each rule works and what happens to your orders.
 投资指南
Pension Withdrawal Order in Korea: How IRP Money Is Taxed
When you take part of the money out of a Korean pension savings account or IRP, the law decides which money left first, and each part is taxed differently. A November 2026 guide to the withdrawal order, rates and exceptions for Korean tax residents.
 投资指南
How to Buy ETFs in Singapore: CDP vs Custodian and Fees
A practical guide for Singapore residents: how SGX-listed and US-listed ETFs are held, what the CDP rule changes of July 2026 mean for custodian accounts, and what a trade really costs at different order sizes.