Capital Gains Tax in Korea: How Domestic and Foreign Stock Gains Are Taxed
How Korea taxes stock gains: listed Korean shares only for major shareholders, foreign stocks for all residents. Rates, deduction and May filing explained.
目录6 个章节
核心要点
- For Korean tax residents, listed Korean shares sold on the exchange by small shareholders are outside capital gains tax; major shareholders, off-exchange sales and unlisted shares are taxed.
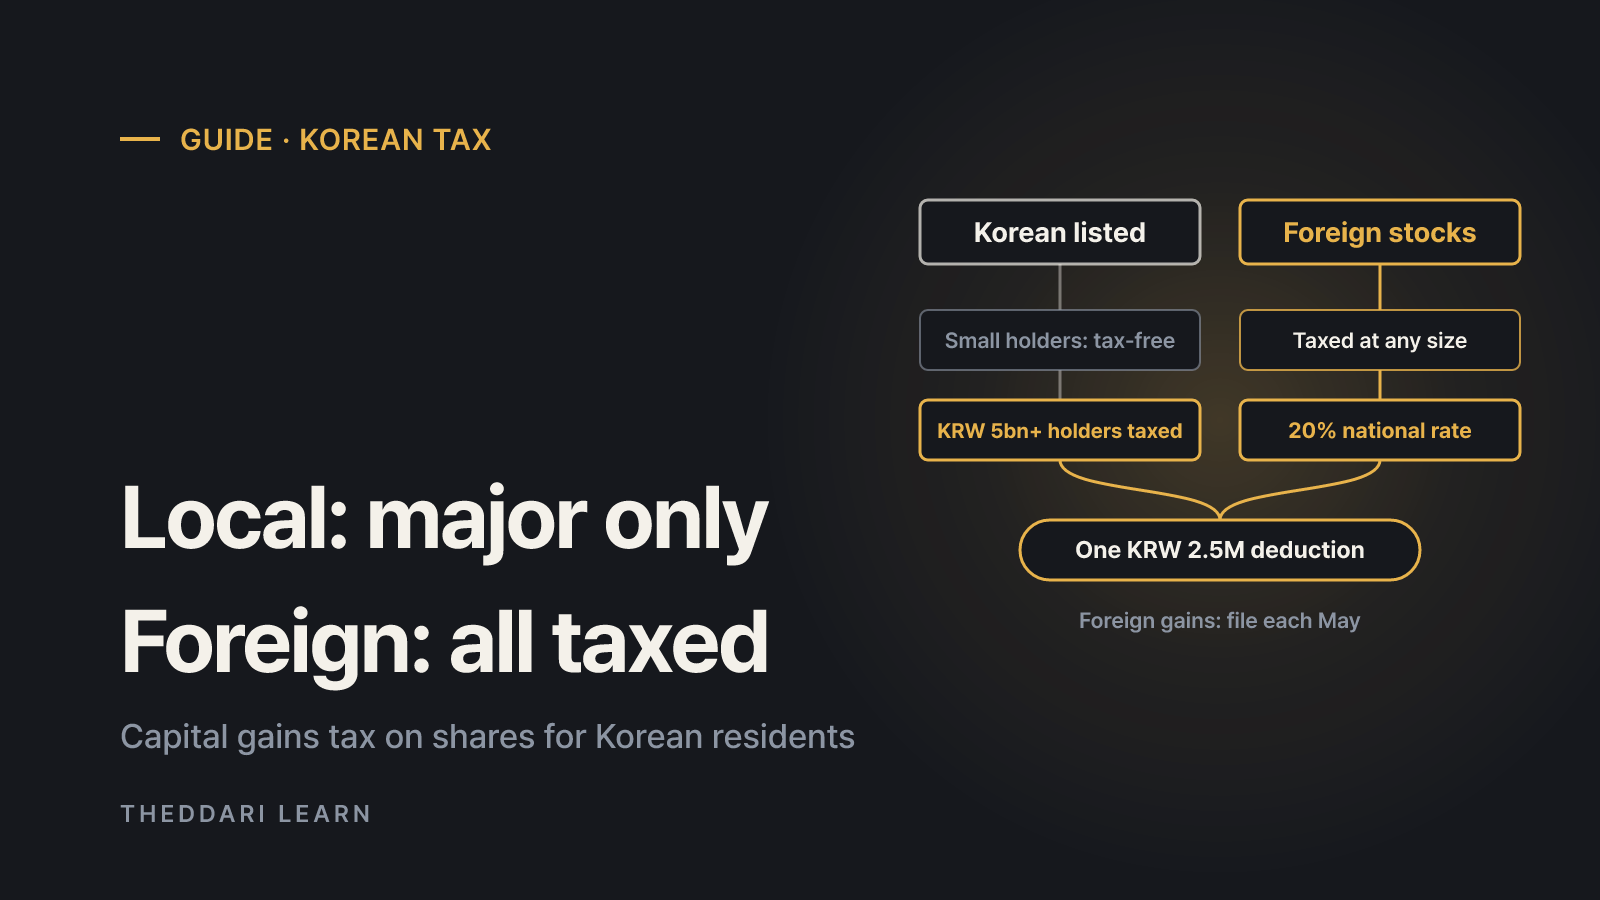
- A listed-company major shareholder holds KRW 5 billion of one stock, or 1% (KOSPI), 2% (KOSDAQ) or 4% (KONEX), measured at the prior year end with related parties.
- Gains on foreign-listed stocks such as US shares are taxable for residents of five or more years, whatever the account size, at a 20% national rate (10% for small-company shares).
- One KRW 2.5 million annual basic deduction covers taxable domestic and foreign share gains combined, and gains and losses in the same year can be netted.
- Foreign stock gains are reported once a year in May of the following year; failing to file triggers a 20% penalty on the unreported tax.
Capital gains tax in Korea treats domestic and foreign stocks very differently. As of October 2026, a Korean tax resident who sells listed Korean shares through the exchange as a small shareholder generally owes no capital gains tax, while the same person must report gains on US, Japanese or other foreign-listed stocks every year, no matter how small the account. This guide covers individual Korean tax residents only and is based on the National Tax Service (NTS) guidance on share capital gains and its May 2026 filing notice. It does not describe the rules for non-residents, companies or other countries, and your own position can differ, so confirm details on Hometax or with a tax adviser before filing.
Who pays capital gains tax in Korea on shares
The NTS splits shares into a few groups. Shares of companies listed on KOSPI, KOSDAQ or KONEX are taxable when a major shareholder sells them, even a single share. When a small shareholder sells listed shares through the securities market, the gain is not subject to capital gains tax. A small shareholder who transfers listed shares outside the market, for example in a private deal, can be taxed. Unlisted company shares are generally taxable for every shareholder, with an exception for small shareholders selling qualifying small and mid-sized company shares through K-OTC, Korea's over-the-counter platform.
Foreign shares follow a broader rule. A resident who has kept an address or residence in Korea for five or more consecutive years up to the sale date is taxed on gains from foreign shares. The NTS defines these as shares issued by foreign companies that are not listed on a Korean exchange, plus shares of Korean companies listed on an overseas exchange, including depositary receipts. In its May 2026 press release the NTS stressed that while only major shareholders and unlisted-share sellers must report Korean share gains, anyone with gains on foreign shares must file.
Listed Korean shares, small shareholder, on exchange
- Taxed?
- No capital gains tax
- How it is reported
- No return; transaction tax withheld on sale
Listed Korean shares, major shareholder
- Taxed?
- Yes, from the first share
- How it is reported
- Preliminary return plus annual return
Listed Korean shares, small shareholder, off exchange
- Taxed?
- Yes
- How it is reported
- Preliminary return plus annual return
Unlisted shares (K-OTC small-company exception)
- Taxed?
- Generally yes
- How it is reported
- Preliminary return plus annual return
Foreign-listed shares, resident of 5+ years
- Taxed?
- Yes, any amount
- How it is reported
- Annual return in May only
The KRW 5 billion major shareholder test
Major shareholder status is measured at the end of the business year before the year of sale, and your holdings are combined with those of related parties such as certain family members. For sales from 1 January 2024, the NTS lists the thresholds as a 1% stake or KRW 5 billion in market value for KOSPI, 2% or KRW 5 billion for KOSDAQ, and 4% or KRW 5 billion for KONEX. For unlisted shares the test is 4% or KRW 1 billion. If you were below the line at the previous year end but buy enough during the year to cross the ownership percentage, you are treated as a major shareholder from that purchase date.
The money threshold was nearly tightened in 2025. The government's July 2025 tax reform plan proposed cutting it from KRW 5 billion to KRW 1 billion, but after investor pushback it announced on 15 September 2025 that the KRW 5 billion line would stay. Korean tax law is revised every year, so investors whose year-end holdings sit near the threshold should check the current rules annually.
Korea stock capital gains: rates, deduction and loss netting
The rates below come from the NTS overview attached to its May 2026 press release and are national income tax rates. For a major shareholder selling non-small-company shares held for at least one year, the first KRW 300 million of taxable gains is taxed at 20% and the excess at 25%. Holdings of less than one year are taxed at 30%. Small-company major shareholders face 20% to 25%. Small shareholders selling off-exchange or unlisted shares pay 10% for small-company shares and 20% otherwise. Foreign shares are generally taxed at 20%, or 10% for qualifying small-company shares.
You will often see 22% quoted for foreign stock gains. That figure is the 20% national rate plus local income tax, which is reported alongside the national return. When estimating what you will actually pay, include the local tax step shown in the Hometax filing flow.
Who is taxed
- Taxable Korean shares
- Major shareholders, off-exchange sales, unlisted shares
- Foreign shares
- All residents of 5+ years with gains
National rate
- Taxable Korean shares
- 10%, 20%, 20-25% or 30% depending on status, company size and holding period
- Foreign shares
- 20% (10% for qualifying small-company shares)
Basic deduction
- Taxable Korean shares
- KRW 2.5 million per year, shared with foreign shares
- Foreign shares
- KRW 2.5 million per year, shared with Korean shares
Loss netting
- Taxable Korean shares
- With foreign shares in the same year, on the annual return
- Foreign shares
- With taxable Korean shares in the same year
Filing
- Taxable Korean shares
- Preliminary and annual returns
- Foreign shares
- No preliminary return; annual return the next May
One deduction, one year, and the exchange rate
Since sales on or after 1 January 2020, gains and losses on taxable Korean shares and foreign shares can be combined, and the basic deduction was changed from KRW 2.5 million for each category to KRW 2.5 million in total. In the NTS example, a KRW 4 million loss on unlisted Korean shares and a KRW 3 million gain on foreign shares produce a net loss, so no tax is due. Losses from tax-free exchange sales of listed Korean shares do not count. Losses can be netted within the same year but cannot be carried forward.
Because foreign share prices and costs are converted into won, currency moves can create a taxable gain even when a position is flat or down in dollars. The NTS also notes that if you sell shares within one year of receiving them as a gift from a spouse or lineal relative, for gifts made on or after 1 January 2025 the gain is calculated using the donor's original cost. Scheduled US jobs, inflation and central bank releases often move the won-dollar rate; the theddari economic calendar lists those dates, although it cannot predict the direction of currencies or prices.

How to file Korean tax on US stocks
- 1
Collect a full year of trades
Gather every foreign share sale from January to December across all brokers, plus any taxable Korean share sales. Many Korean brokers issue a capital gains calculation statement; the NTS says submitting it lets you skip the detailed calculation schedule and expense evidence.
- 2
Net gains and losses, then deduct
Combine the year's gains and losses and subtract the KRW 2.5 million basic deduction once. Where income taxed at different rates is mixed, losses are applied first against income at the same rate, then spread across the rest.
- 3
File on Hometax in May
Foreign share gains need no preliminary return. For 2025 sales the deadline fell on 1 June 2026 because 31 May was a Sunday. Check the NTS notice in spring 2027 for the deadline covering 2026 sales.
- 4
Pay, or pay in instalments
Under the 2026 notice, if the tax due exceeded KRW 10 million, part of it could be paid by 3 August: the amount above KRW 10 million when the tax was up to KRW 20 million, or up to 50% when it was higher.
Taxable Korean share sales also require a preliminary return during the year. The NTS worked example shows a domestic major shareholder who filed a preliminary return and later claimed a partial refund on the annual return by netting a foreign share loss. According to the same release, about 220,000 people received May 2026 filing notices, and 182,000 of them were foreign share investors, the largest group. Not receiving a notice does not remove the obligation to file.
Penalties, exceptions and common mistakes
- Late or missing returns: not filing by the deadline adds a 20% penalty on the unreported tax, and unpaid tax accrues a late-payment charge of 0.022% per day.
- Year-end major shareholder status: because the test uses the previous year-end, holdings near KRW 5 billion should be checked together with related parties.
- Transaction tax still applies: tax-free on capital gains does not mean tax-free trading. Korean brokers withhold securities transaction tax on sales, and Korean press reported the rate returning to about 0.2% in 2026 after the planned financial investment income tax was scrapped.
- Temporary relief to verify: in March 2026 a National Assembly committee approved a special deduction of up to 100% of the capital gains tax on foreign shares sold through a Reinvestment Account (RIA), with the proceeds held in Korean stocks for at least one year, the rate stepping down by sale date. Confirm the final terms with your broker and the NTS before relying on it.
- ETFs are different: Korean-listed ETFs that track foreign markets and ETFs listed abroad can be taxed differently, so do not assume they follow the foreign share rules above.
Tax policy news often surfaces first in investor discussion. The theddari stock Telegram trends page shows which market and tax topics Korean investors are talking about; treat it as a lead, and confirm anything that affects your return against the NTS or Ministry of Economy and Finance originals.
常见问题
Do Korean residents pay tax on US stock gains?
Is selling Korean stocks on KOSPI tax-free?
Can losses on Korean stocks offset gains on US stocks?
Did Korea lower the major shareholder threshold to KRW 1 billion?
来源与参考资料
- 1National Tax Service: Capital gains tax on shares (Korean)(在新标签页中打开)www.nts.go.kr
- 2National Tax Service press release on 2025 capital gains tax filing, 4 May 2026 (Korean)(在新标签页中打开)www.nts.go.kr
- 3Dong-A Ilbo: Government keeps KRW 5 billion major shareholder threshold, 16 Sep 2025 (Korean)(在新标签页中打开)www.donga.com
- 4Seoul Shinmun: Committee passes tax relief for moving foreign stock money back to Korea, 17 Mar 2026 (Korean)(在新标签页中打开)www.seoul.co.kr
相关文章
 投资指南
Stock Market Circuit Breakers and Sidecars: US vs Korea
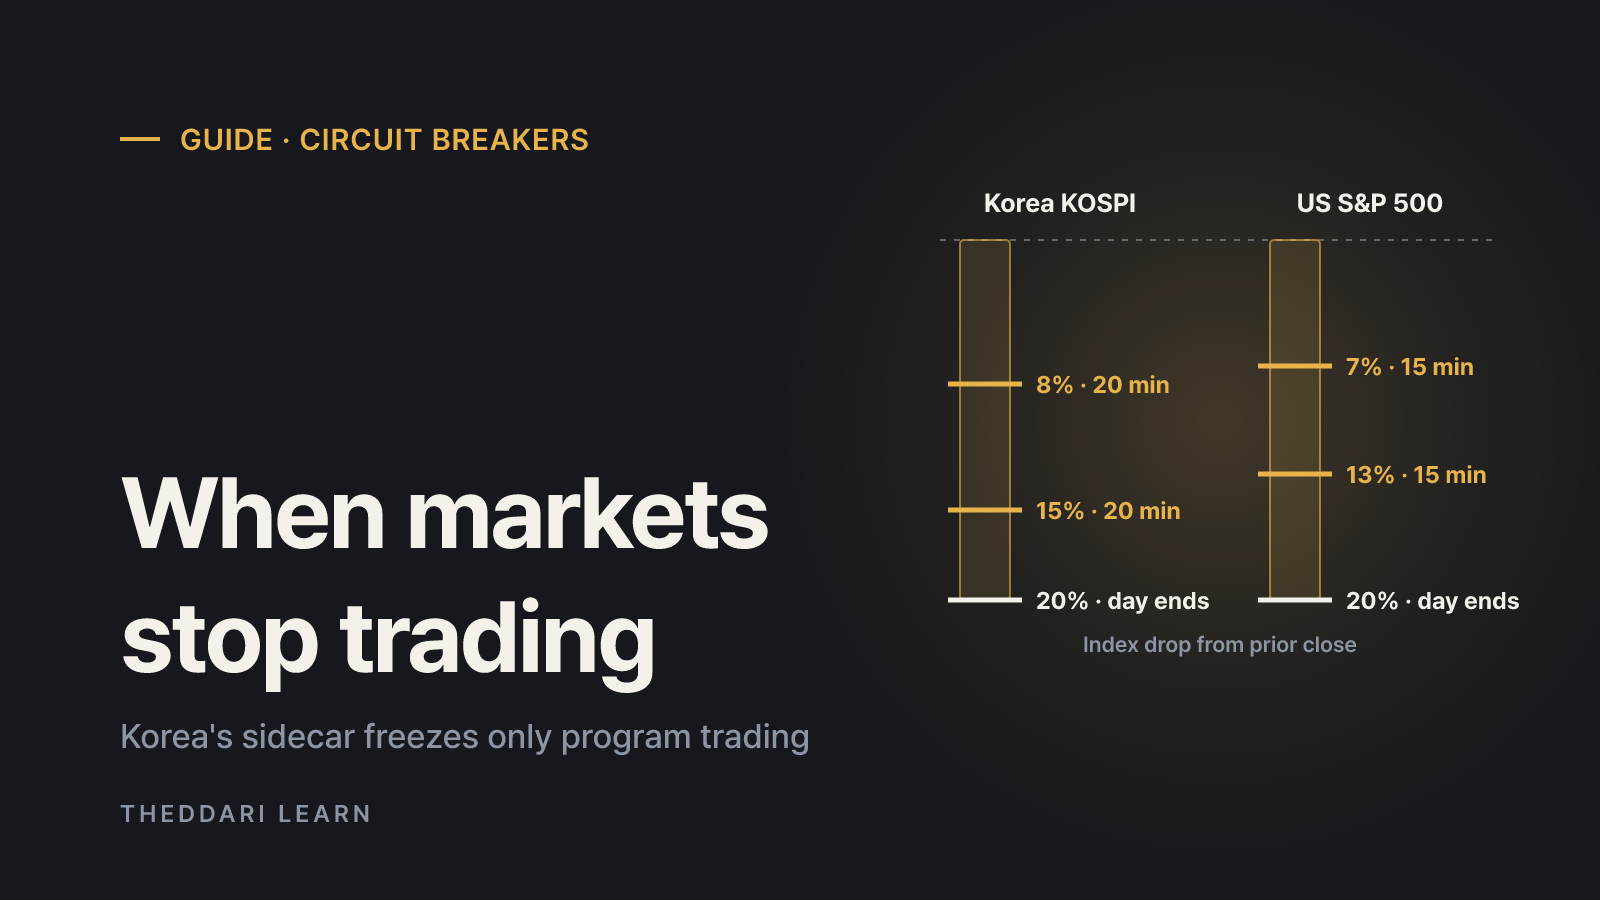
US market-wide circuit breakers halt all trading when the S&P 500 drops 7%, 13% or 20%. Korea uses 8%, 15% and 20% thresholds plus a sidecar that freezes only program trading. Here is how each rule works and what happens to your orders.
 投资指南
Pension Withdrawal Order in Korea: How IRP Money Is Taxed
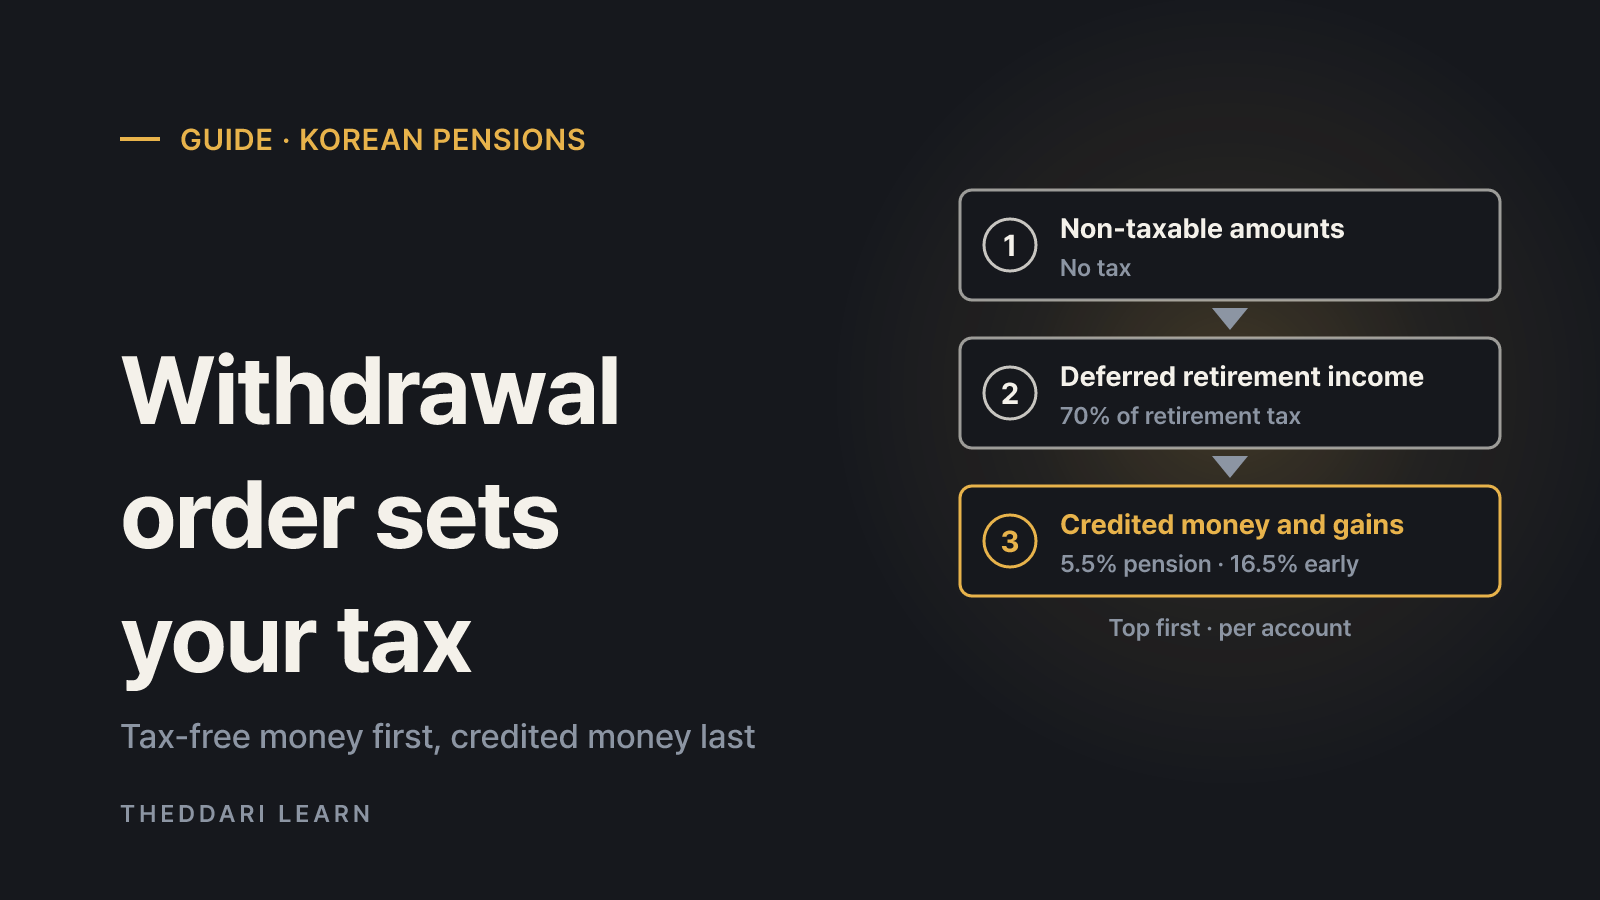
When you take part of the money out of a Korean pension savings account or IRP, the law decides which money left first, and each part is taxed differently. A November 2026 guide to the withdrawal order, rates and exceptions for Korean tax residents.
 投资指南
How to Buy ETFs in Singapore: CDP vs Custodian and Fees
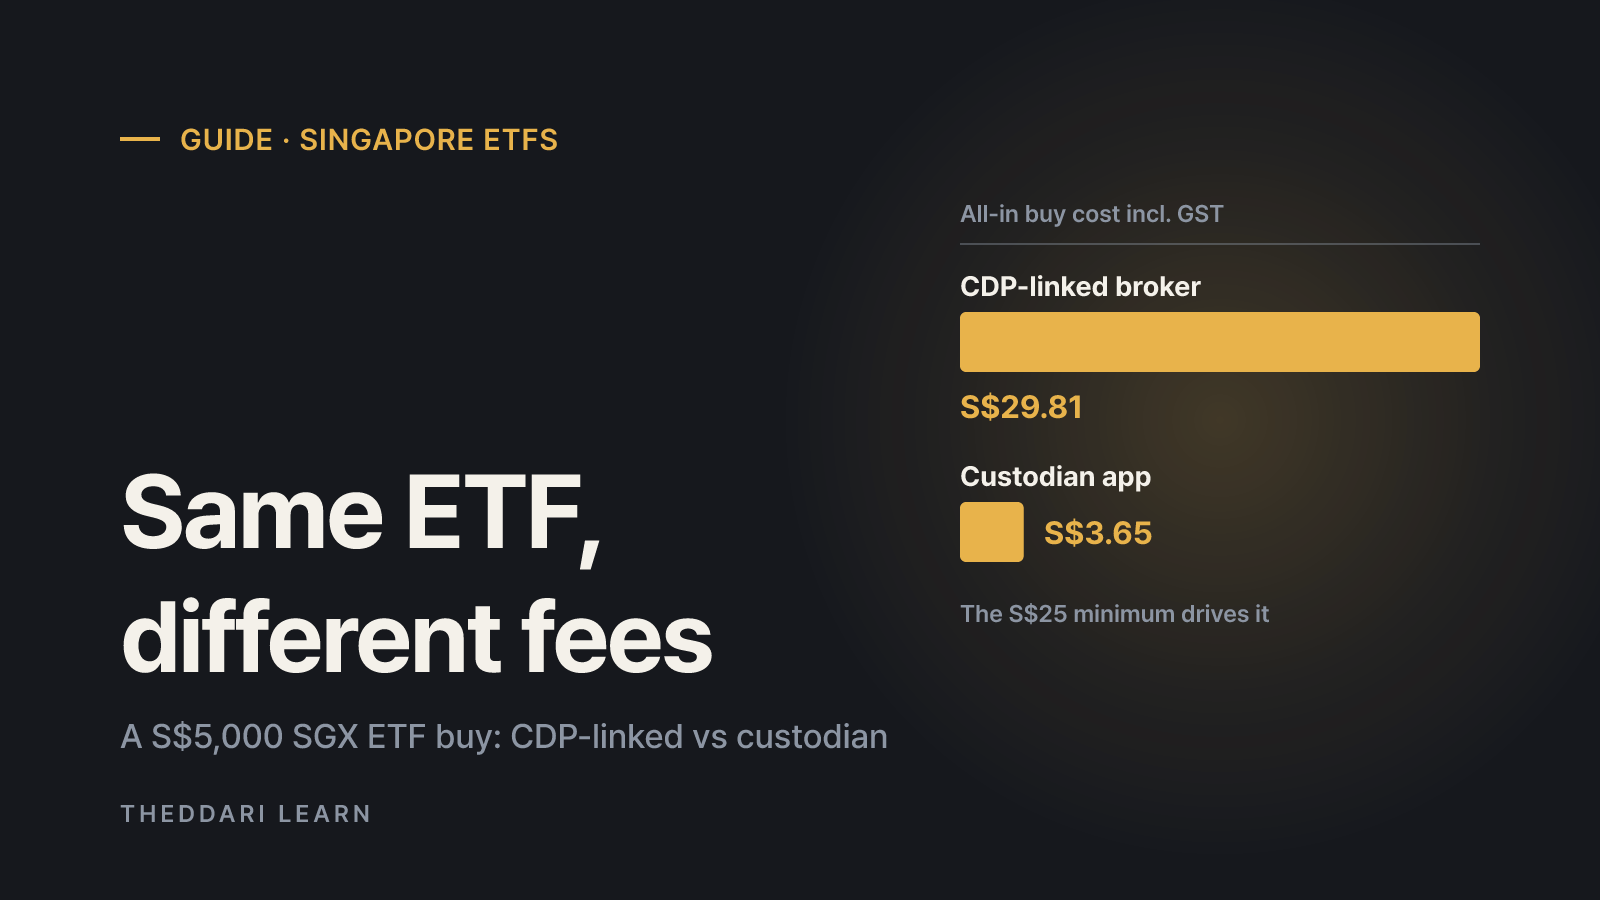
A practical guide for Singapore residents: how SGX-listed and US-listed ETFs are held, what the CDP rule changes of July 2026 mean for custodian accounts, and what a trade really costs at different order sizes.