What Is CXMT? What China's DRAM Maker Means for Micron and Memory Chip Stocks
CXMT is China's largest DRAM maker. Here is its 2026 IPO, its 10% DRAM share, the US 1260H listing, and what it means for Micron and memory chip stocks.
目录9 个章节
核心要点
- CXMT (ChangXin Memory Technologies) is China's largest DRAM maker, founded in 2016 in Hefei and listed on Shanghai's STAR Market on July 27, 2026.
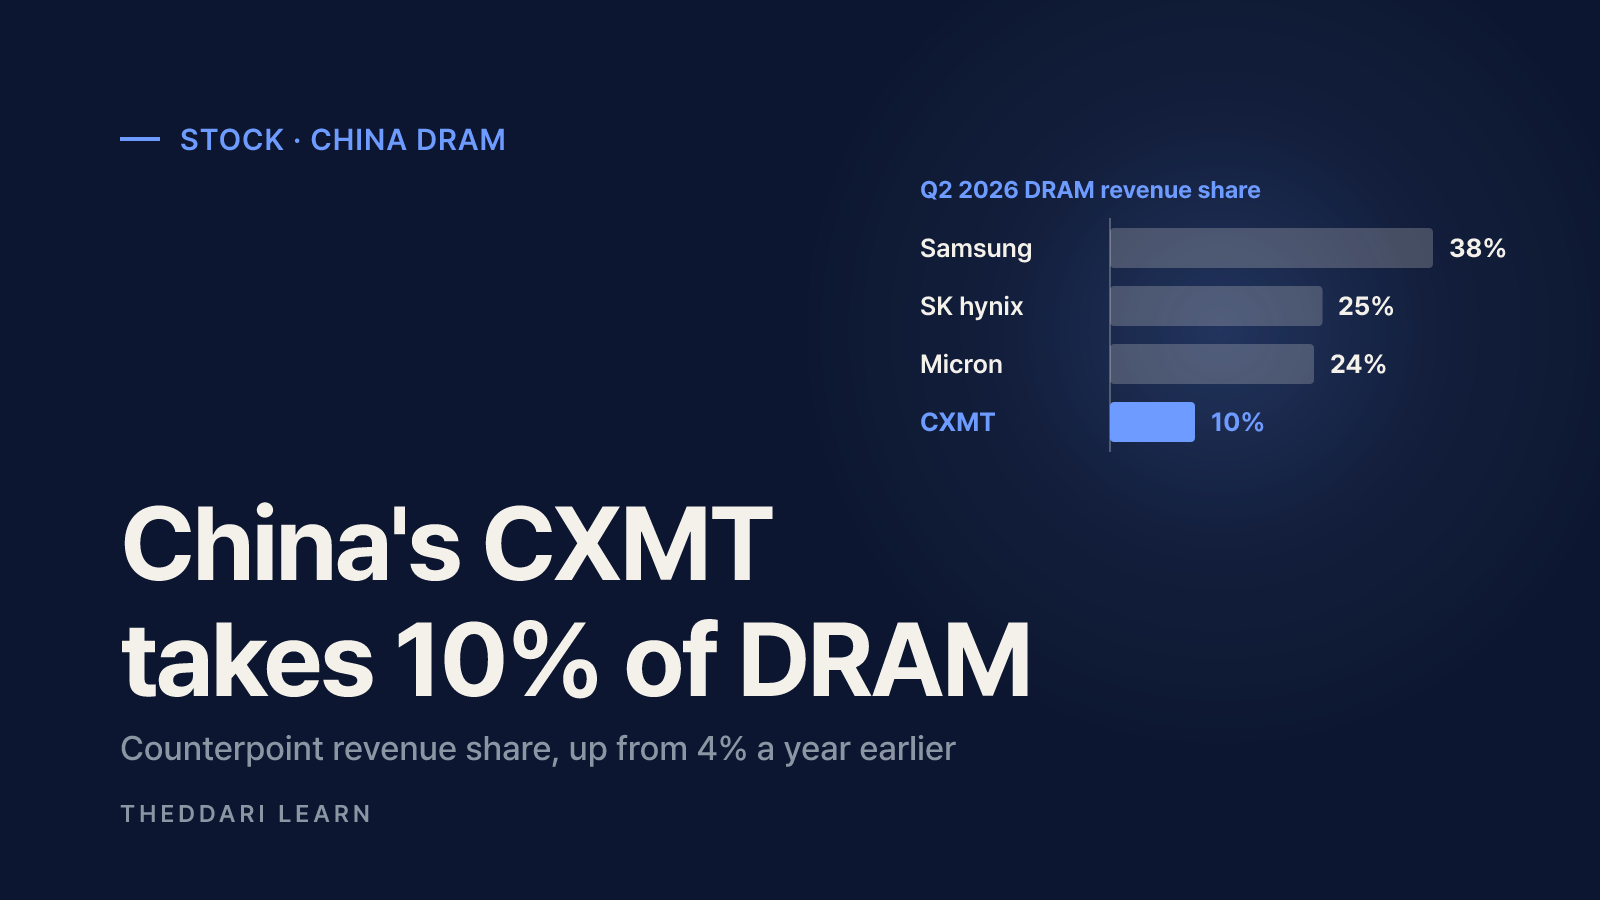
- Counterpoint Research put Q2 2026 DRAM revenue share at Samsung 38%, SK hynix 25%, Micron 24% and CXMT 10%, up from 4% a year earlier.
- CXMT competes mostly in commodity DRAM sold to Chinese customers; it still trails the big three in high-bandwidth memory (HBM) used in AI accelerators.
- The Pentagon kept CXMT on its Section 1260H Chinese military companies list in June 2026, and CXMT sued in August. The list is not a sanction or an export ban by itself.
CXMT (ChangXin Memory Technologies) is China's largest maker of DRAM, the short-term working memory inside phones, PCs and servers. Founded in 2016 in Hefei, it listed on Shanghai's STAR Market on July 27, 2026, and reached a 10% share of global DRAM revenue in the second quarter of 2026, according to Counterpoint Research data reported by Yahoo Finance. That is the first time a newcomer has broken into double digits in a market long split between Samsung, SK hynix and Micron.
For anyone following memory chip stocks, CXMT matters for two reasons: it adds commodity DRAM supply, and it sits at the center of US-China technology policy. This guide explains the business, how to read conflicting market-share numbers, and what CXMT's growth does and does not mean for Micron and its peers. All figures are as of October 2026.
What does CXMT make, and who buys it?
CXMT is an integrated DRAM manufacturer: it designs and produces its own chips. According to Chosun Biz, it grew with backing from the Chinese government and state funds, became the first mainland Chinese company to mass-produce a self-designed DDR4 chip in 2019, and has since added DDR5 and LPDDR5.
Its customers are overwhelmingly Chinese. The Korea Herald, citing the IPO prospectus, reported that overseas sales were just 2.79% of revenue and that the top five customers, including Alibaba Cloud, ByteDance, Xiaomi and Honor, generated about two-thirds of core revenue. Server DRAM rose from 8.39% of revenue in 2024 to 26.51% in 2025, a shift the paper linked to China's push to localize AI infrastructure.
Revenue and profit trend
Rising memory prices turned CXMT from a heavy loss-maker into a highly profitable company within two years. Figures below are in Chinese yuan as reported by Chosun Biz; the 2024 net result was not given in that report.
2023
- Revenue
- 9.1 billion yuan
- Net result
- Loss of 19.2 billion yuan
2024
- Revenue
- 24.2 billion yuan
- Net result
- Not reported
2025
- Revenue
- 61.8 billion yuan
- Net result
- Profit of 7.1 billion yuan
Q1 2026
- Revenue
- 50.8 billion yuan (up 719% year over year)
- Net result
- Profit of 33.0 billion yuan
CXMT's DRAM market share: why the numbers disagree
You will see CXMT described as holding 7%, 9% or 10% of the DRAM market. None of these is necessarily wrong. They come from different research firms, measure different things (revenue versus bit shipments) and cover different periods.
Counterpoint, revenue
- Period
- Q2 2026
- CXMT
- 10%
- Samsung
- 38%
- SK hynix
- 25%
- Micron
- 24%
TrendForce, revenue
- Period
- Q1 2026
- CXMT
- 7.6%
- Samsung
- 38%
- SK hynix
- 29%
- Micron
- 22%
Omdia, revenue
- Period
- CXMT Q4 2025; big three full-year 2025
- CXMT
- 7.67%
- Samsung
- 33.96%
- SK hynix
- 34.48%
- Micron
- 23.41%
Counterpoint, bit shipments
- Period
- Early 2026 estimate
- CXMT
- About 9%
- Samsung
- -
- SK hynix
- -
- Micron
- -
Two details matter for interpretation. First, CXMT's chips are estimated to sell for 5% to 10% less than comparable products from the big three, so revenue share and unit share can move differently. Second, Counterpoint projects CXMT's bit-shipment share at about 11% by 2028 and argues that 15% is the level a DRAM maker needs to fund leading-edge fabs over the long run. Its cautionary example is Taiwan's DRAM industry, which fell below that line in 2008 and shrank to roughly 3% of the market.
Why CXMT is back in the headlines
The July 2026 IPO priced at 8.66 yuan per share and raised about 57.9 billion yuan (roughly $8.6 billion), or up to 66.6 billion yuan with the over-allotment option. The shares rose about 466% on their first trading day. Valuation was debated from the start: Chosun Biz noted the offering price implied 308.92 times 2025 earnings, far above the industry average of 76.32 times.
Then, on October 12, 2026, the South China Morning Post reported that CXMT president Cao Kanyu claimed key progress on a 4F-squared memory cell design at an industry event in Shanghai, with a server memory product based on it planned by the end of 2026. In a 4F-squared layout each cell occupies four times the square of the minimum feature size, so more cells fit on a chip. Samsung and SK hynix are pursuing the same structure. Treat this as a company roadmap until yields and customer qualification are public.
What CXMT's rise means for memory chip stocks
Commodity DRAM supply
CXMT plans to lift monthly wafer capacity from about 320,000 to 420,000 by 2027. Most of that output is commodity DRAM such as DDR4, LPDDR4 and DDR5. In today's tight market CXMT benefits from high prices like everyone else, but in a downturn its extra supply could weigh on commodity pricing. A state-supported producer may also keep investing through a slump longer than a purely commercial rival would.
The HBM gap
High-bandwidth memory, the stacked DRAM that sits next to AI accelerators, is where the incumbents earn outsized profits. Per The Korea Herald, the big three had started HBM4 and were sampling HBM4E, while CXMT was developing HBM3 and targeting HBM3E mass production in 2027. Its overall technology gap is estimated at two to three years. Companies with a larger HBM mix are therefore less exposed to CXMT in the near term.
Micron versus SanDisk
Micron is the US company most directly comparable to CXMT because DRAM is a large part of its business. SanDisk sells NAND flash for storage, a different market. China's NAND challenger is YMTC; Yahoo Finance reported that its parent had a STAR Market application accepted to raise about 33 billion yuan. When Micron and SanDisk trend together, remember that the competitive threats in DRAM and NAND are separate.
The US policy angle: Section 1260H
In a June 10, 2026 Federal Register notice, the Department of Defense listed CXMT as a Chinese military company under Section 1260H, citing affiliations with China's Ministry of Industry and Information Technology and the State-owned Assets Supervision and Administration Commission. According to Trade Law Daily, the Pentagon had posted a notice removing CXMT in February 2026 but withdrew it the same day, and CXMT sued in federal court in Washington, DC on August 28.
Morrison Foerster explains that a 1260H designation does not by itself impose sanctions or ban commercial deals. Since June 30, 2026, though, the Pentagon cannot buy directly from listed companies, and a listed company faces a higher risk of being added to Treasury's NS-CMIC list, which generally bars US persons from trading its securities. Limited access to advanced lithography tools remains a separate long-term constraint.
A checklist for memory stock investors
- 1
Match the market-share basis
Before comparing numbers, confirm the research firm, whether it is revenue or bit shipments, and the quarter.
- 2
Read the earnings calls
In Micron, Samsung and SK hynix results, look for commodity DRAM pricing, China revenue exposure and HBM mix. Use the earnings calendar below to see report dates.
- 3
Track CXMT's delivery
Check whether the year-end 2026 server product, 2027 HBM3E production and the 420,000-wafer capacity target actually happen.
- 4
Watch Washington
The 1260H lawsuit, any NS-CMIC designation and changes to chip-equipment export controls can change CXMT's pace and its access to foreign customers and investors.

To see how traders are discussing memory names, browse the theddari stock Telegram trends. High chatter is not a price signal, so check the original reports and numbers yourself.
Risks and limits of this analysis
- Share and earnings figures vary by source and basis, and some reports used here are translations.
- CXMT's capacity and product timelines are company plans that depend on yields and customer qualification.
- Memory is a deeply cyclical industry; when today's shortage eases, prices can fall for CXMT and the big three alike.
- US and Chinese policy shifts can change CXMT's equipment supply, overseas sales and investor access quickly.
- CXMT is a mainland A-share, so trading hours, currency, access routes and disclosure practices differ from US-listed stocks.
常见问题
Can US investors buy CXMT stock?
Why do CXMT market share numbers differ between reports?
Is CXMT a threat to Micron's HBM business?
Does CXMT affect SanDisk?
来源与参考资料
- 1Yahoo Finance (Stocktwits): Micron, Samsung, SK Hynix Suffer Drop In DRAM Market Share As China's CXMT Pulls Ahead (Sept 3, 2026)(在新标签页中打开)finance.yahoo.com
- 2The Korea Herald: China's CXMT eyes memory's Big 3 with $8.5b IPO (July 19, 2026)(在新标签页中打开)www.koreaherald.com
- 3Chosun Biz: China's CXMT debuts with record IPO, challenges Samsung SK Micron in DRAM (July 22, 2026)(在新标签页中打开)biz.chosun.com
- 4South China Morning Post: China's CXMT unveils key progress on chip structure (Oct 12, 2026)(在新标签页中打开)www.scmp.com
- 5Federal Register: Notice of Availability of Designation of Chinese Military Companies (June 10, 2026)(在新标签页中打开)www.federalregister.gov
- 6Trade Law Daily: Chinese Chip Firm Joins Others in Challenging Pentagon's Chinese Military Company Label (Sept 1, 2026)(在新标签页中打开)tradelawdaily.com
- 7Morrison Foerster: DoD Expands the Section 1260H Chinese Military Companies List (June 26, 2026)(在新标签页中打开)www.mofo.com
相关文章
 股票
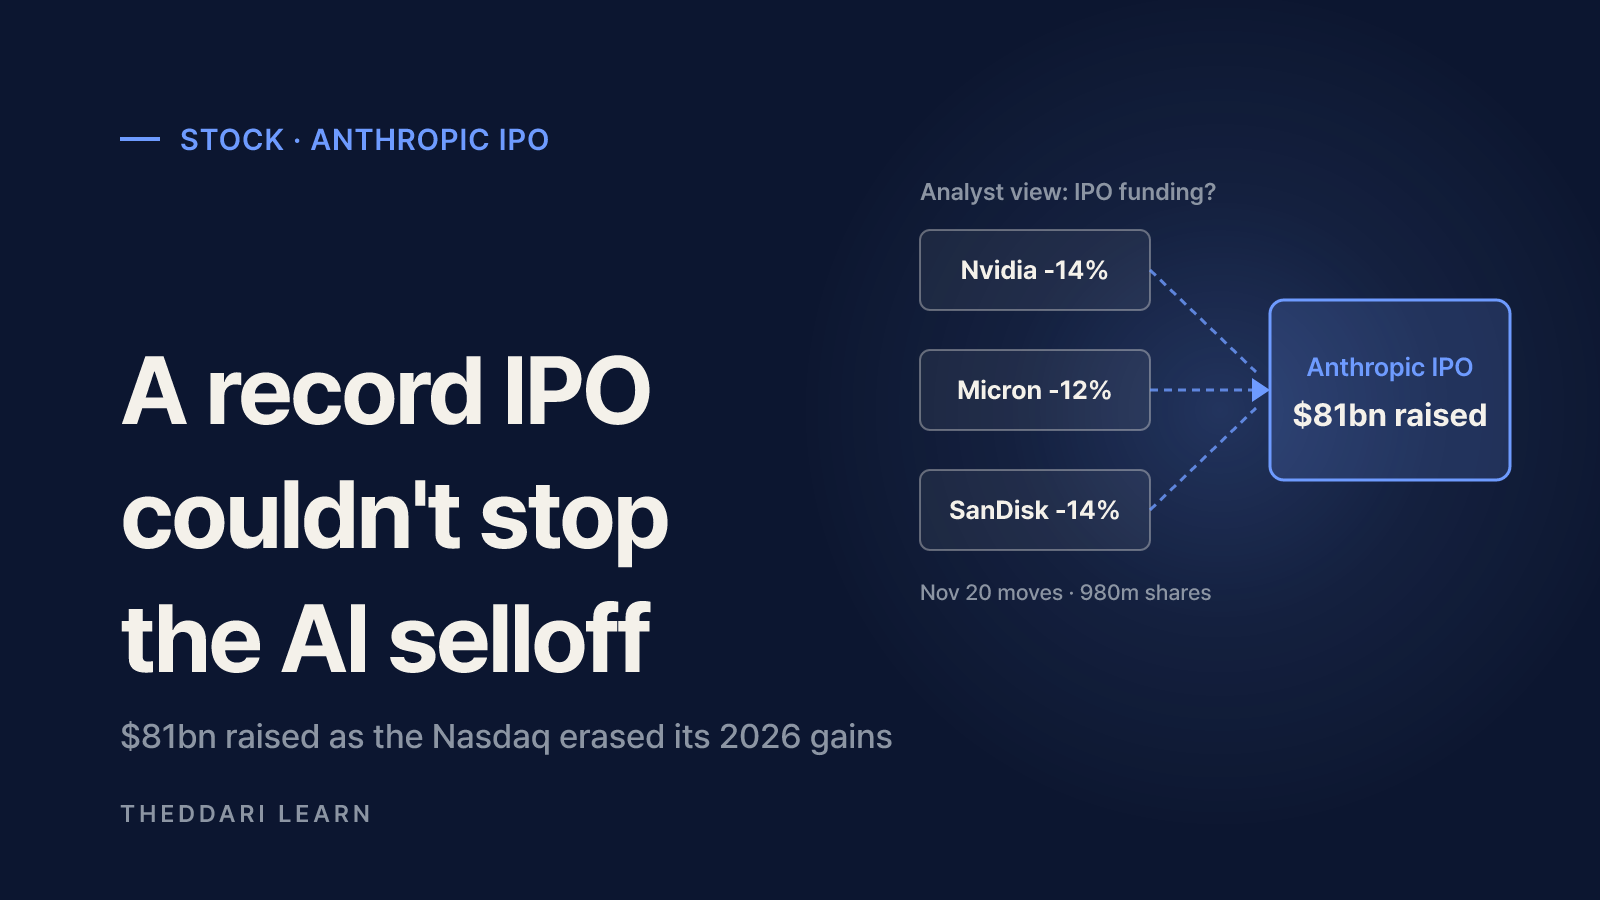
Why the Anthropic IPO Didn't Stop the AI Stock Selloff
Anthropic raised $81bn in the largest IPO on record, yet the Nasdaq wiped out its 2026 gains the next day. Here is how a blockbuster listing and an AI selloff can happen at once.
 股票
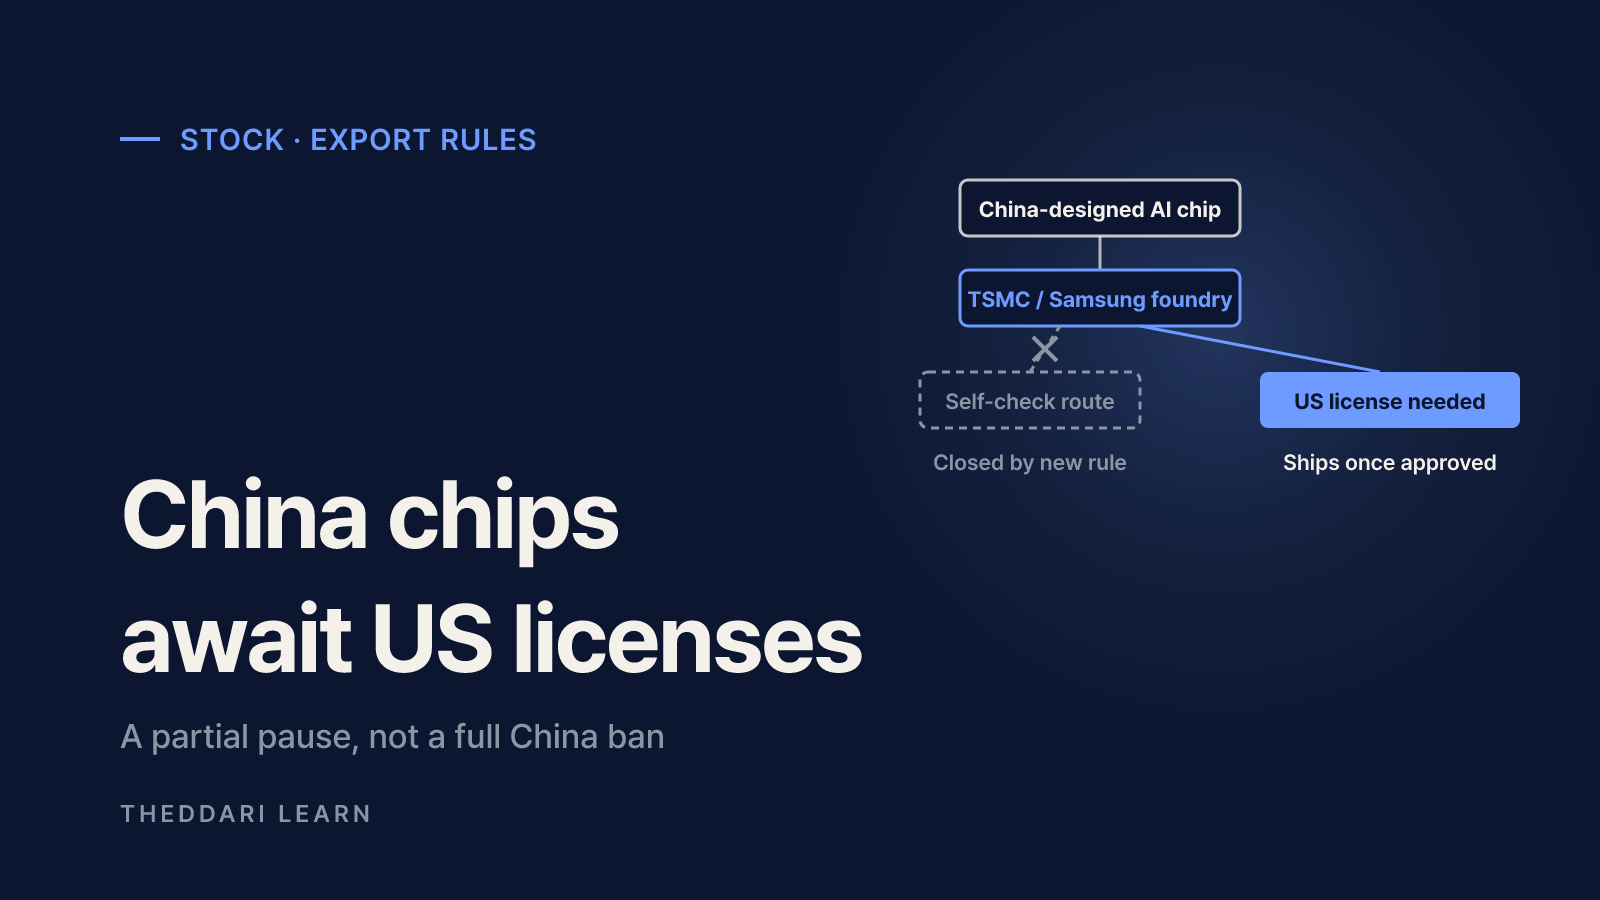
Chip Export Controls: Why TSMC, Samsung Paused China Chips
After the US Commerce Department's new chip export rule took effect on November 19, 2026, TSMC and Samsung reportedly paused some deliveries to Chinese customers. Here is what the rule actually changes, which parts are confirmed, and the numbers that matter for TSM and Samsung shareholders.
 股票
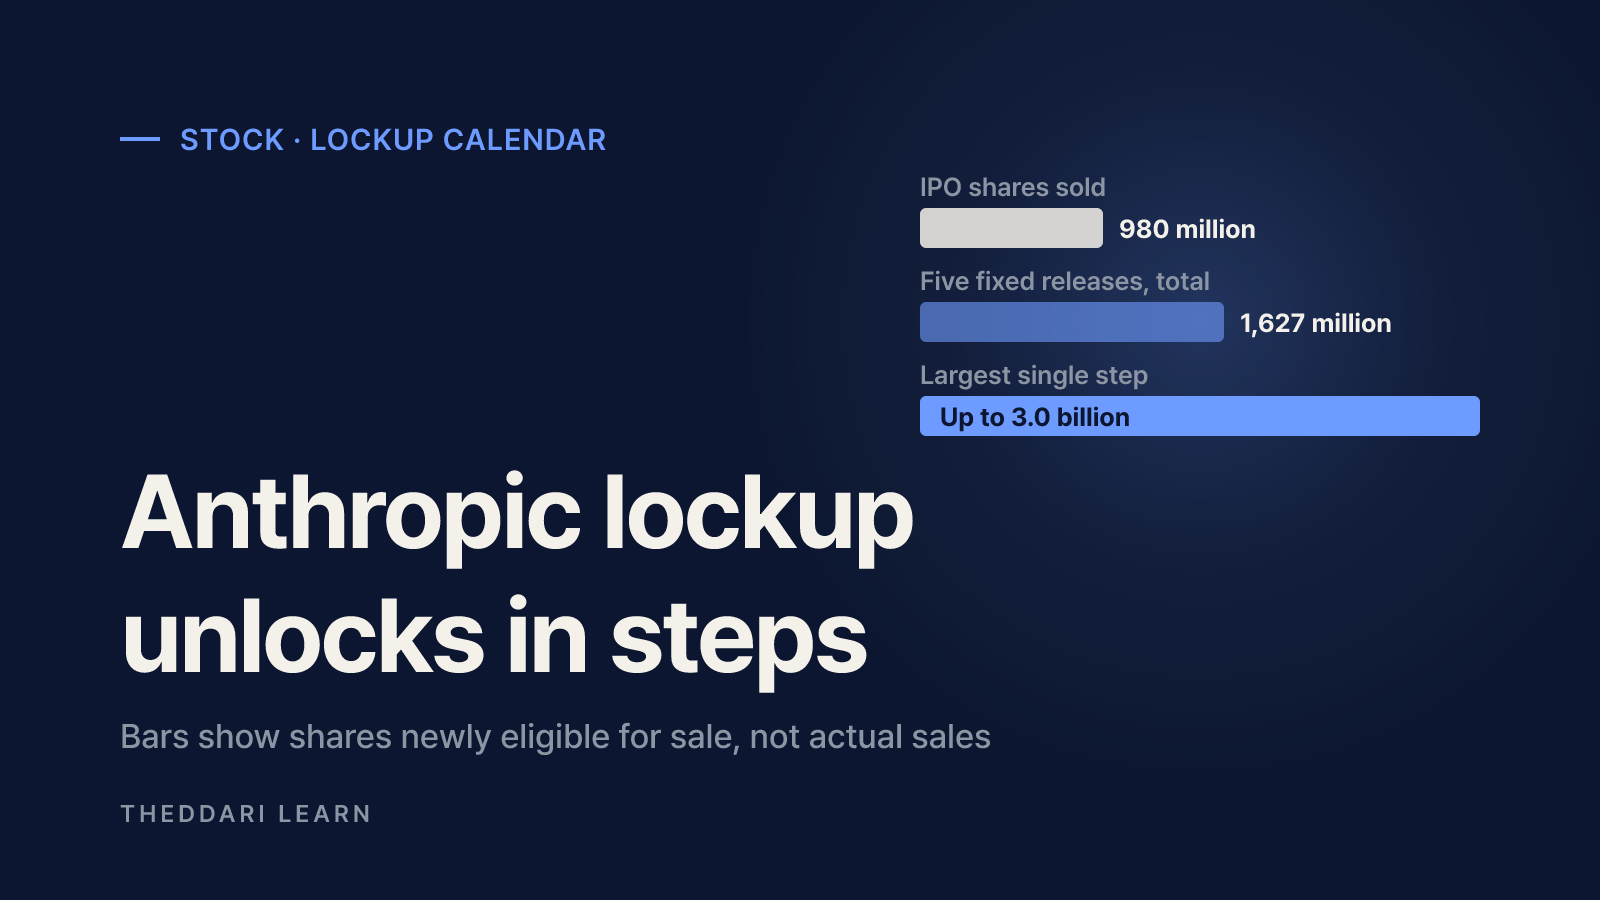
Anthropic IPO Lockup Expiration Dates and ANT Price Impact
There is no single Anthropic lockup expiration date. Insider shares unlock in 23 steps, some on fixed dates and the largest ones tied to earnings. Here is the calendar, where to verify it, and how to think about price impact.