Bond ETF Losses Explained: Interest Rates, Duration and How Bond ETF Returns Work
Bond ETF losses explained: why rising rates cut bond ETF prices, how to use duration to estimate the hit, and how Treasury ETFs differ from holding bonds.
目录9 个章节
核心要点
- Most bond ETF losses come from rising interest rates: when market yields go up, the prices of existing fixed-rate bonds go down, and so does the fund's NAV.
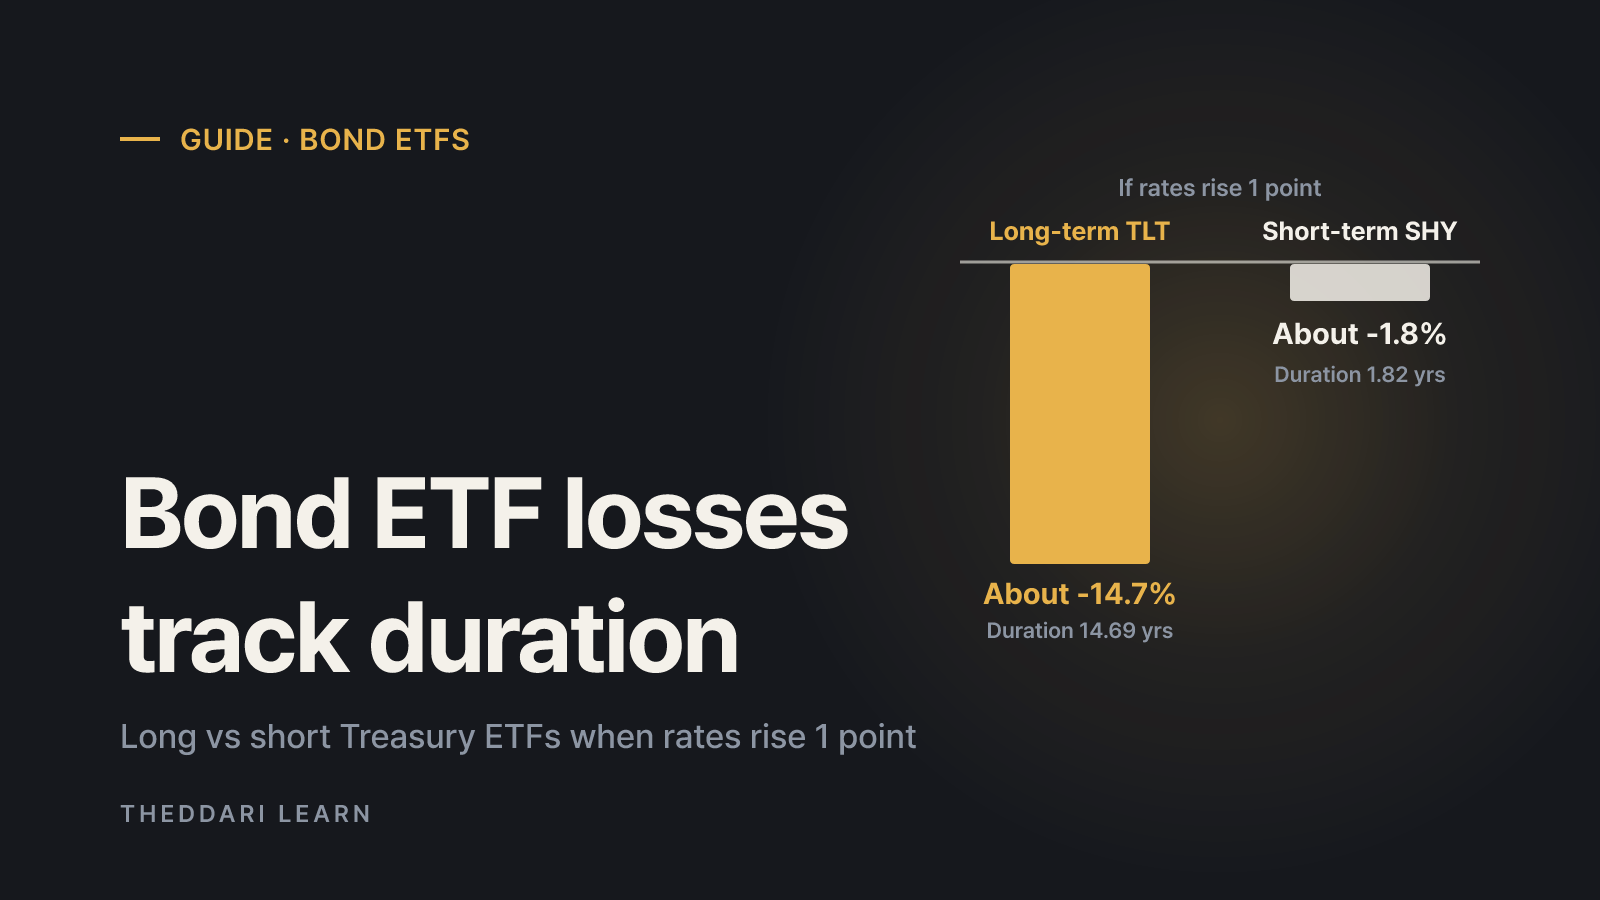
- Duration estimates the hit. A fund with an effective duration of 14.69 years would be expected to lose roughly 14.7% if rates rose 1 percentage point.
- A typical bond ETF never matures, so there is no fixed date when it returns to its starting price.
- Total return is price change plus distributions. Income cushions small rate increases but not large ones.
- Credit risk, currency exposure and leverage add risks on top of duration.
Bond ETF losses usually come down to one thing: interest rates went up. When market yields rise, the prices of bonds already issued at lower fixed rates fall, and a bond ETF holding those bonds sees its net asset value (NAV) drop. How far it drops depends on the fund's duration, its sensitivity to rate changes. This guide uses FINRA's investor education material and iShares fund data as of October 2026 to explain how bond ETF returns work and why a fund full of U.S. Treasuries can still post double-digit losses.
The phrase 'bonds are safe' mixes up two different risks. Treasuries carry very little default risk, but they carry plenty of price risk if you might sell before maturity. A bond ETF is, in effect, always selling before maturity, because its price is set by the market value of its holdings every trading day.
Why rising rates cause bond ETF losses
FINRA's example makes the mechanism clear. Say you pay $1,000 for a 10-year bond with a 6% coupon. A year later, rates have risen and comparable new bonds pay 7%. No buyer will pay full price for your 6% bond when 7% is available, so to sell it you have to accept a discount large enough that the buyer earns roughly 7%. If rates had fallen instead, you could sell above face value.
A bond ETF holds dozens or hundreds of such bonds. When yields rise across the market, all of those bonds reprice lower at once, and the ETF's NAV follows. Government backing does not change this: it covers scheduled interest and repayment at maturity, not the price someone will pay you next Tuesday.
Rates rise
- Existing bond prices
- Fall
- Bond ETF NAV
- Falls
- Yield on new bonds the fund buys
- Higher
Rates fall
- Existing bond prices
- Rise
- Bond ETF NAV
- Rises
- Yield on new bonds the fund buys
- Lower
Rates flat
- Existing bond prices
- Drift toward face value
- Bond ETF NAV
- Grows mostly by income
- Yield on new bonds the fund buys
- Similar
Bond duration: the number that sizes the loss
Duration measures how much a bond's price is likely to change when rates move. FINRA's rule of thumb: for every 1 percentage point change in rates, price moves roughly the duration number in percent, in the opposite direction. A duration of 10 implies about a 10% drop if rates rise 1 point and about a 10% gain if they fall 1 point. Longer maturities and lower coupons generally mean longer duration.
Real fund data shows how wide the range is. As of October 9, 2026, the iShares 20+ Year Treasury Bond ETF (TLT) reported an effective duration of 14.69 years and a weighted average maturity of 26.07 years. The iShares 1-3 Year Treasury Bond ETF (SHY) reported 1.82 years. Both hold only Treasuries, yet the long fund is about eight times as rate-sensitive.
Maturity range held
- Long-term treasury ETF (TLT)
- 20+ years
- Short-term treasury ETF (SHY)
- 1-3 years
Effective duration
- Long-term treasury ETF (TLT)
- 14.69 years
- Short-term treasury ETF (SHY)
- 1.82 years
Estimated price change if rates rise 1 point
- Long-term treasury ETF (TLT)
- About -14.7%
- Short-term treasury ETF (SHY)
- About -1.8%
30-day SEC yield
- Long-term treasury ETF (TLT)
- 5.54%
- Short-term treasury ETF (SHY)
- 4.65%
2022 NAV total return
- Long-term treasury ETF (TLT)
- -31.41%
- Short-term treasury ETF (SHY)
- -3.90%
YTD NAV total return to Oct 12, 2026
- Long-term treasury ETF (TLT)
- -7.42%
- Short-term treasury ETF (SHY)
- +0.64%
Expense ratio
- Long-term treasury ETF (TLT)
- 0.15%
- Short-term treasury ETF (SHY)
- 0.15%
The estimate row is a straight-line approximation: duration times the rate change. For large moves, convexity matters. TLT lists convexity of 3.07 versus 0.05 for SHY, which means TLT's actual losses on a big rate spike would be slightly smaller, and its gains on a big rate drop slightly larger, than the simple estimate.
Find a fund's duration on its fact sheet or product page, usually under Key Facts, Portfolio Characteristics or Bond Holding Statistics.
How bond ETF total return works: price plus income
A bond ETF's total return has two parts: the change in NAV from bond prices, and the distributions paid from interest income. Investor.gov explains that funds pass most of their income, less expenses, to shareholders, and that NAV rises or falls with the market value of the portfolio. Fees come out of NAV, so you pay them indirectly.
How much rate rise can income absorb?
A rough one-year break-even is yield divided by duration. For TLT that is 5.54% / 14.69, about 0.38 percentage points. For SHY it is 4.65% / 1.82, about 2.55 points. In other words, a long-term Treasury ETF's yearly income can be wiped out by a fairly small rise in long-term yields, while a short-term fund can absorb a much larger move. This assumes a single, immediate rate change and a constant yield for the year, so treat it as a sense of scale, not a forecast.
A steady monthly payout is not principal protection
Monthly distributions can make a long bond fund feel stable. Yet TLT's five-year cumulative NAV total return to September 30, 2026 was -35.65%, a figure that already assumes every distribution was reinvested. Income helped, but price declines were larger.
Holding individual bonds vs owning a bond ETF
FINRA notes that a buy-and-hold-to-maturity investor may see little direct impact from rate swings: if you never sell, interim prices matter less, and you collect the promised coupons and face value unless the issuer defaults. Most bond ETFs do not work that way.
Maturity
- Individual bond held to maturity
- Fixed date, face value repaid
- Typical bond ETF
- None; holdings roll per index rules
Price swings
- Individual bond held to maturity
- Unrealized unless you sell
- Typical bond ETF
- Reflected in NAV and market price daily
Income after rates rise
- Individual bond held to maturity
- Coupon stays fixed
- Typical bond ETF
- Rises gradually as new bonds are added
Path back from a loss
- Individual bond held to maturity
- Maturity
- Typical bond ETF
- Depends on rates, income and duration
Diversification
- Individual bond held to maturity
- One issuer per bond
- Typical bond ETF
- Many holdings
Defined-maturity bond ETFs, which hold bonds maturing in a single year and then liquidate, are designed to behave more like a bond held to maturity. If that feature matters to you, confirm it in the prospectus rather than assuming any fund with 'Treasury' in its name works that way.
Other risks beyond duration
- Credit risk: corporate and high-yield bond ETFs can fall when defaults rise or credit spreads widen. FINRA stresses that a low duration does not mean low risk.
- Yield curve shifts: short and long rates do not always move together, so a Fed cut may not lift long-term bond funds.
- Currency: if you buy a bond ETF denominated in another currency, exchange-rate moves add to or subtract from your return; hedged versions carry hedging costs.
- Leverage: 2x and 3x long-bond funds target daily multiples, and multi-day results can differ sharply from the multiple of the index.
- Taxes: distribution and capital gains treatment depends on your country and account type, so check your local rules.
A checklist before you choose a bond fund
- Decide when you will need the money; the closer that date, the less duration you can tolerate.
- Look up effective duration and multiply by a 1- or 2-point rate rise to see the potential drawdown.
- Check credit quality: Treasuries, investment-grade corporates or high yield.
- Note rate-moving events such as CPI releases, jobs reports and FOMC meetings on the economic calendar. It tells you when volatility may spike, not which way rates will go.
- Compare expense ratio, bid/ask spread, currency exposure and tax treatment.

To see which rate and bond topics investor channels are discussing, browse stock Telegram trends. Mention volume reflects attention, not direction.
Bottom line
A long-term Treasury ETF that drops sharply when rates climb is usually working as designed. Duration cuts both ways: big gains when yields fall, big losses when they rise. Before buying any bond ETF, the more useful question is not whether its bonds are safe from default, but what its duration is and how much your balance would move if rates shifted by one percentage point.
常见问题
Can you lose money in a Treasury bond ETF?
Will my bond ETF recover if I just wait?
What is a good duration for a bond ETF?
Why did my bond ETF fall when the Fed cut rates?
来源与参考资料
- 1FINRA — Brush Up on Bonds: Interest Rate Changes and Duration(在新标签页中打开)www.finra.org
- 2iShares 20+ Year Treasury Bond ETF (TLT) fund page(在新标签页中打开)www.ishares.com
- 3iShares 1-3 Year Treasury Bond ETF (SHY) fund page(在新标签页中打开)www.ishares.com
- 4Investor.gov — Mutual Funds(在新标签页中打开)www.investor.gov
相关文章
 投资指南
Stock Market Circuit Breakers and Sidecars: US vs Korea
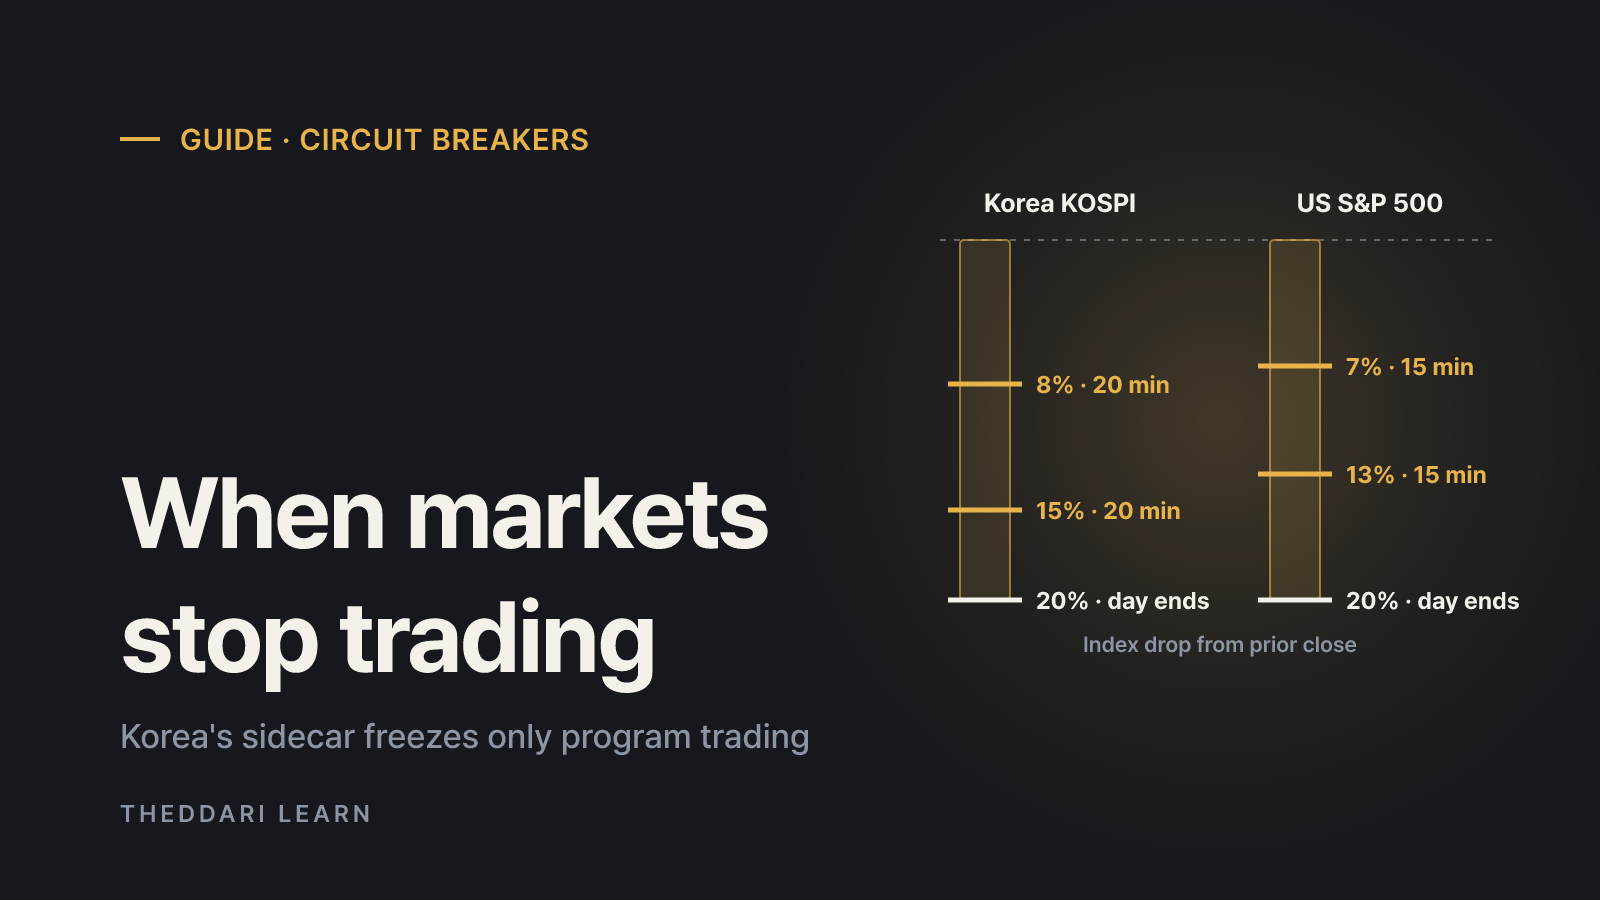
US market-wide circuit breakers halt all trading when the S&P 500 drops 7%, 13% or 20%. Korea uses 8%, 15% and 20% thresholds plus a sidecar that freezes only program trading. Here is how each rule works and what happens to your orders.
 投资指南
Pension Withdrawal Order in Korea: How IRP Money Is Taxed
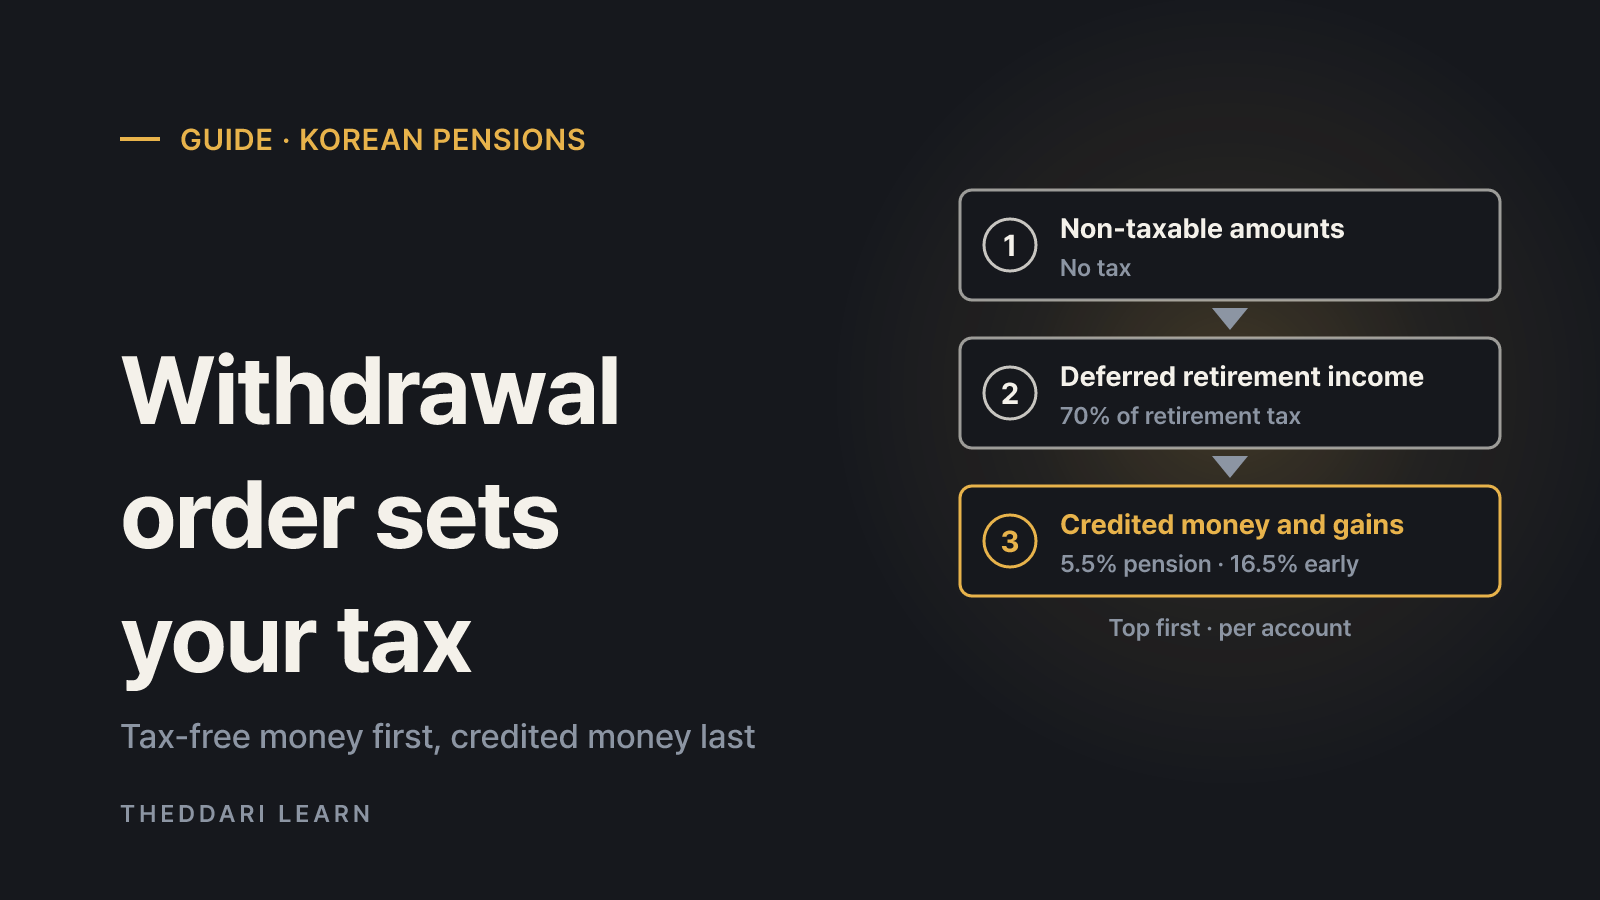
When you take part of the money out of a Korean pension savings account or IRP, the law decides which money left first, and each part is taxed differently. A November 2026 guide to the withdrawal order, rates and exceptions for Korean tax residents.
 投资指南
How to Buy ETFs in Singapore: CDP vs Custodian and Fees
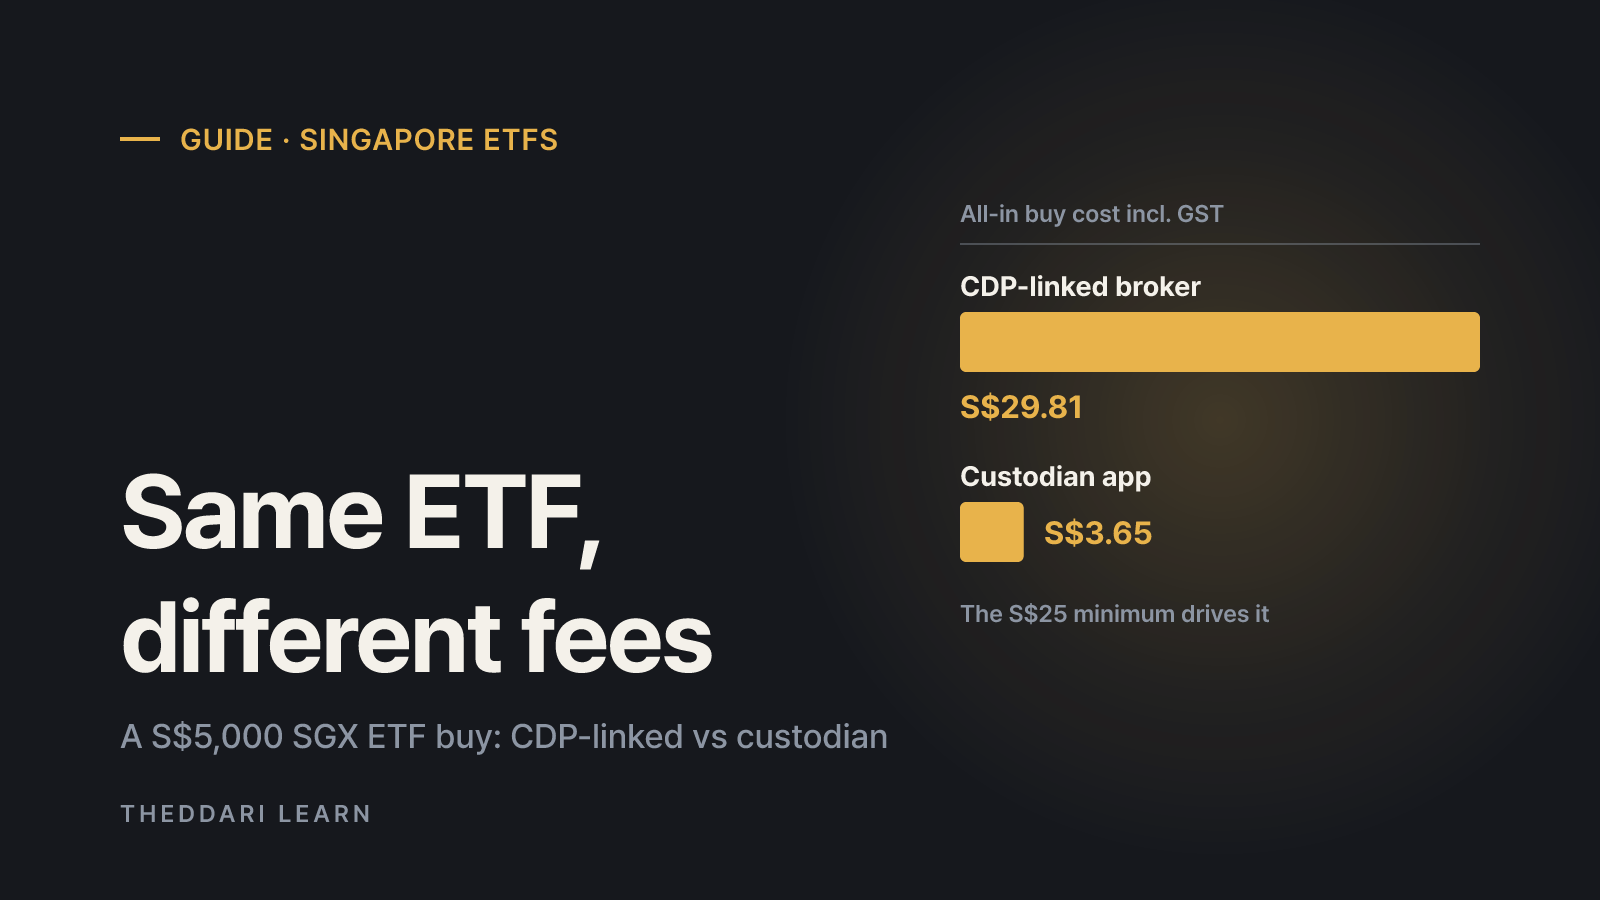
A practical guide for Singapore residents: how SGX-listed and US-listed ETFs are held, what the CDP rule changes of July 2026 mean for custodian accounts, and what a trade really costs at different order sizes.