ラウンジ›インサイト
コンセプト解説
暗号資産・株式・AI の重要な概念と最新の話題をわかりやすく解説
検索結果
28件更新日が新しい順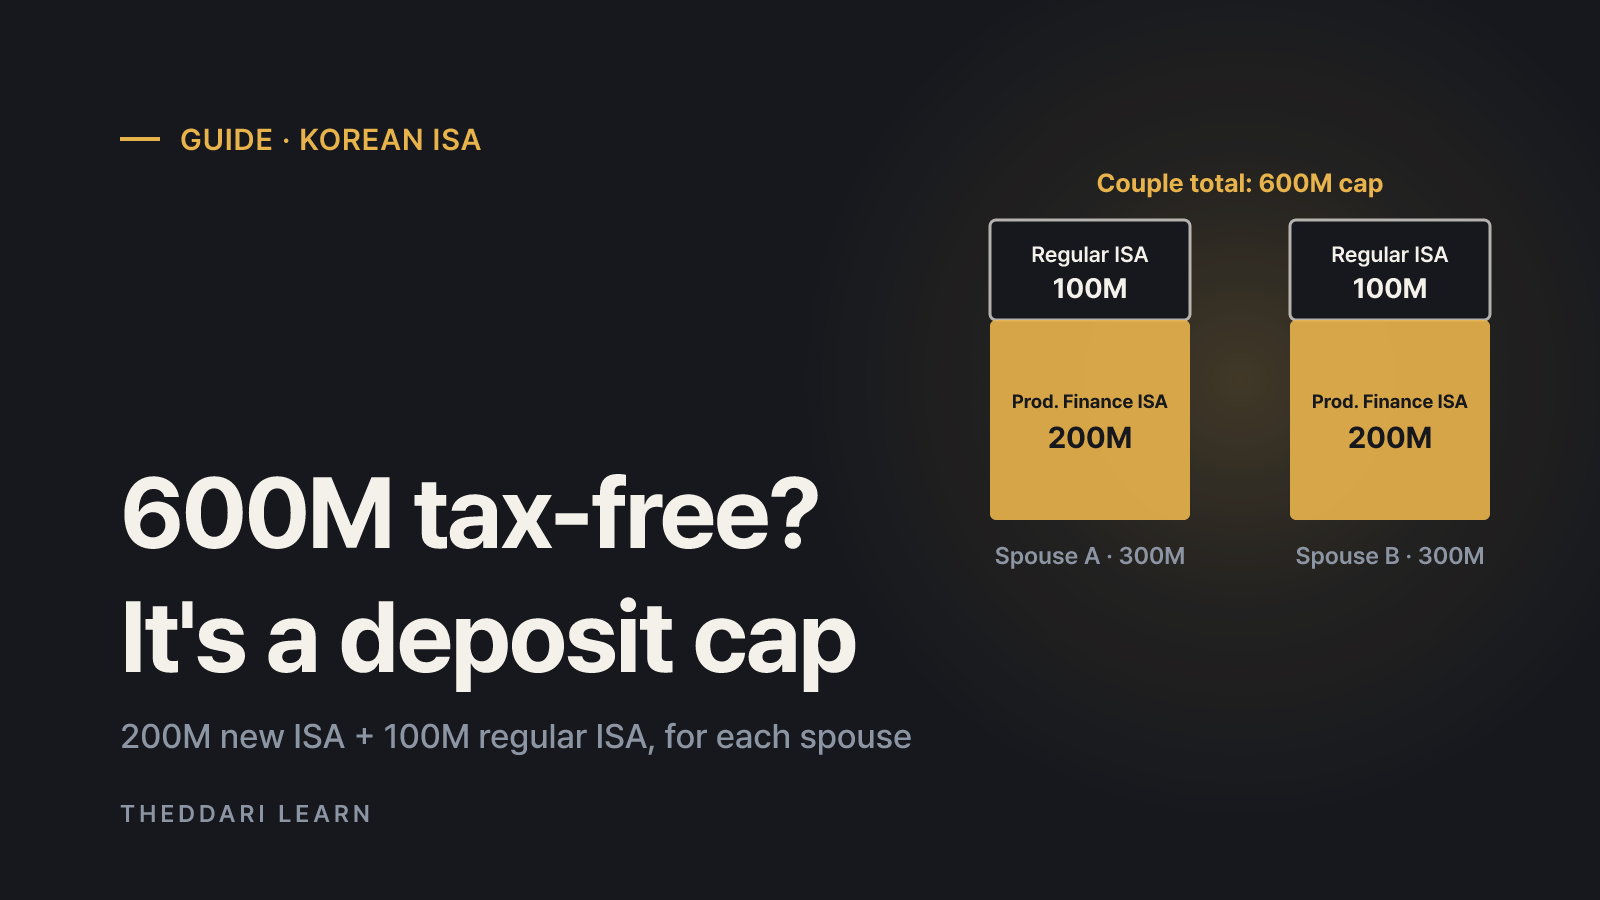 投資ガイド · 最新
Korea Productive Finance ISA: Is the 600M Won Claim Real?
Videos promoting a 'tax-free account for couples up to 600 million won' point to Korea's proposed Productive Finance ISA. The 600M figure is two people's combined contribution caps, not a tax-free amount, and the bill was still before the National Assembly as of November 1, 2026.
6分閲覧 3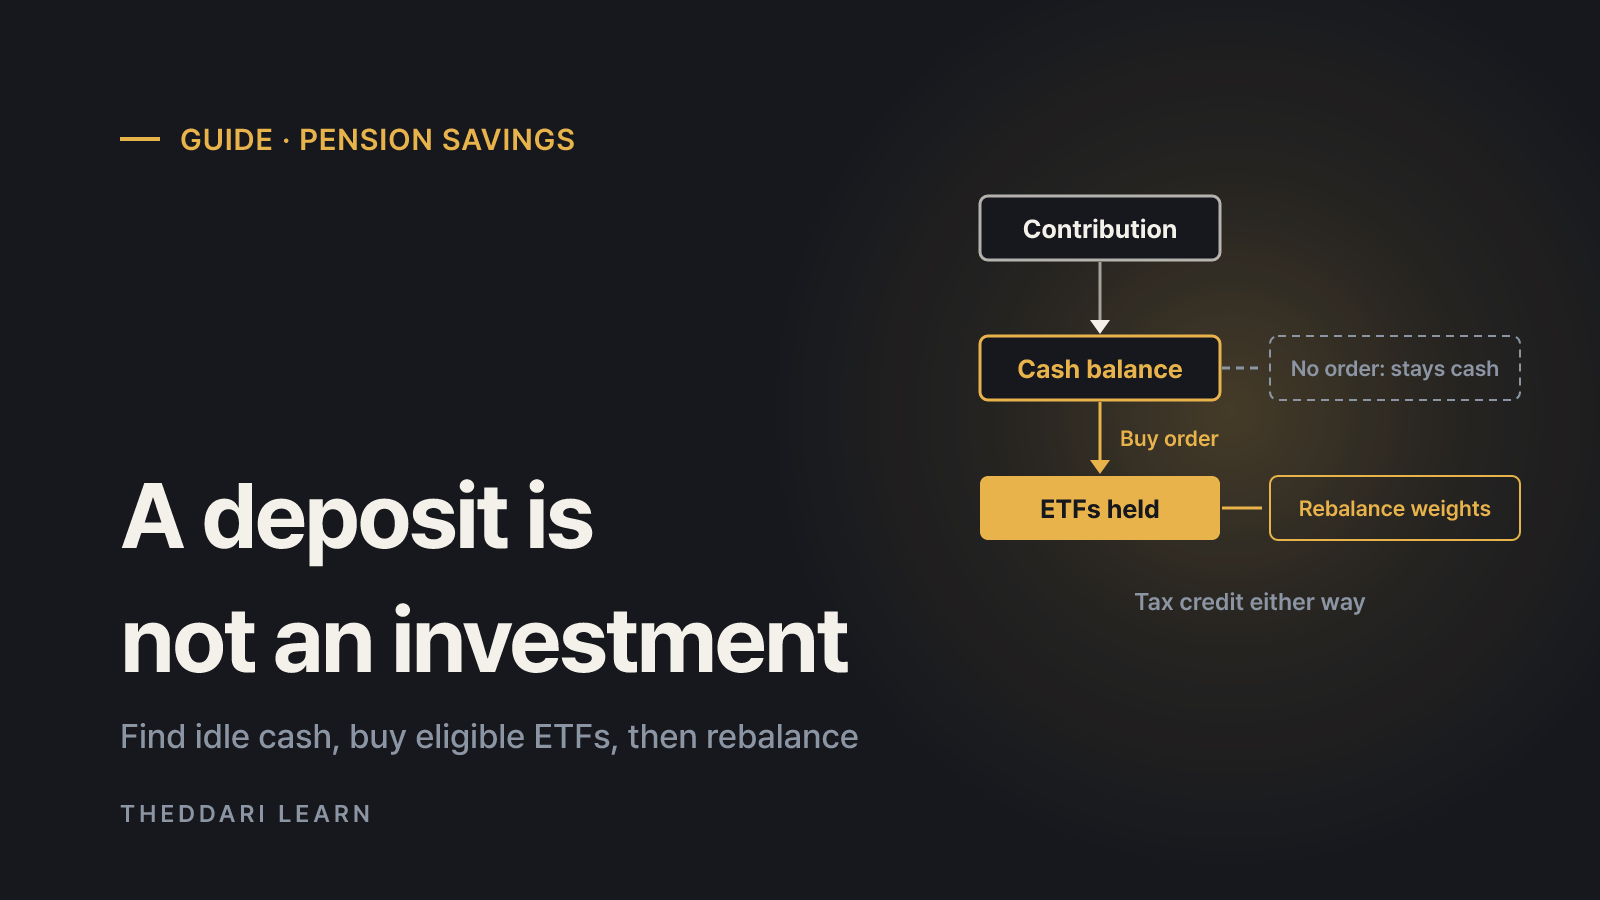 投資ガイド · よくある質問
Korean Pension Savings Fund Idle Cash: ETF Buying Guide
In a Korean brokerage pension savings account, depositing and investing are separate steps. Here is how to find idle cash, buy eligible ETFs, automate purchases and rebalance.
7分閲覧 8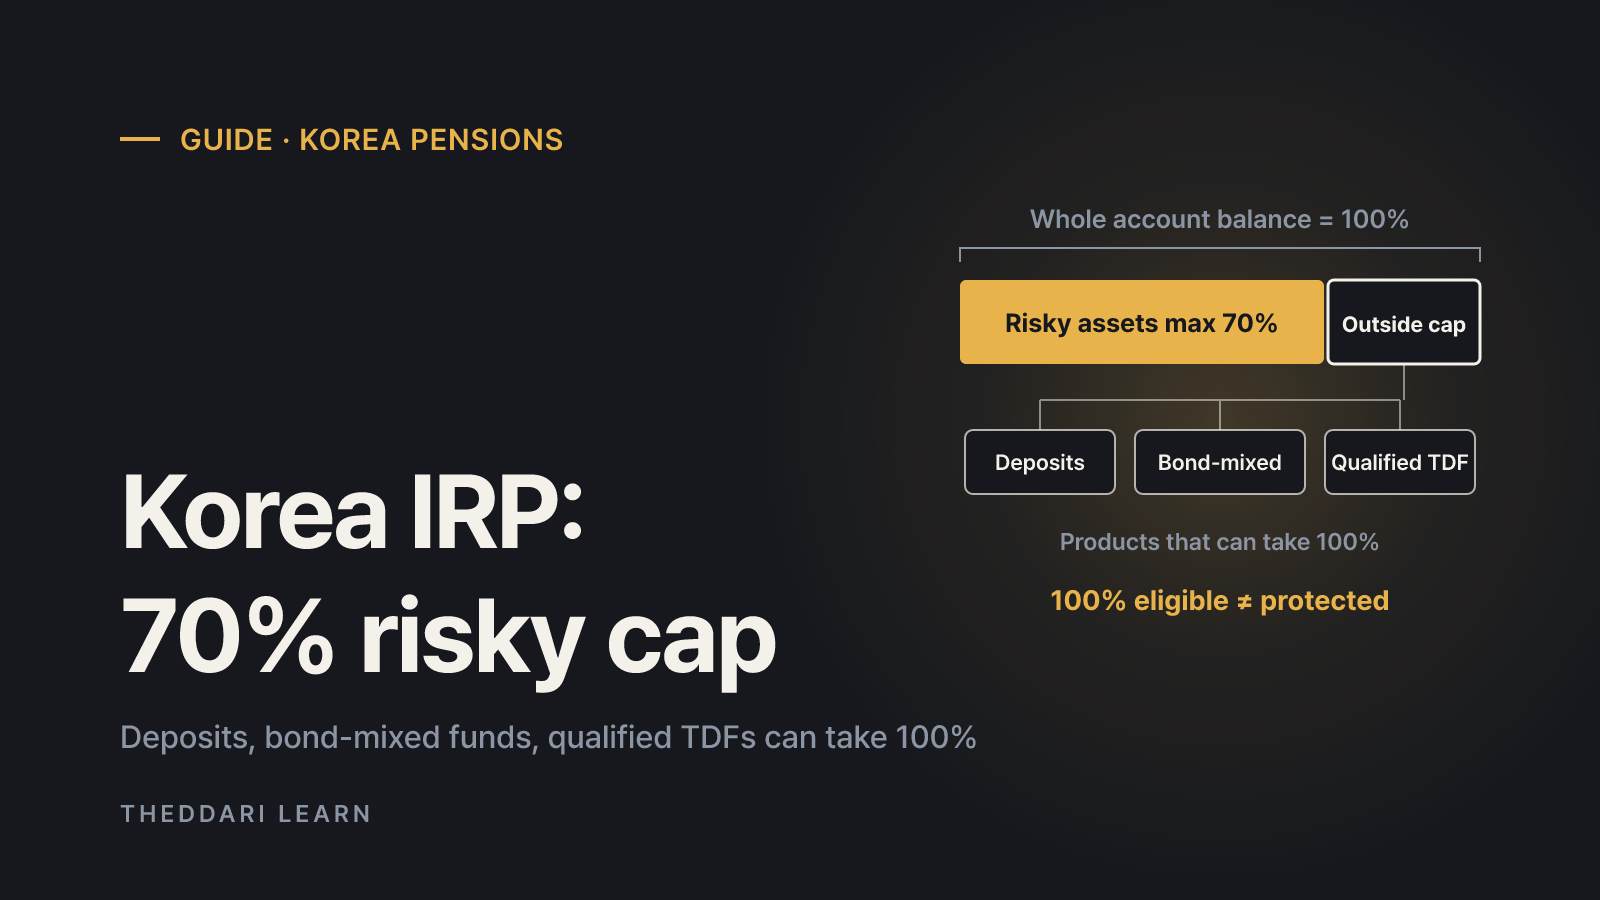 投資ガイド · よくある質問
Korea IRP 70% Limit: What Counts as a Safe Asset
How Korea's 70% risky-asset cap works in DC and individual IRP retirement accounts, which products may fill 100% of the balance, what changed for qualified TDFs in April 2026, and why regulators say a 100% label is not a safety label.
7分閲覧 8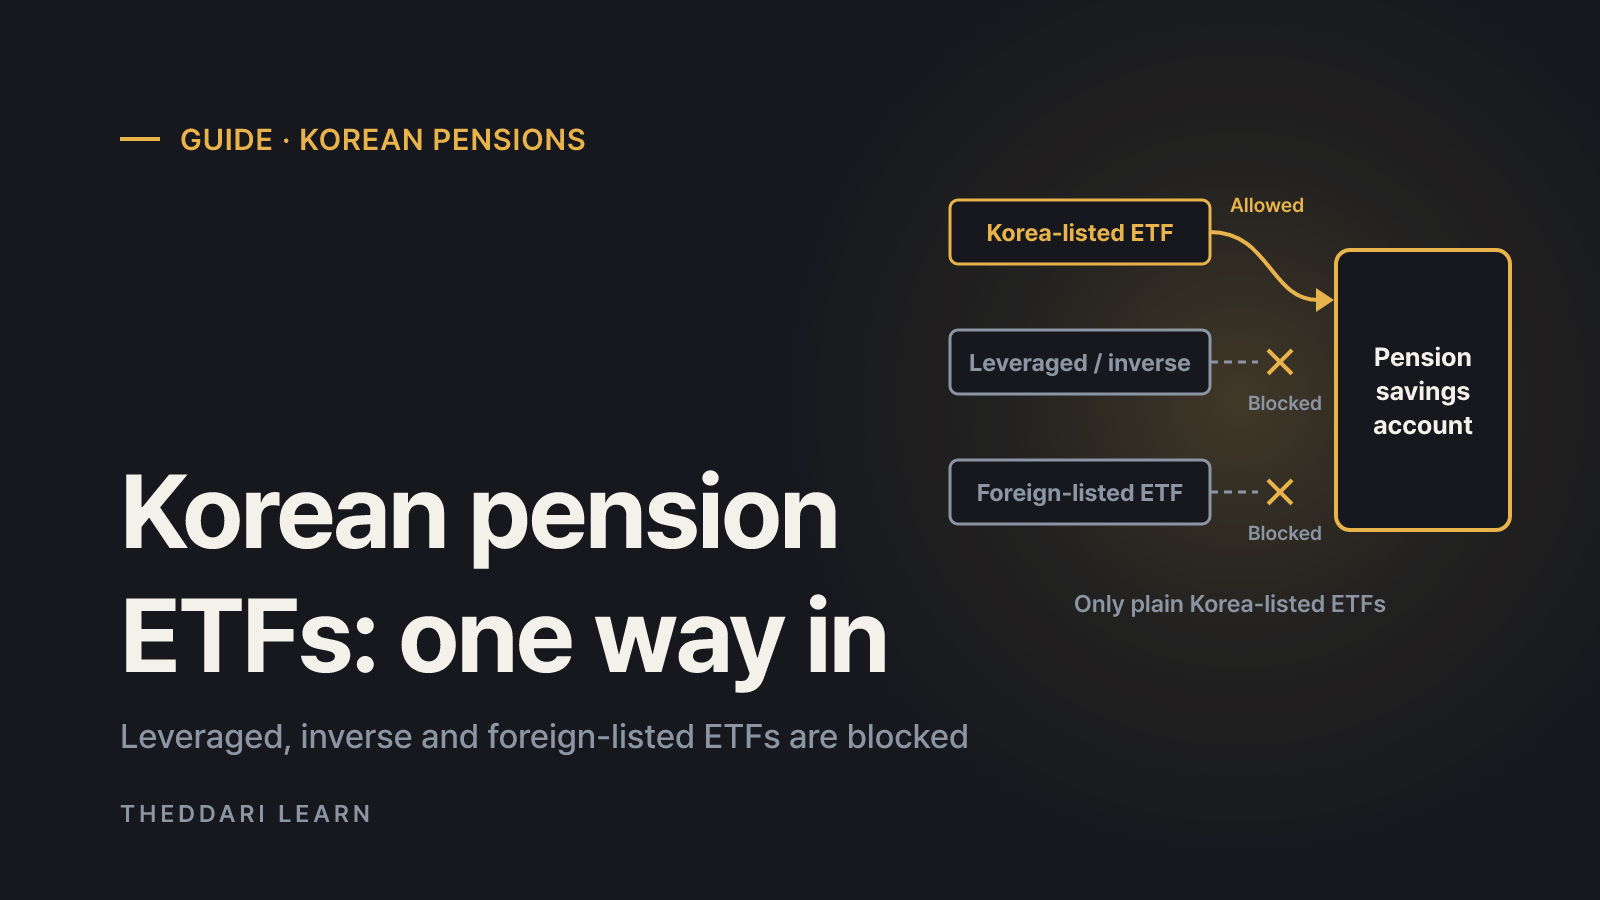 投資ガイド · よくある質問
Korean Pension Savings ETF Limits: Leveraged and US ETFs
Korea's pension savings account (yeongeum jeochuk) lets you trade ETFs listed on the Korea Exchange, but not leveraged, inverse or foreign-listed funds. Here is what is allowed, why, and how it differs from IRP and DC plans.
7分閲覧 8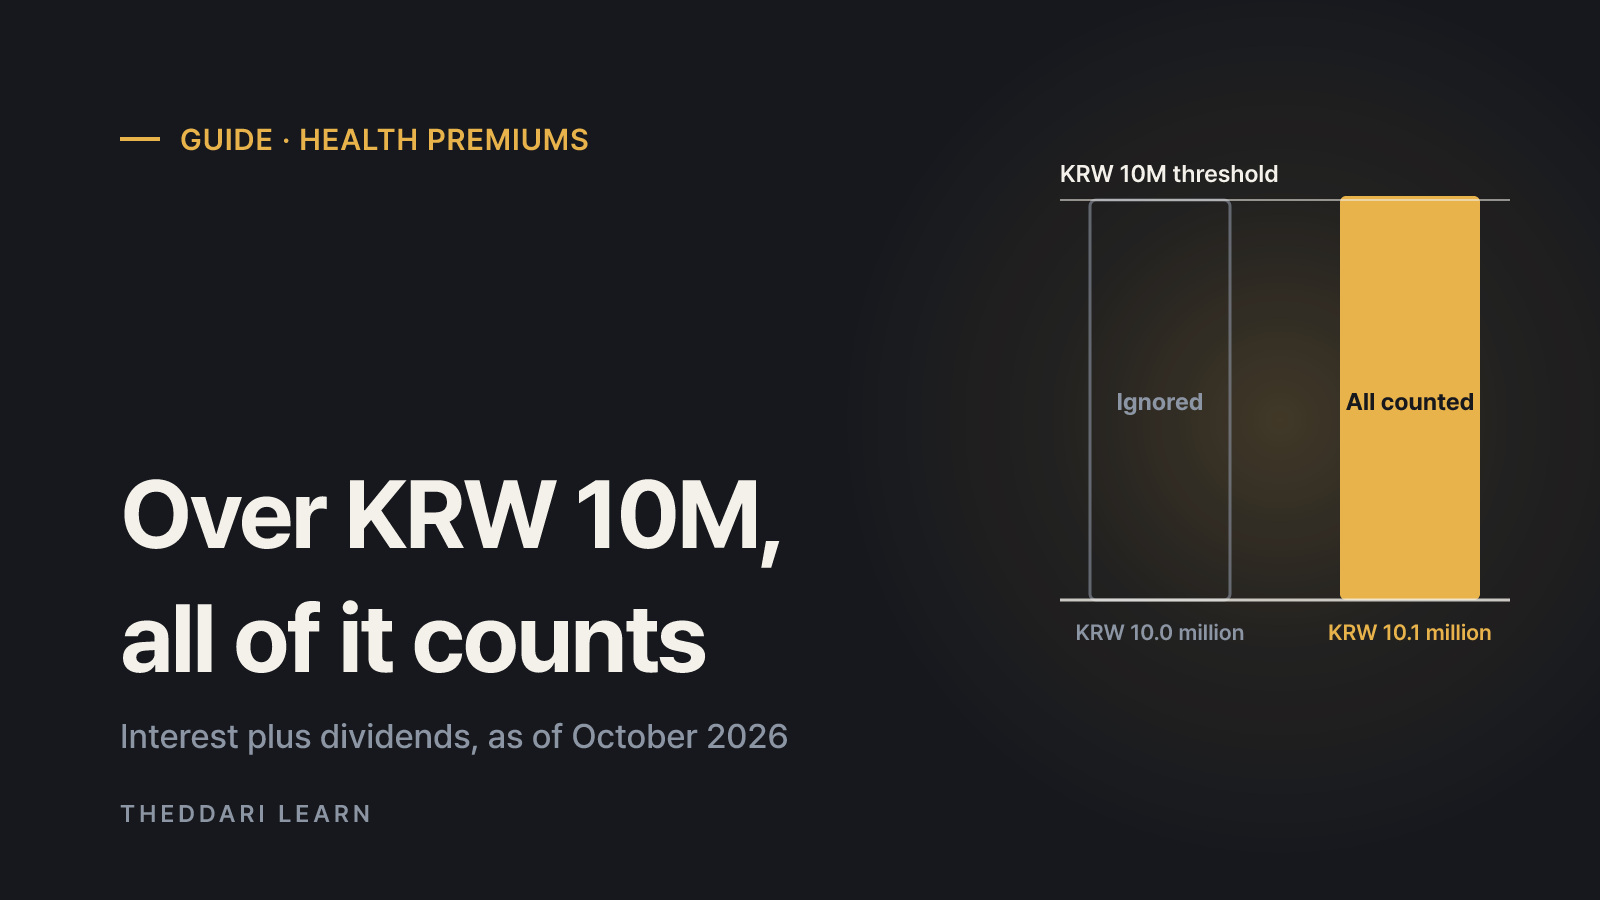 投資ガイド · よくある質問
Do Dividends Raise Korean Health Insurance Premiums?
A plain-English guide for people covered by Korea's National Health Insurance: when dividends start counting, how dependents lose status, what regional and employee subscribers pay, and which ETF payouts are excluded. Checked against NHIS and statute pages in October 2026.
6分閲覧 8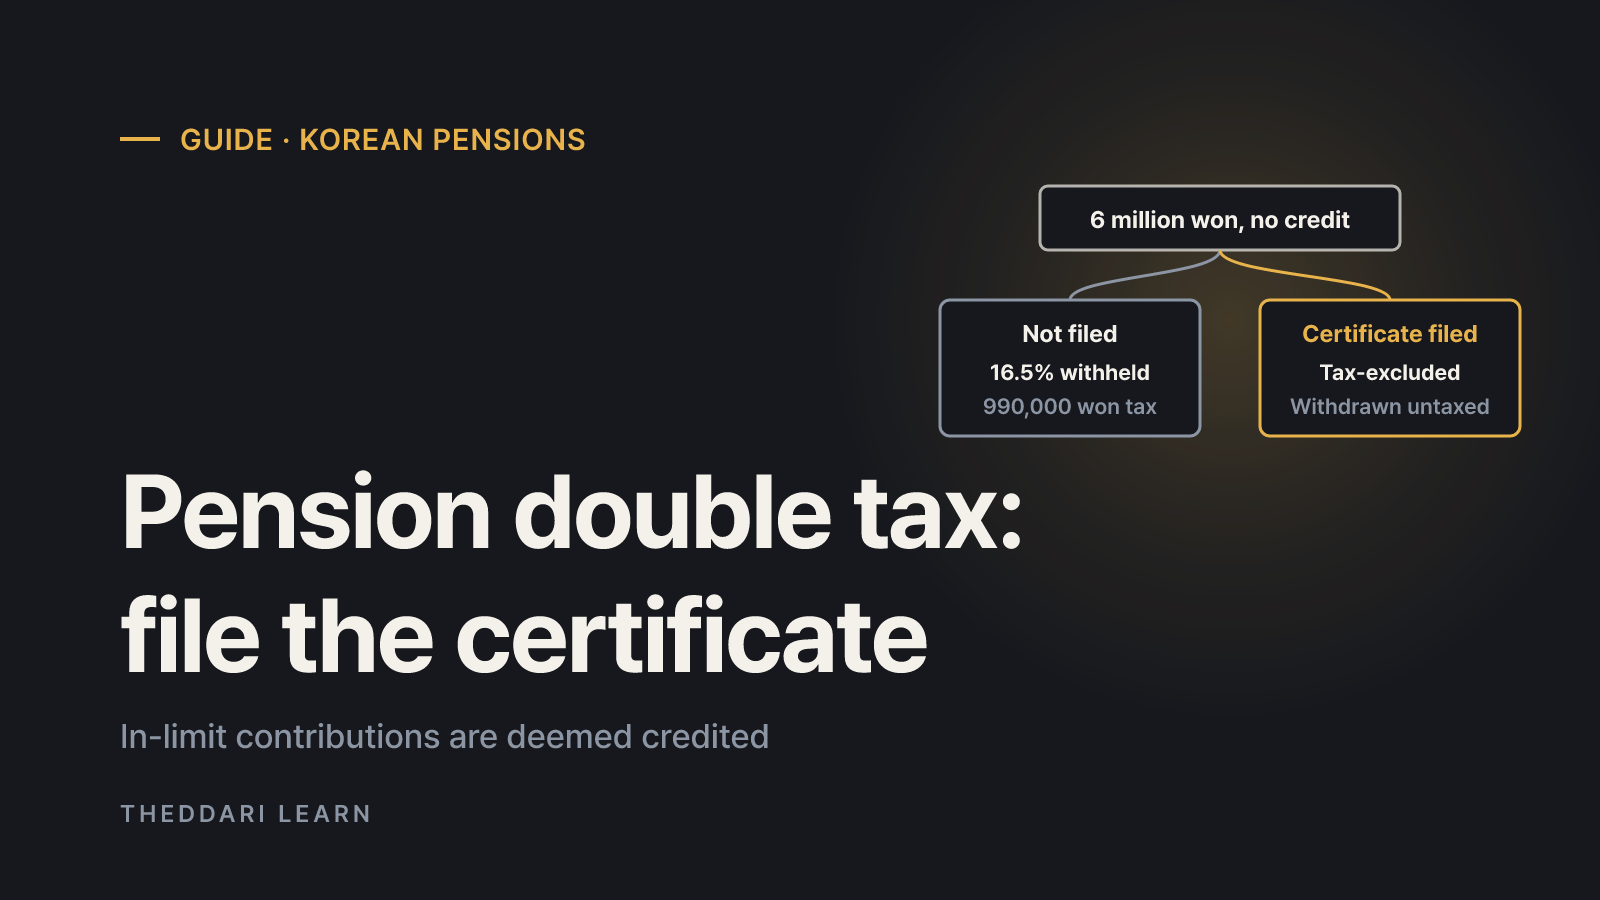 投資ガイド · よくある質問
Korean Pension Savings Double Tax: Uncredited Contributions
Under Korean tax rules, pension savings contributions within the annual credit limit are deemed credited even if you never claimed the credit. Here is how Korean residents register those amounts as tax-excluded before withdrawing.
7分閲覧 9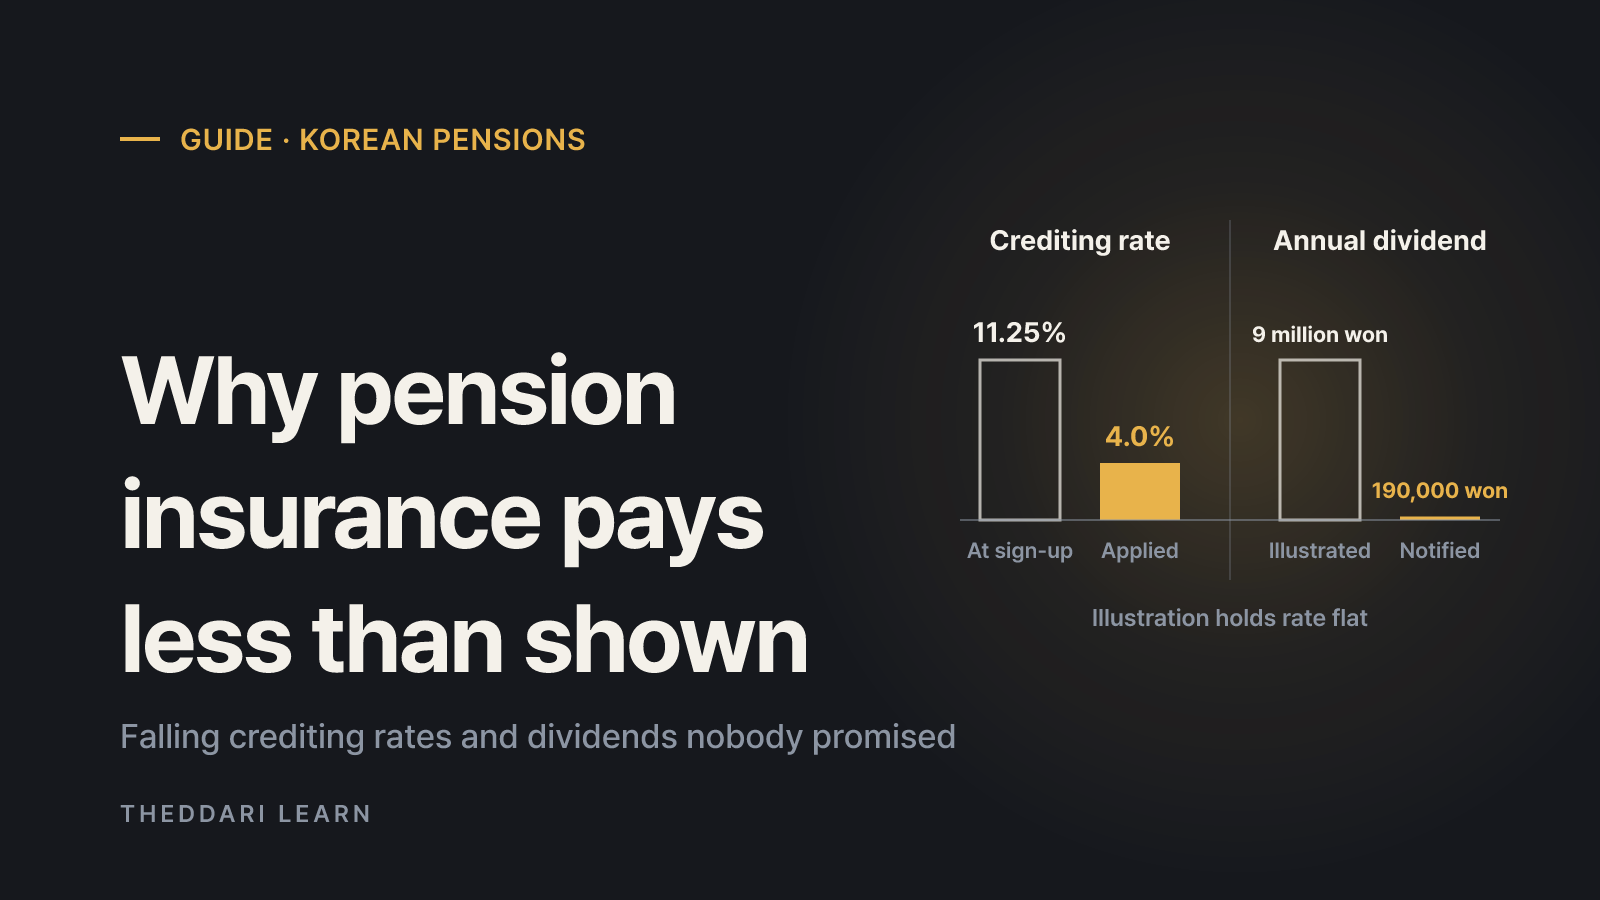 投資ガイド · 最新
Why Pension Savings Insurance Payouts Fall Short in Korea
The pension shown in a Korean pension savings insurance illustration assumes the sign-up crediting rate never changes. Using October 2026 FSS dispute cases, this guide explains what changed and how to check your own contract.
8分閲覧 9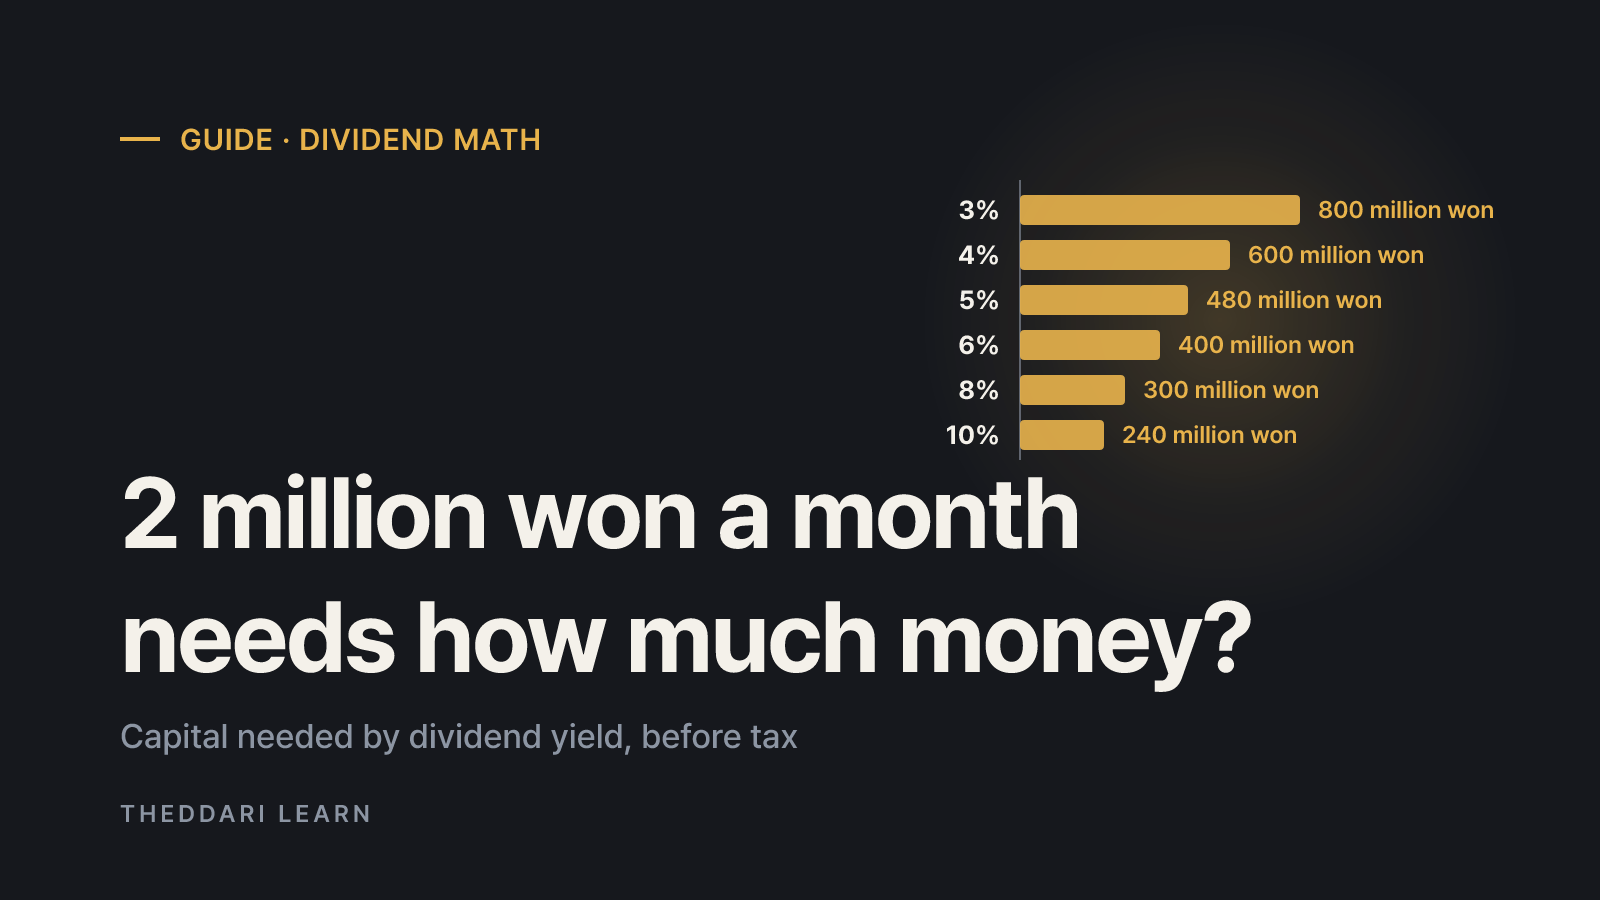 投資ガイド · よくある質問
2 Million Won Monthly Dividend Income: Capital and Korea Tax
2 million won a month in dividends takes 600 million won at a 4% yield before tax, and more after tax. As of October 2026, see how Korea's 15.4% withholding, the 20 million won threshold and new high-dividend rules change the math.
8分閲覧 17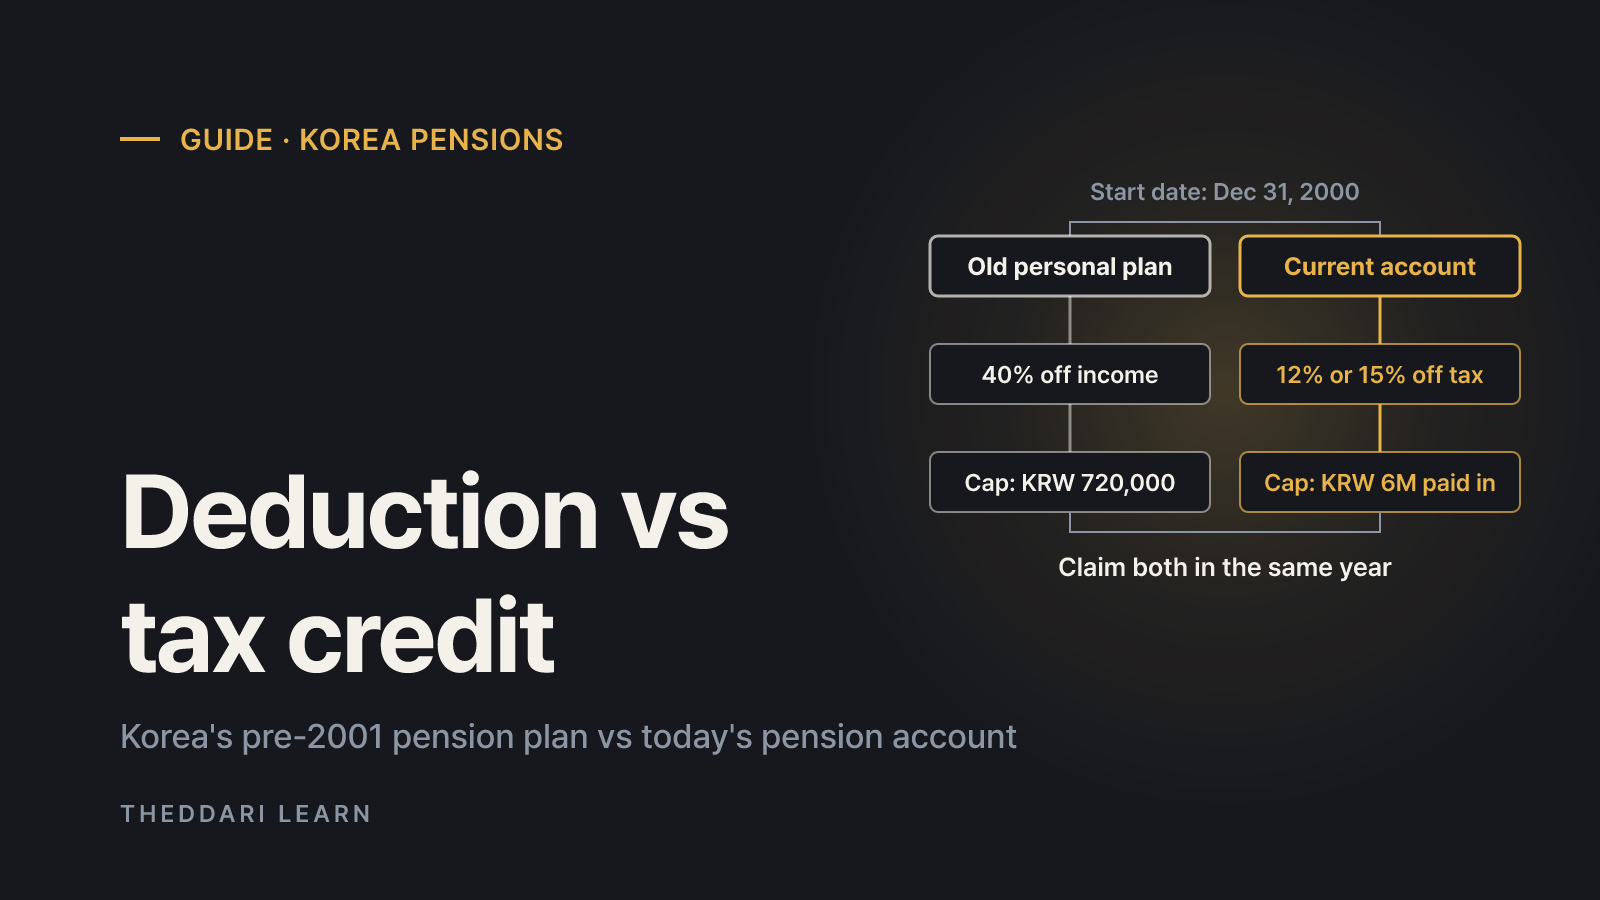 投資ガイド · よくある質問
Korea personal pension savings: old deduction vs tax credit
Korean residents who opened a personal pension savings plan by December 31, 2000 still get a 40% income deduction (capped at KRW 720,000). Here is how that differs from today's 12-15% pension account tax credit, whether you can claim both, and what happens if you cancel.
7分閲覧 11