Retirement Investing for Beginners: How Much to Save and How to Balance Risk
Retirement investing for beginners: estimate your savings gap, balance safer and riskier assets, rebalance, and check 2026 401(k) and IRA limits.
目次7セクション
要点
- Estimate your gap first: expected monthly spending in retirement minus Social Security and pension income, then multiply by the years you plan to fund.
- The U.S. Department of Labor cites an expert estimate that you will need 70 to 80 percent of preretirement income; treat it as a starting point, not your number.
- Your mix of stocks, bonds and cash depends on time horizon and risk tolerance; many retirement savers shift toward bonds and cash as retirement approaches.
- Rebalance on a schedule, such as every six or 12 months, or when an asset class drifts past a preset band.
- For 2026 the IRS limits are $24,500 for 401(k) deferrals and $7,500 for IRAs, with higher catch-up amounts for savers 50 and older.
Retirement investing starts with one question: how big is the gap between what you will spend and what Social Security or a pension will pay? Once you know that gap, you can estimate how much to save and decide how to split money between safer assets, such as cash and bonds, and riskier assets, such as stocks. This beginner's guide uses U.S. government sources checked as of October 2026. Contribution limits and Social Security apply to the United States; readers elsewhere should use their own country's pension and tax rules. Nothing here recommends a specific fund or allocation.
Retirement investing goal: calculate your income gap
A popular rule of thumb says you need a fixed dollar amount to retire. Your real number depends on where you live, your health, your housing costs and how many years you work. The U.S. Department of Labor notes that experts estimate you will need 70 to 80 percent of your preretirement income to maintain your standard of living. The same page says retirement beneficiaries receive, on average, about 40 percent of preretirement income from Social Security, and that the average American spends roughly 19 years in retirement. Those averages show why personal savings usually need to cover a meaningful share.
- 1
Estimate monthly spending in retirement
Start with your current budget. Remove costs that will end, such as commuting or a mortgage you expect to pay off, and add costs that may rise, such as health care and travel.
- 2
Subtract income sources you can verify
Use the retirement estimator on the Social Security Administration's website and any pension benefit statement from your employer. Record each amount and the age it starts.
- 3
Multiply the gap by the years you need to fund
Monthly gap × 12 × years in retirement gives a simple total that ignores inflation and investment growth. Then test several inflation and return assumptions in a retirement calculator to build a range.
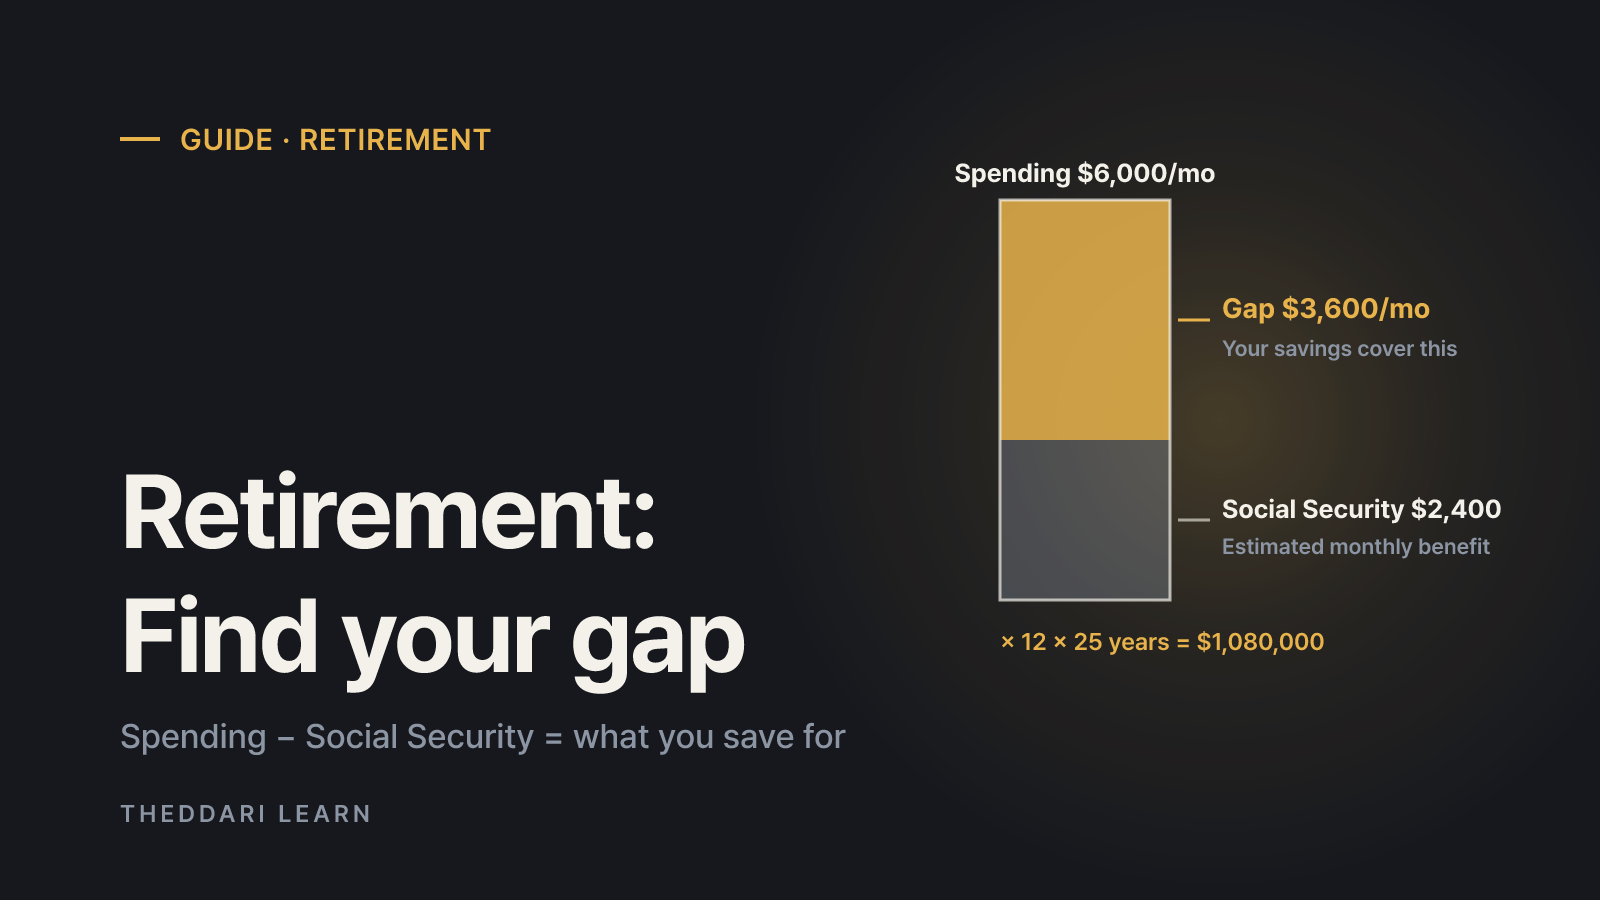
Here is a hypothetical example. Suppose you expect to spend $6,000 a month and Social Security is estimated at $2,400. The gap is $3,600 a month. Over 25 years, $3,600 × 12 × 25 = $1,080,000 before inflation or growth. Inflation raises the amount you need, while returns earned on money still invested in retirement reduce it. Running an optimistic, a base and a cautious case is more honest than relying on one figure.
A retirement calculator only reflects the assumptions you enter. Raising the expected return by one percentage point can shrink the required savings dramatically, so be wary of results that depend on optimistic returns.
How to balance safer and riskier assets
The SEC's Investor.gov defines asset allocation as dividing investments among assets such as stocks, bonds and cash, and calls it a personal decision. The two main inputs are your time horizon, meaning how many years until you need the money, and your risk tolerance, meaning your ability and willingness to see losses in exchange for potentially higher returns. Investors with long horizons may accept more volatile assets; those with short horizons may prefer steadier ones.
Cash equivalents
- Examples
- Savings, money market funds, Treasury bills
- Main job
- Emergency fund, near-term spending
- Risk people overlook
- Inflation erodes purchasing power
Bonds
- Examples
- Treasuries, corporate bonds, bond funds
- Main job
- Income, lower volatility
- Risk people overlook
- Prices fall when rates rise; issuer default
Stocks
- Examples
- Individual shares, stock funds and ETFs
- Main job
- Long-term growth
- Risk people overlook
- Deep drawdowns and slow recoveries
Target date funds
- Examples
- Funds named for a retirement year
- Main job
- Automatic shift over time
- Risk people overlook
- Glide path may not match your situation
A practical way to decide is to match each dollar to when you will spend it. Money needed in the next few years belongs in safer assets, while money you will not touch for a decade or more can carry more stock risk. Investor.gov notes that most people investing for retirement hold less stock and more bonds and cash as they approach retirement age, and that a target date fund's adviser typically makes the fund more conservative as the target year nears.
Diversify inside each asset class too
Owning several funds does not automatically mean you are diversified. A narrowly focused fund, such as one sector, can leave you concentrated. Investor.gov suggests checking the top holdings of each fund to confirm they actually differ. It also cautions that free online risk questionnaires may be biased toward products sold by the website's sponsor.
Rebalance and review on a schedule
Markets move your allocation away from its target. In Investor.gov's example, a portfolio that started at 60 percent stocks can drift to 80 percent after a rally, which means you now carry more risk than you planned. Rebalancing means selling some of the overweight asset, directing new contributions to the underweight one, or both. Some experts rebalance every six or 12 months; others act only when an asset class moves past a preset percentage. Either way, infrequent rebalancing tends to work best. Doing it inside a 401(k) or IRA can avoid triggering taxable gains that would apply in a regular brokerage account.
Interest rates and inflation affect the yields on cash and bonds. The theddari economic calendar lists scheduled CPI, jobs and central bank releases, which can help you pick review dates. If you hold individual stocks, the earnings calendar shows when those companies report. These tools organize schedules; they do not predict prices.

2026 U.S. retirement account limits to know
According to the IRS announcement for 2026, contribution limits rose for most workplace plans and IRAs. Income limits also apply to deducting traditional IRA contributions and to contributing to a Roth IRA, so check the full notice before you contribute.
401(k), 403(b), governmental 457, TSP
- 2026 limit
- $24,500
- Notes
- Employee elective deferrals
Catch-up, age 50+
- 2026 limit
- $8,000
- Notes
- Most 401(k)-type plans; total up to $32,500
Catch-up, ages 60 to 63
- 2026 limit
- $11,250
- Notes
- Higher SECURE 2.0 limit, if the plan allows
IRA
- 2026 limit
- $7,500
- Notes
- Plus $1,100 catch-up at age 50+
The Department of Labor also suggests learning how much you need to contribute to receive your employer's full match and how long you must stay to keep it. Avoid treating retirement accounts as an emergency fund: early withdrawals can cost you principal, growth and tax benefits, and may trigger penalties.
Beginner mistakes and a simple checklist
- Investing before building an emergency fund, which can force you to sell stocks during a downturn.
- Changing your mix because one asset recently did well; that is chasing performance, not rebalancing.
- Ignoring fees, which compound over decades just like returns.
- Skipping your Social Security estimate, which leaves the income gap unknown.
- Setting a plan once and never revisiting it after a job change, marriage or health event.
In short: estimate your gap, match money to its time horizon, choose accounts that fit your tax situation, rebalance infrequently and recalculate every year. This process does not promise an outcome, but it shows what you know and what still needs research.
よくある質問
How much should I invest for retirement each year?
Is the '110 minus your age' rule a good retirement investing strategy?
Are bonds and cash risk-free for retirees?
What happens if I withdraw from my 401(k) or IRA early?
出典・参考資料
関連記事
 投資ガイド
Stock Market Circuit Breakers and Sidecars: US vs Korea
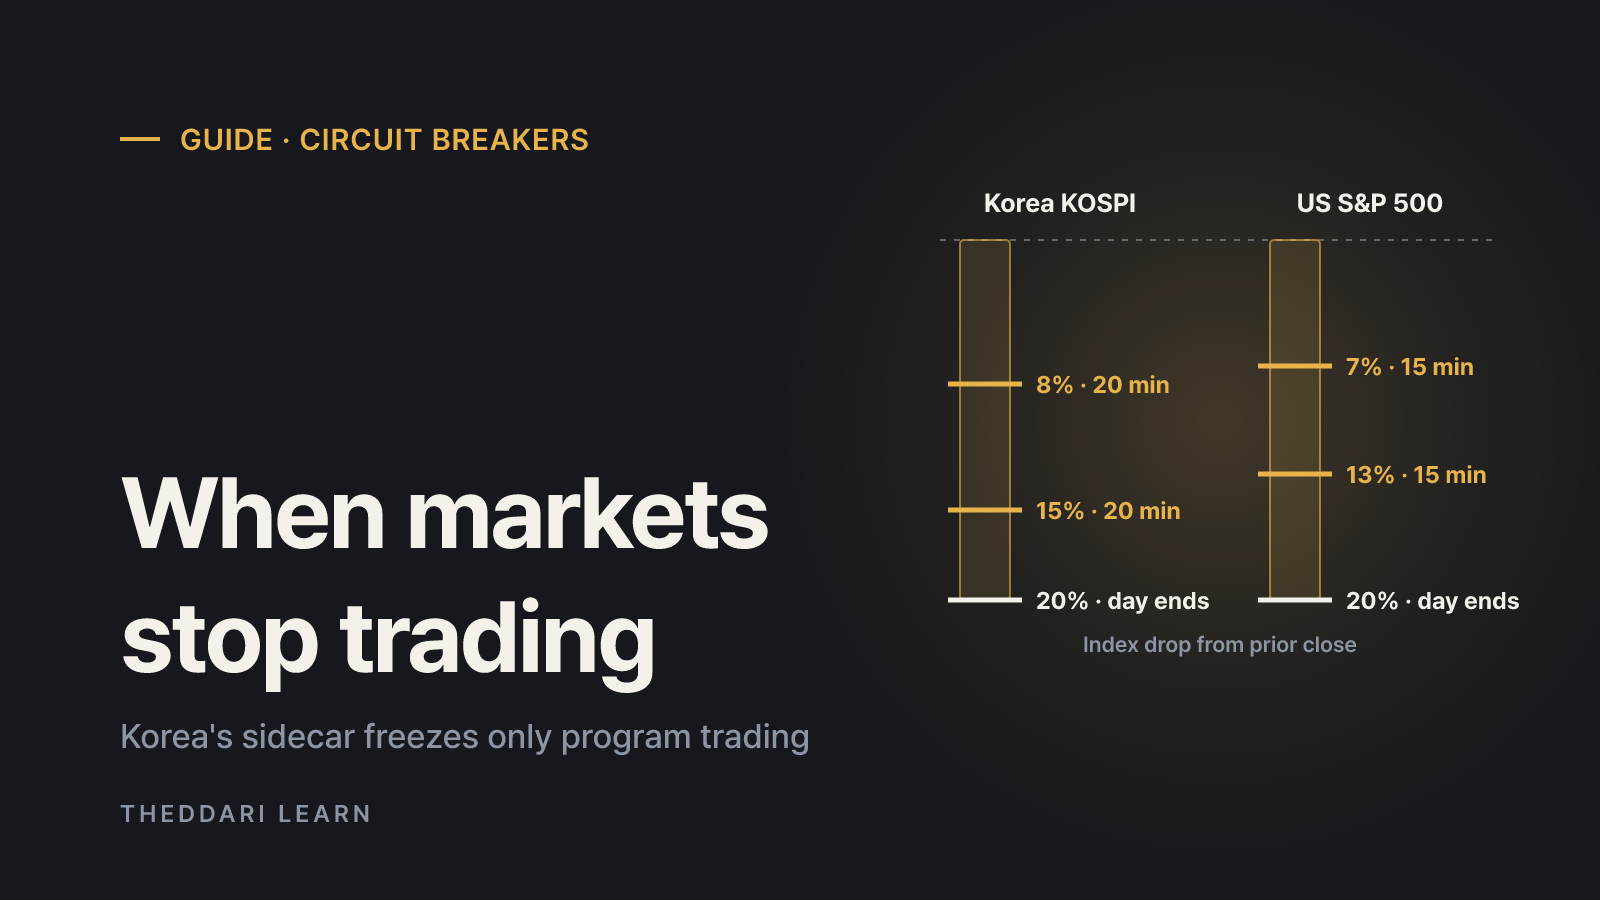
US market-wide circuit breakers halt all trading when the S&P 500 drops 7%, 13% or 20%. Korea uses 8%, 15% and 20% thresholds plus a sidecar that freezes only program trading. Here is how each rule works and what happens to your orders.
 投資ガイド
Pension Withdrawal Order in Korea: How IRP Money Is Taxed
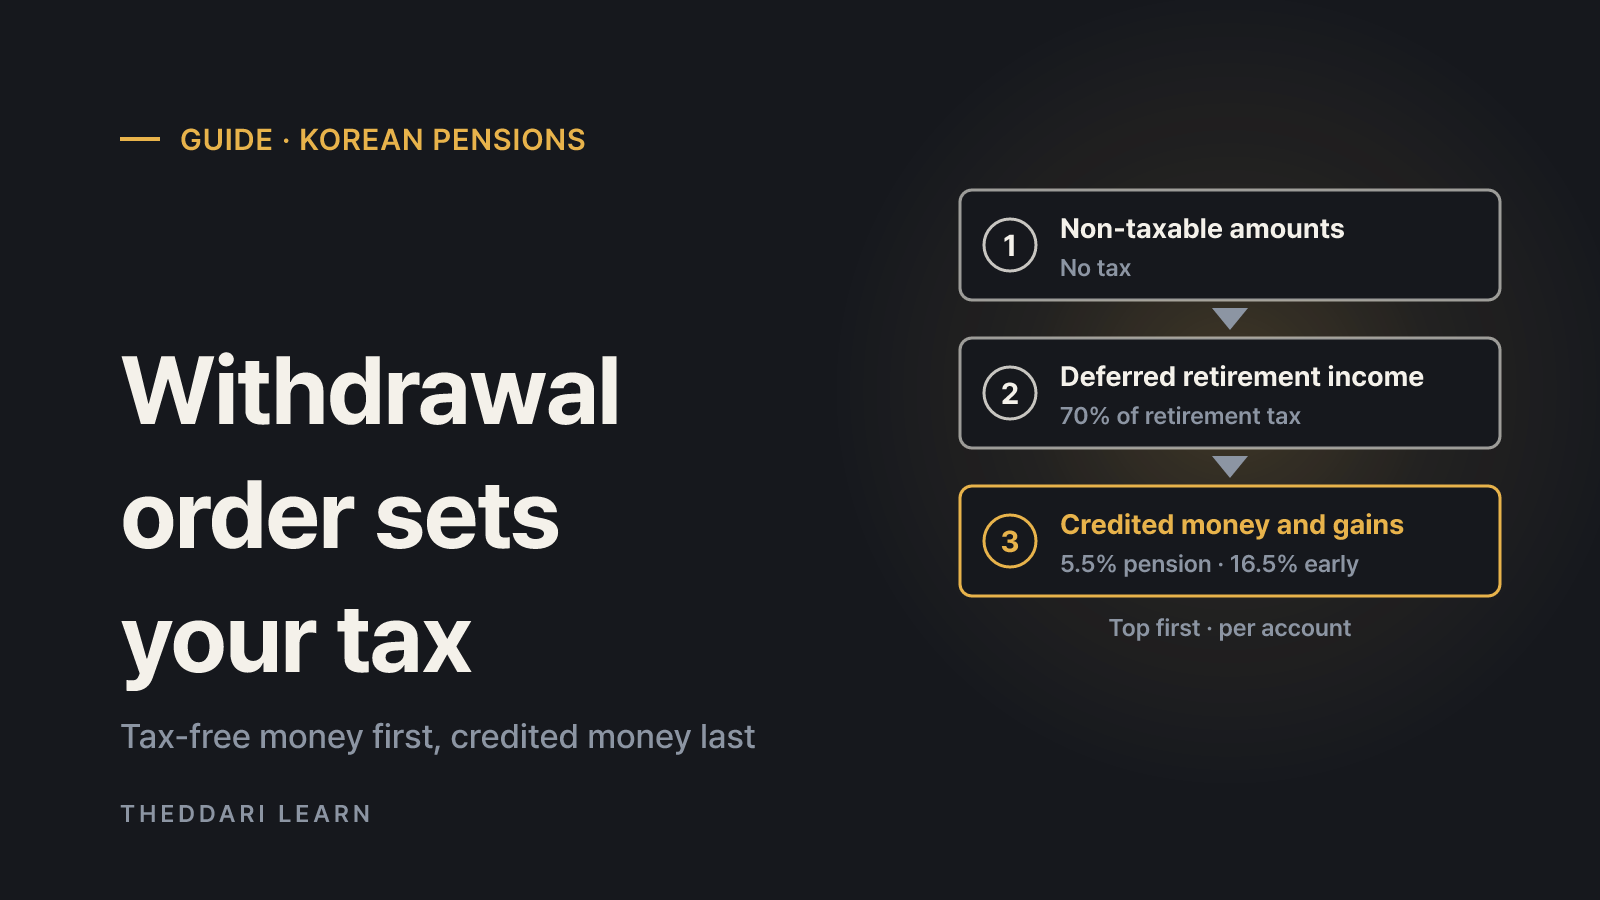
When you take part of the money out of a Korean pension savings account or IRP, the law decides which money left first, and each part is taxed differently. A November 2026 guide to the withdrawal order, rates and exceptions for Korean tax residents.
 投資ガイド
How to Buy ETFs in Singapore: CDP vs Custodian and Fees
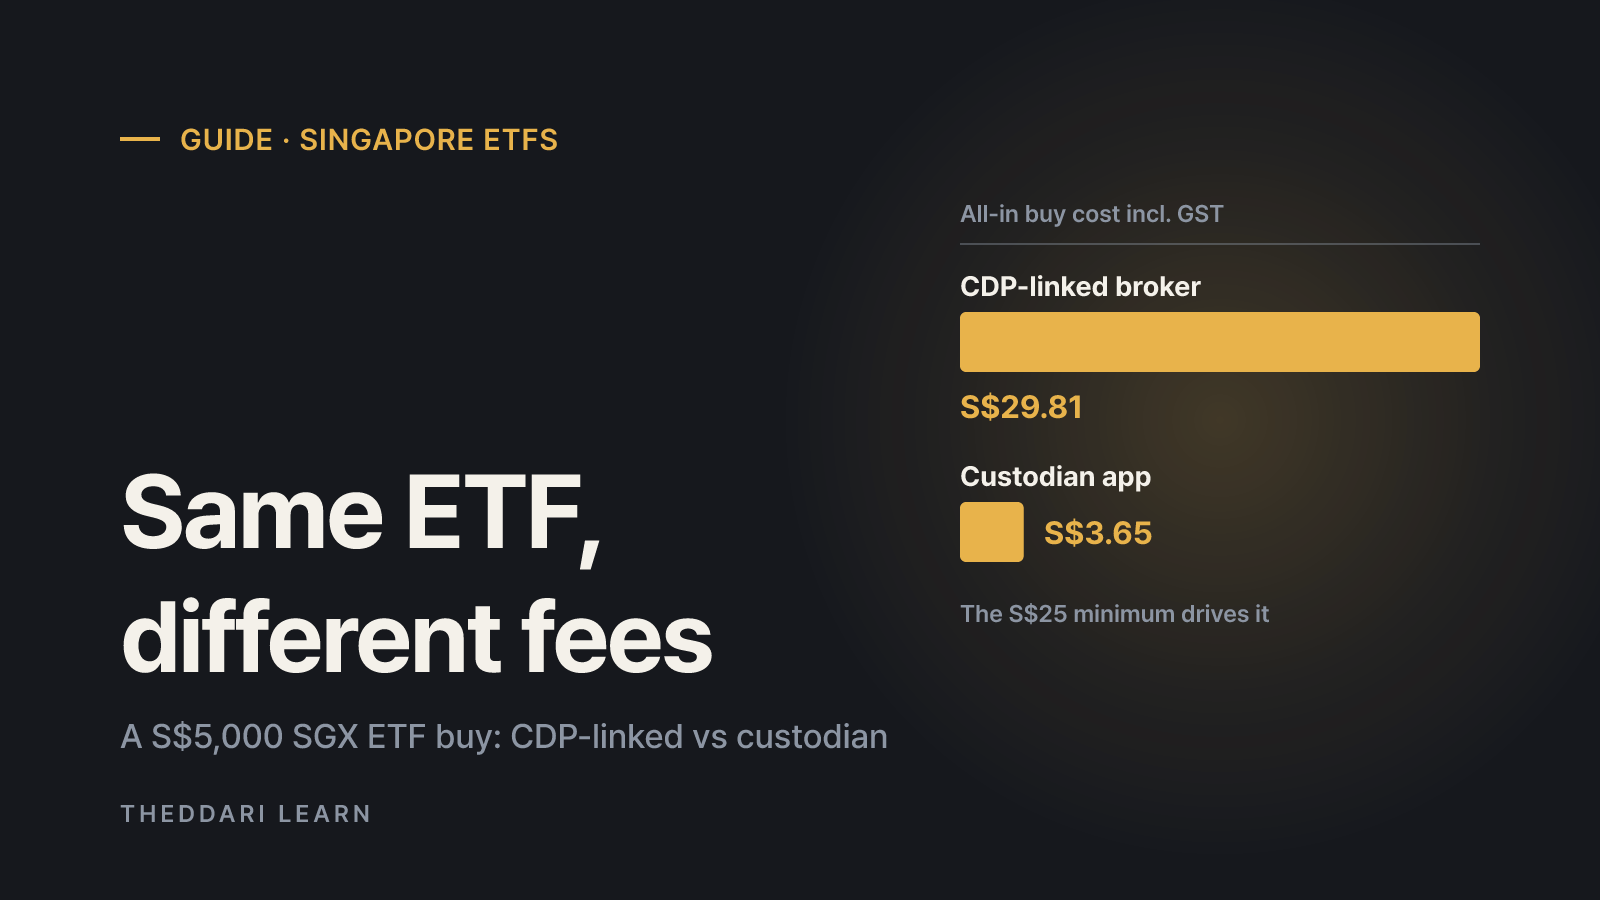
A practical guide for Singapore residents: how SGX-listed and US-listed ETFs are held, what the CDP rule changes of July 2026 mean for custodian accounts, and what a trade really costs at different order sizes.