What Does LG Innotek Do? Its Camera Module Business and Key Earnings Metrics
LG Innotek makes iPhone-grade camera modules, chip substrates and auto parts. See its segment mix, Apple concentration and the metrics to watch in its earnings.
目次6セクション
要点
- LG Innotek (KRX: 011070) is a Korean LG Group component maker with three units: optical solutions (camera modules), package solutions (chip substrates) and mobility solutions (auto parts).
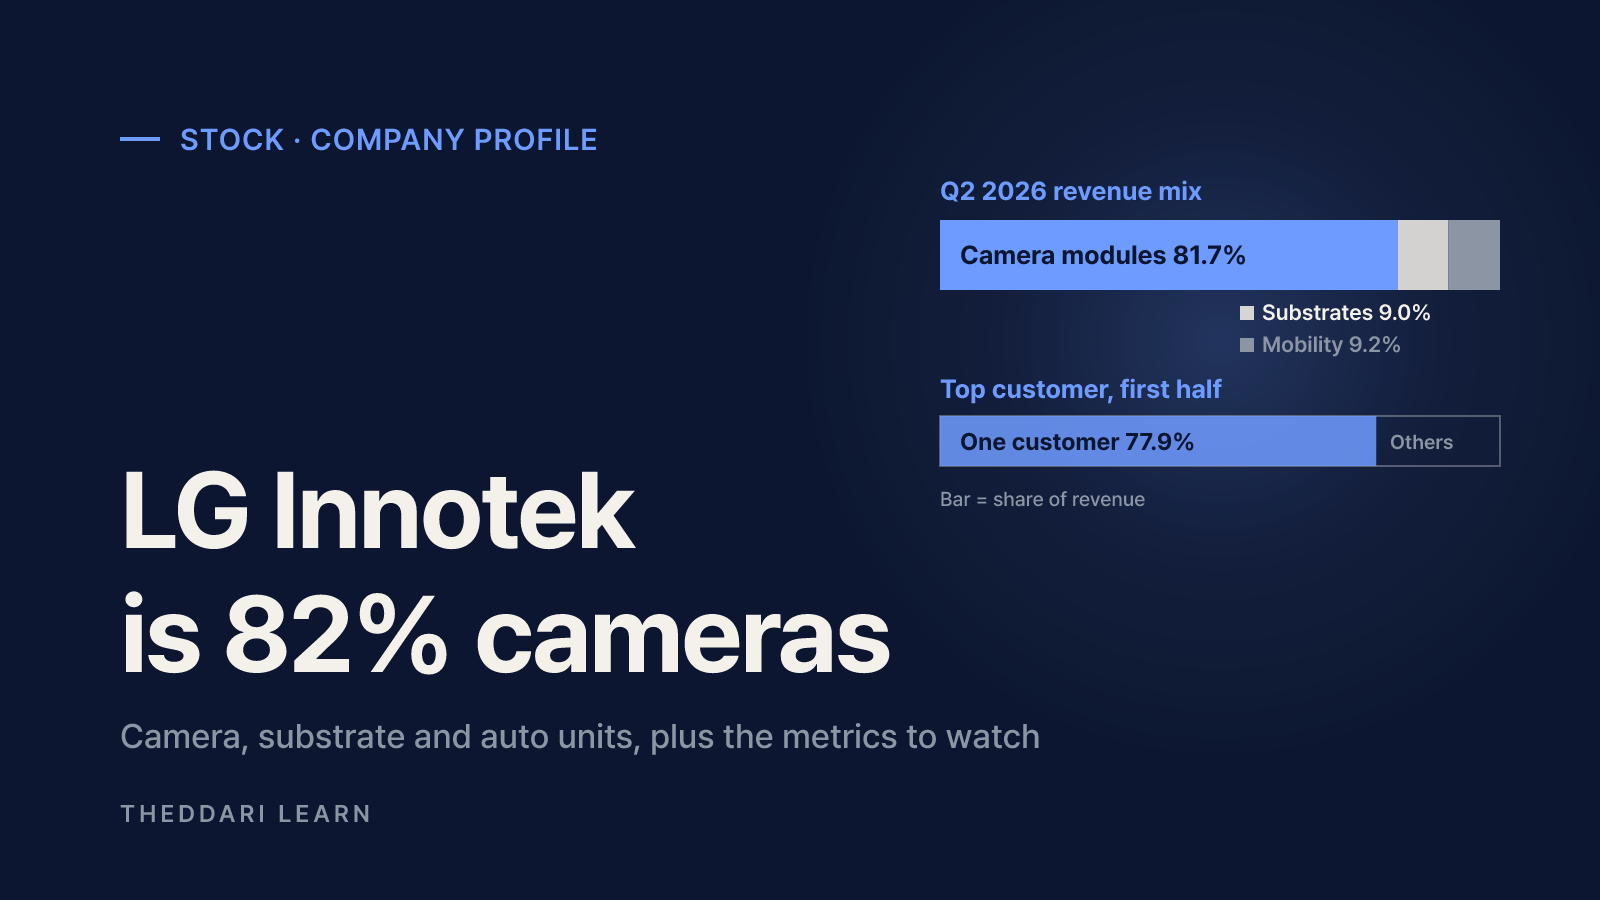
- In Q2 2026, optical solutions produced 4.5179 trillion won of the company's 5.5272 trillion won revenue, roughly 82%.
- Its semi-annual report shows a single unnamed customer, widely believed to be Apple, accounted for 77.9% of first-half 2026 revenue.
- On October 12, 2026, the shares fell 16.17% to 479,500 won as brokers cut third-quarter profit estimates, citing currency effects.
- For each earnings release, track segment revenue and profit, operating margin, the won-dollar rate, customer concentration, utilization and substrate capex.
LG Innotek is a South Korean electronic components maker in the LG Group, best known as a major supplier of high-end smartphone camera modules. It also makes semiconductor package substrates and automotive parts. As of October 2026, camera modules dominate the numbers: in the second quarter of 2026, about 82% of its 5.5272 trillion won (roughly $3.9 billion) revenue came from the optical solutions unit, and most sales go to a single customer widely believed to be Apple. That concentration is why a few metrics matter far more than the headline revenue figure. This guide uses the company's own preliminary results and its semi-annual report as reported by the press. It does not recommend buying or selling the stock.
Why it is in the news: on October 12, 2026, LG Innotek shares closed down 16.17% at 479,500 won on the Korea Exchange. Hankyung reported that falling third-quarter profit estimates and currency headwinds drove the selloff.
How LG Innotek's business is organized
The company reports three business units. Optical solutions builds smartphone camera modules, 3D sensing modules and vehicle cameras. Package solutions makes substrates that connect chips to circuit boards, including RF-SiP for wireless functions, FC-CSP for mobile and memory chips and FC-BGA for PC and server processors, plus display materials. Mobility solutions supplies automotive communication and lighting modules. The table below uses figures from LG Innotek's Q2 2026 release; shares are calculated from those numbers.
Optical solutions
- Main products
- Phone camera modules, 3D sensing, vehicle cameras
- Q2 2026 revenue (KRW)
- 4.5179 trillion
- Share
- ~81.7%
- Year over year
- +48%
Package solutions
- Main products
- RF-SiP, FC-CSP, FC-BGA substrates; display materials
- Q2 2026 revenue (KRW)
- 498.4 billion
- Share
- ~9.0%
- Year over year
- +20%
Mobility solutions
- Main products
- Auto communication and lighting modules
- Q2 2026 revenue (KRW)
- 510.9 billion
- Share
- ~9.2%
- Year over year
- +10%
Total
- Main products
- Consolidated, preliminary (K-IFRS)
- Q2 2026 revenue (KRW)
- 5.5272 trillion
- Share
- 100%
- Year over year
- +40.5%
Operating profit for the quarter was 245.8 billion won, up from just 11.4 billion won a year earlier. The eye-catching 2,057% growth rate reflects that very low base. Compared with the first quarter's 295.3 billion won, profit actually fell 16.8%. Dividing profit by revenue gives an operating margin of about 4.4%, which is thin for a business of this size and explains why small swings in costs or exchange rates move earnings sharply.
Camera modules: the core and the main source of volatility
According to the first-half report as summarized by EDAILY, optical solutions revenue reached 9.1285 trillion won in the first half of 2026, or 82.5% of the total, with 409.9 billion won of operating profit. Camera module plants in Gumi, China and Vietnam ran at an average 85.2% utilization and produced about 241.7 million units. Because production ramps around a customer's annual flagship launch, quarterly results swing with launch timing. The Korea Herald reported that LG Innotek is supplying a variable-aperture main camera module expected in the iPhone 18 Pro, citing industry sources; the company itself does not confirm customer product details.
Substrates: small today, the planned second engine
Package solutions is only about 9% of revenue, but management has said it wants this unit to become a core business. The Gumi substrate plant ran at 94.0% utilization in the first half, up from 80.8% for full-year 2025. In its Q2 release the company said it had started expanding its Vietnam substrate plant and was reviewing further investment. The Korea Herald reported the roughly $1 billion Haiphong plant will focus on RF-SiP and FC-CSP with mass production slated for 2028, while server-grade FC-BGA output at Gumi is targeted for 2027. Timelines like these can slip, so confirm them against later company updates.
Customer concentration: 77.9% from one buyer
The single most important number for understanding LG Innotek is customer concentration. The semi-annual report shows one customer generated 8.8415 trillion won in the first half of 2026, 77.9% of revenue, and the top ten customers together accounted for 86%. The company does not disclose the name, but the customer is widely identified as Apple. When the iPhone's premium models sell well, LG Innotek's revenue and plant utilization rise together. When demand softens or pricing pressure increases, there is little other volume to fill the gap. Diversification into substrates, vehicle sensing and robot vision is the company's answer, yet package and mobility combined were still only about 18% of Q2 revenue.
Seven LG Innotek earnings metrics to watch
Headline revenue and operating profit rarely tell the full story for a company this concentrated. Use the theddari earnings calendar to note the next report date, then compare the release against these items.
- Segment revenue mix: is optical solutions still near 82%, and is package solutions gaining share?
- Segment profit: half-year and annual reports break out segment operating profit. The Korea Herald noted package solutions earned close to a fifth of 2025 operating profit on about a tenth of revenue.
- Operating margin: about 4.4% in Q2 2026. Rising revenue with a falling margin points to cost, currency or pricing pressure.
- The won-dollar exchange rate: industry figures cited by Hankyung put the average rate at 1,502 won per dollar in Q2 and 1,418 in Q3, a stronger won that shrinks dollar sales in won terms.
- Customer concentration: watch whether the 77.9% single-customer share moves in the next periodic report.
- Utilization: camera modules (85.2%) and Gumi substrates (94.0%) in the first half signal demand and the need for new capacity.
- Capex and timelines: track spending and progress at the Vietnam and Gumi substrate sites and the FC-BGA server ramp.

Reading estimates versus results
Share prices often react to the gap between results and consensus rather than the raw numbers. Ahead of Q3 2026, Yuanta Securities forecast revenue of 6.2594 trillion won and operating profit of 78.7 billion won, down from a prior 320 billion won profit estimate, according to Hankyung. In the same report, Mirae Asset described the weakness as largely a temporary currency effect, and DB Securities said much of the concern was already priced in. Treat brokerage estimates and price targets as opinions, and compare the company's reported figures and commentary directly. Parent LG Electronics' weaker-than-expected Q3 preliminary operating profit of 781.8 billion won was also cited as a hint about its consolidated subsidiary, but that link is an inference.
During sharp moves, rumors spread quickly on Telegram channels and forums. The theddari stock Telegram trends page shows which topics are being discussed most, but mention volume says nothing about accuracy, so verify claims against official filings.
Risks to keep in mind
- Concentration: a 77.9% single-customer share means that customer's sales trends and pricing decisions flow straight into results.
- Seasonality and timing gaps: mismatches between material purchases, inventory and shipment dates can cut profit even when revenue grows.
- Currency: a stronger Korean won reduces the won value of dollar-denominated sales.
- Capex: if substrate demand undershoots, new plants bring depreciation costs and low utilization.
- Competition: both camera modules and substrates face Korean, Japanese, Taiwanese and Chinese rivals.
- Information quality: customer names and component wins are often industry-sourced reports rather than company disclosures.
In short, LG Innotek is a camera module business with a growing substrate arm. A single day's price drop says little on its own; the next earnings report's segment mix, margin, currency commentary and substrate utilization will show whether the structure is actually changing. Figures here reflect preliminary results and reports available as of October 2026 and may be revised in final filings. Readers outside Korea should also check how their own broker and tax jurisdiction treat Korean-listed shares.
よくある質問
Is LG Innotek an Apple supplier?
Why did LG Innotek stock drop in October 2026?
Can US investors buy LG Innotek shares?
How big is LG Innotek's substrate business?
出典・参考資料
- 1LG Innotek Newsroom: Q2 2026 preliminary results (July 27, 2026, Korean)(新しいタブで開きます)news.lginnotek.com
- 2EDAILY: LG Innotek 77.9% of First-Half Revenue Came from Apple (Aug 14, 2026)(新しいタブで開きます)en.edaily.co.kr
- 3The Korea Herald: LG Innotek ramps up iPhone 18 Pro camera, AI substrate output (Aug 10, 2026)(新しいタブで開きます)www.koreaherald.com
- 4Hankyung: LG Innotek falls 16% on earnings shock concerns (Oct 13, 2026, Korean)(新しいタブで開きます)www.hankyung.com
関連記事
 株式
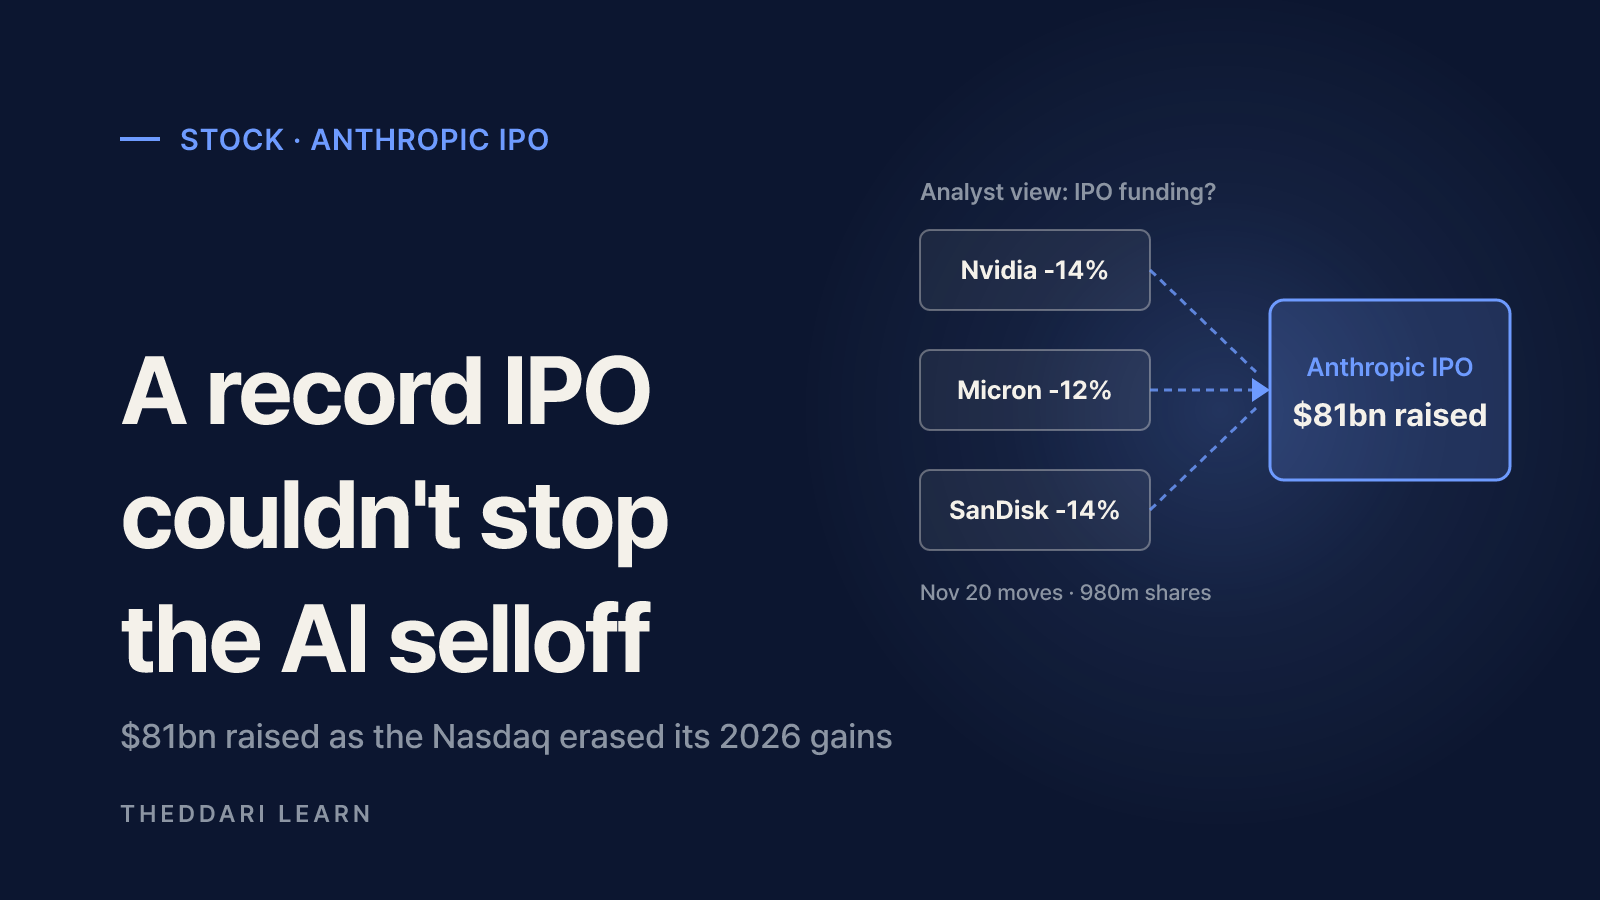
Why the Anthropic IPO Didn't Stop the AI Stock Selloff
Anthropic raised $81bn in the largest IPO on record, yet the Nasdaq wiped out its 2026 gains the next day. Here is how a blockbuster listing and an AI selloff can happen at once.
 株式
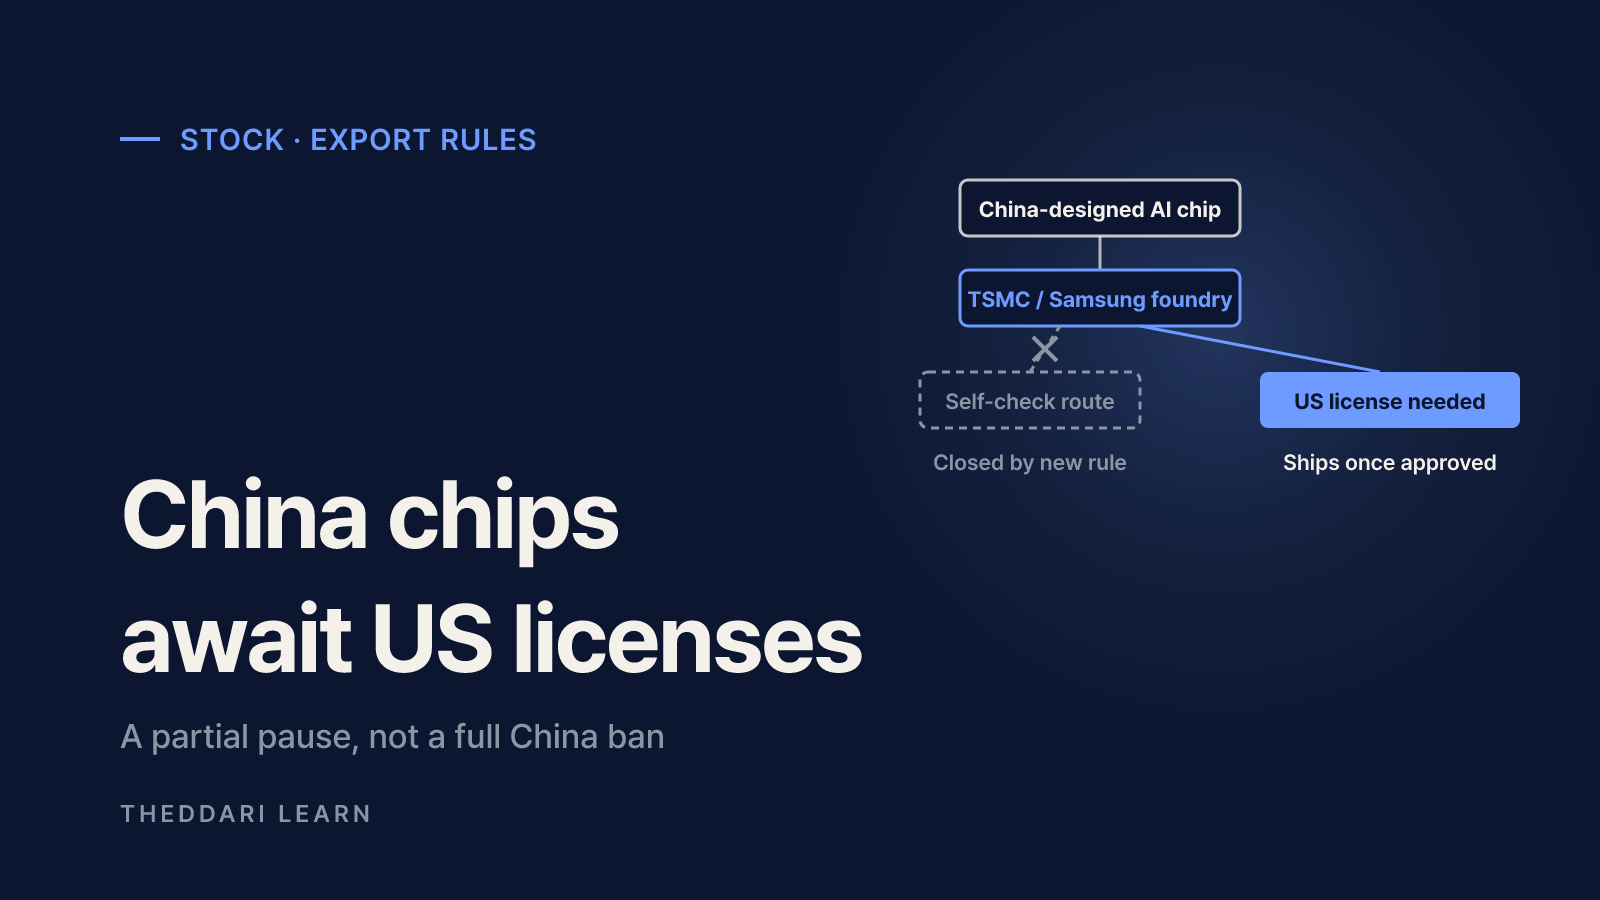
Chip Export Controls: Why TSMC, Samsung Paused China Chips
After the US Commerce Department's new chip export rule took effect on November 19, 2026, TSMC and Samsung reportedly paused some deliveries to Chinese customers. Here is what the rule actually changes, which parts are confirmed, and the numbers that matter for TSM and Samsung shareholders.
 株式
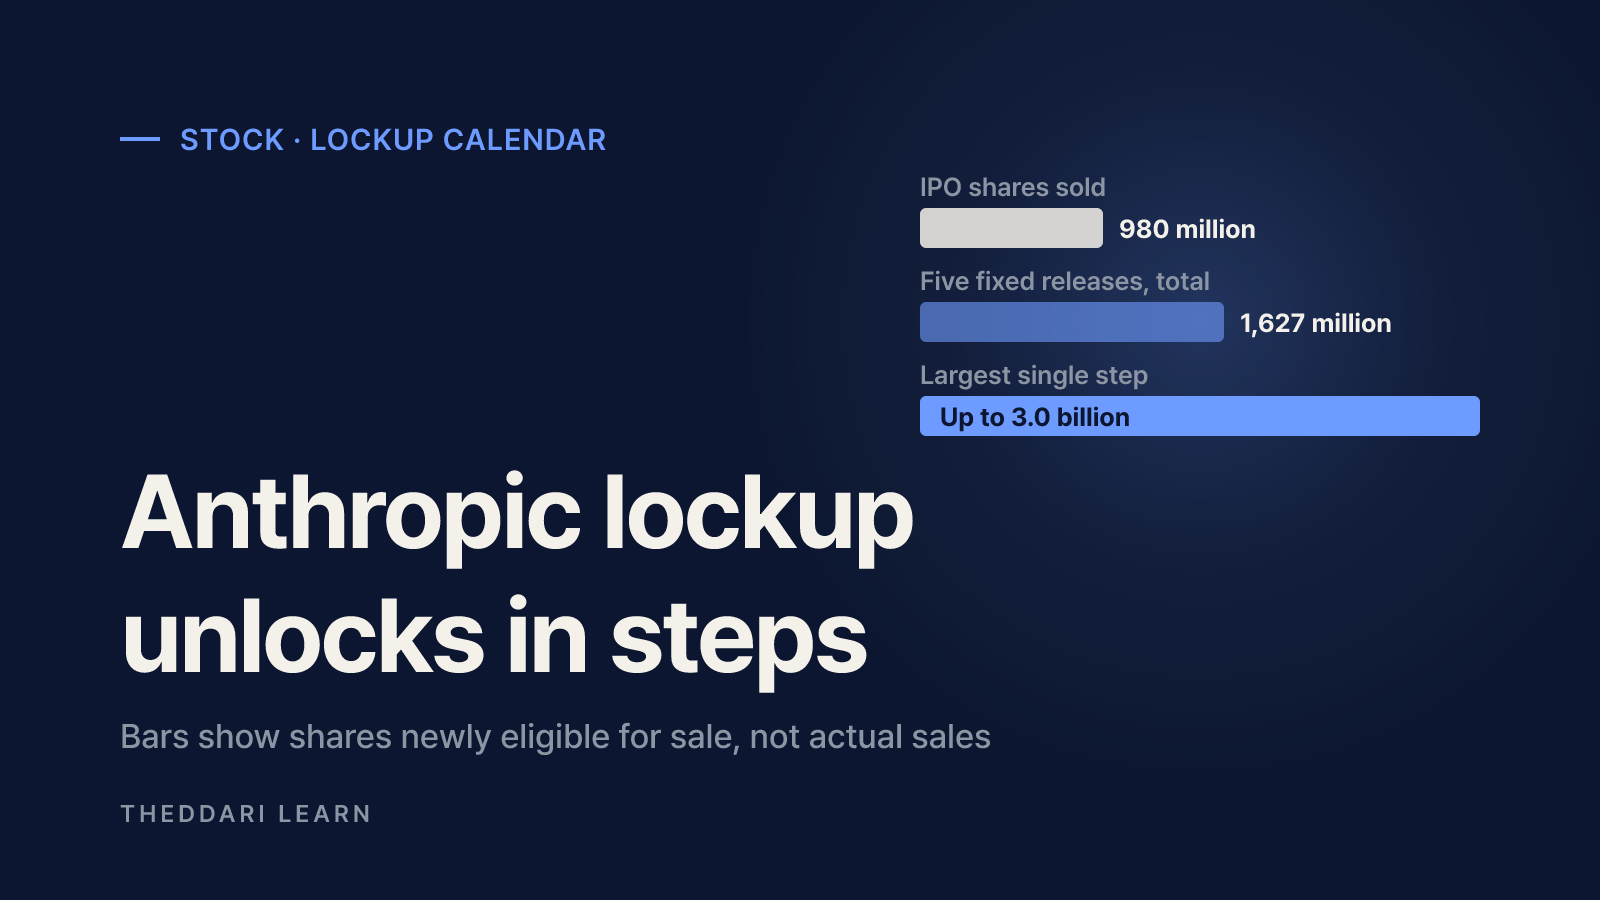
Anthropic IPO Lockup Expiration Dates and ANT Price Impact
There is no single Anthropic lockup expiration date. Insider shares unlock in 23 steps, some on fixed dates and the largest ones tied to earnings. Here is the calendar, where to verify it, and how to think about price impact.