What Is a Pension Savings Trust in Korea? What Existing Holders Should Know and How to Transfer
Korea stopped new pension savings trust sales in 2018. Learn what existing holders keep, how returns compare, and how to transfer to a pension fund account.
目次8セクション
要点
- A Korean pension savings trust is the bank-managed version of Korea's tax-advantaged Pension Savings Account; new sales stopped in January 2018.
- Trusts opened by the end of 2017 carry principal preservation, and since September 1, 2025 they are deposit-insured up to KRW 100 million separately from ordinary deposits at the same bank.
- Korea's Financial Services Commission reported a 2025 annual return of 4.0% for trusts versus 29.3% for funds and ETFs, but funds can lose money and longer-run fund averages were much lower.
- Moving money out should be done through the official account transfer system, not by cancelling, to avoid a 16.5% other-income tax and keep the account's start date.
- Transfers must move the whole balance and cannot be reversed once the old provider confirms your intent by phone.
A Korean pension savings trust (yeongeum jeochuk sintak) is the bank-managed version of Korea's tax-advantaged Pension Savings Account, and it has been closed to new buyers since January 2018. If you still hold one, the short answer is that the account remains valid: trusts opened by the end of 2017 preserve principal and are deposit-insured, but their returns have been modest. If you decide to move the money, use Korea's official pension account transfer system rather than cancelling the account. This guide covers Korean residents and former residents holding these accounts as of October 2026, based on Financial Services Commission (FSC) releases and the government's Easy Law legal information service. It does not cover tax treatment in other countries.
What a Korean pension savings trust is
Korea's Pension Savings Account, often abbreviated PSA, is a private retirement account. Contributions can earn an income tax credit, investment growth is tax-deferred, and money taken as a pension is taxed at lower pension income rates. According to Easy Law, the account comes in three legal forms depending on who you contract with: a trust contract with a licensed trust company (in practice, a bank), a brokerage contract for collective investment securities (the pension savings fund), or an insurance contract (pension savings insurance).
Main providers
- Pension savings trust
- Banks
- Pension savings fund
- Brokerages, banks
- Pension savings insurance
- Insurers
Contributions
- Pension savings trust
- Flexible
- Pension savings fund
- Flexible
- Pension savings insurance
- Regular premiums
Return basis
- Pension savings trust
- Performance-based
- Pension savings fund
- Performance-based
- Pension savings insurance
- Insurer's posted rate
Principal
- Pension savings trust
- Preserved for accounts opened through 2017
- Pension savings fund
- Can fall below contributions
- Pension savings insurance
- Protected by contract, though early balances can sit below premiums paid
Deposit insurance
- Pension savings trust
- Covered
- Pension savings fund
- Not covered
- Pension savings insurance
- Covered
Payout options
- Pension savings trust
- Fixed period
- Pension savings fund
- Fixed period
- Pension savings insurance
- Fixed period; life annuity at life insurers
Open to new buyers
- Pension savings trust
- No, since 2018
- Pension savings fund
- Yes
- Pension savings insurance
- Yes
The trust was unusual: it was performance-based, yet legacy accounts preserve principal. Regulators ended new sales from 2018, and the FSC's 2025 white paper notes that trust balances have been shrinking ever since because no new money can enter. At the end of 2025 trusts held KRW 13.8 trillion, or 6.9% of the KRW 198.2 trillion in all pension savings accounts, down from KRW 15.4 trillion in 2023. Fund balances, by contrast, rose 50.7% in 2025 to KRW 61.3 trillion as many holders moved toward market-linked investments.
What you keep by staying in the trust
Principal preservation and separate deposit insurance
Easy Law states that pension savings trusts opened through 2017 preserve principal. On top of that, the FSC announced that Korea's deposit insurance limit rose from KRW 50 million to KRW 100 million on September 1, 2025, and that pension savings coverage applies separately from ordinary deposits at the same institution. In other words, a trust and a regular savings account at one bank each have their own KRW 100 million limit. Deposit insurance protects you if the institution fails; it says nothing about returns. A fund account does not carry this protection for its market-linked holdings.
How the returns compare
The FSC's white paper reported 2025 annual returns of 4.0% for trusts, 29.3% for funds and ETFs, and 0.8% for insurance (measured on a cumulative basis). Cumulative returns were 3.3% for trusts and 14.3% for funds and ETFs. Read those numbers carefully. The fund figure reflects a strong stock market year; the same report shows five-year and ten-year annualized fund returns of 10.3% and 8.8%. The FSC also changed its calculation method in the fourth quarter of 2025, using the dividend rate for trusts and adjusted net asset value for funds, so it cautions against direct year-over-year comparisons. A fund account can fall below the amount you put in.
Questions to answer before deciding
- How many years remain until you plan to start payouts? Pension withdrawals require age 55 or older and at least five years since the account opened, which most pre-2018 trusts already meet.
- How would you feel about a temporary loss? Leaving the trust means giving up both principal preservation and deposit insurance.
- Will you actively choose and review ETFs or funds? In a fund account the investment selection is your responsibility, and service levels and fees can vary between online and branch channels.
- Is the account a pre-2001 personal pension savings product? Those older accounts follow different tax rules and can only move to a provider that still runs the same legacy product.
- Is the account subject to seizure, provisional seizure or a pledge? Such accounts may not be transferable.
The FSC's own guidance avoids naming a better product. It says each type has different features and that penalties or losses can arise depending on circumstances, so holders should weigh their finances and risk tolerance. If you are considering insurance instead of a fund, check the minimum rate floor, whether the rate floats, and the expense ratio, and remember that cancelling within roughly seven years can trigger a surrender deduction. Lower-risk assets tend to track the interest rate environment, so knowing when central bank rate decisions are scheduled can give context when you compare a trust's dividend rate with alternatives. A calendar explains timing; it does not forecast returns.

How to transfer a Korean pension savings trust to a fund account
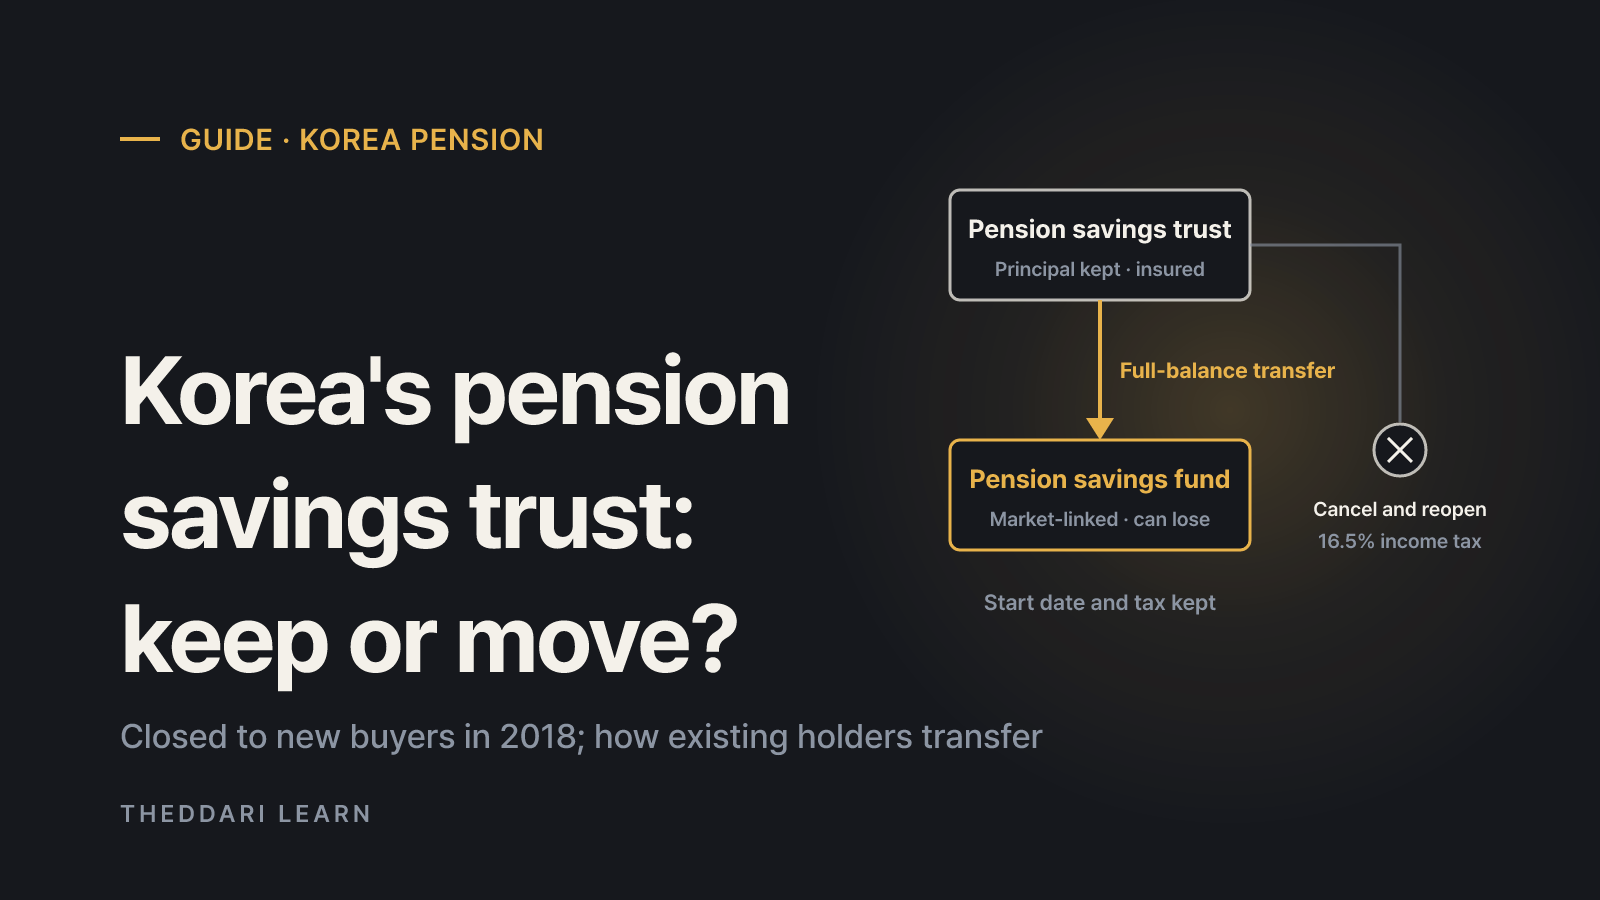
Korea's pension account transfer system lets you move money between pension accounts before payouts start without the move being treated as a withdrawal, so no tax is triggered and the account history continues. Cancelling the trust and opening a new account instead counts as early termination and can trigger the 16.5% other-income tax. Since April 27, 2015, the FSC's simplified procedure means you only need to apply at the receiving provider; many brokerages now also accept applications through their apps, so check the receiving firm's process.
- 1
Compare before you apply
Use the comparison disclosures on Korea's integrated pension portal to check returns and fees. Write down the trust's recent dividend rate and the costs of the products you would buy, using the same basis. Once completed, a transfer cannot be undone.
- 2
Open the receiving account and request the transfer
Open a pension savings fund account and give the receiving provider your bank's name and trust account number. The receiving firm must explain risks such as possible loss of principal and obtain your signed confirmation.
- 3
Choose the account start date
If the receiving account is newly opened with no balance and receives the full balance, you can choose either the old or the new account's start date. Keeping the trust's earlier date preserves the five-year payout condition you have already met.
- 4
Take the confirmation call from your bank
The existing bank confirms your intent in a recorded call and must explain the expected transfer date, estimated amount, transfer fee and the possibility that the final amount differs. If no call arrives by the day after you applied, contact either provider. After you confirm, the transfer cannot be cancelled.
- 5
Invest the transferred balance
Money arriving in a fund account often sits uninvested until you choose products. Check how your provider handles incoming transfers and set a mix of equity, bond and deposit-type products that fits the losses you can tolerate.
When transfers are restricted (FSC guidance): you cannot transfer into an account that is already paying a pension; only full-balance transfers are allowed; accounts opened on or after March 1, 2013 cannot move into accounts opened before that date; and accounts under seizure, provisional seizure or a pledge may be blocked.
Tax rules that carry over after a transfer
Because a transfer keeps the account within the pension system, the same Korean tax structure applies afterward. Per Easy Law, contributions of up to KRW 6 million a year qualify for a tax credit of 16.5% if total salary is KRW 55 million or less (or comprehensive income KRW 45 million or less), and 13.2% above that, including local income tax. The annual contribution cap is KRW 18 million. Payouts within the annual pension limit are taxed at 5.5% before age 70, 4.4% from 70 to under 80 and 3.3% from 80, with 3.3% possible for life annuities. Withdrawals above the limit, or early withdrawals of tax-credited money, face the 16.5% other-income tax. Non-residents and people taxed in another country should check how their home jurisdiction views the account.
Discussion about pension accounts and ETFs spreads quickly through Korean blogs and investor communities, and following those trends can show what other holders are weighing. Your own payout date, tax position and risk tolerance remain the basis for the decision, and official disclosures are the reference for numbers.
Bottom line for existing holders
A legacy pension savings trust is not a problem account simply because it can no longer be sold. It offers principal preservation and separate deposit insurance at the cost of modest returns. If you move, do it through the official transfer system, transfer the full balance, decide whether to keep the original start date, and finish your comparison before your bank's confirmation call, because that call is the point of no return.
よくある質問
Can I still open a pension savings trust in Korea?
Will I pay tax if I move a pension savings trust into a fund account?
Is a Korean pension savings trust protected if the bank fails?
Can I transfer only part of my trust balance?
出典・参考資料
- 1Financial Services Commission (Korea): 2025 Pension Savings Account Investment White Paper, June 18, 2026(新しいタブで開きます)www.fsc.go.kr
- 2Financial Services Commission (Korea): Simplified pension savings account transfers, April 21, 2015(新しいタブで開きます)www.fsc.go.kr
- 3Ministry of Government Legislation, Easy Law: Pension savings(新しいタブで開きます)www.easylaw.go.kr
- 4Financial Services Commission (Korea): Deposits protected up to KRW 100 million from September 1, 2025(新しいタブで開きます)www.fsc.go.kr
関連記事
 投資ガイド
Stock Market Circuit Breakers and Sidecars: US vs Korea
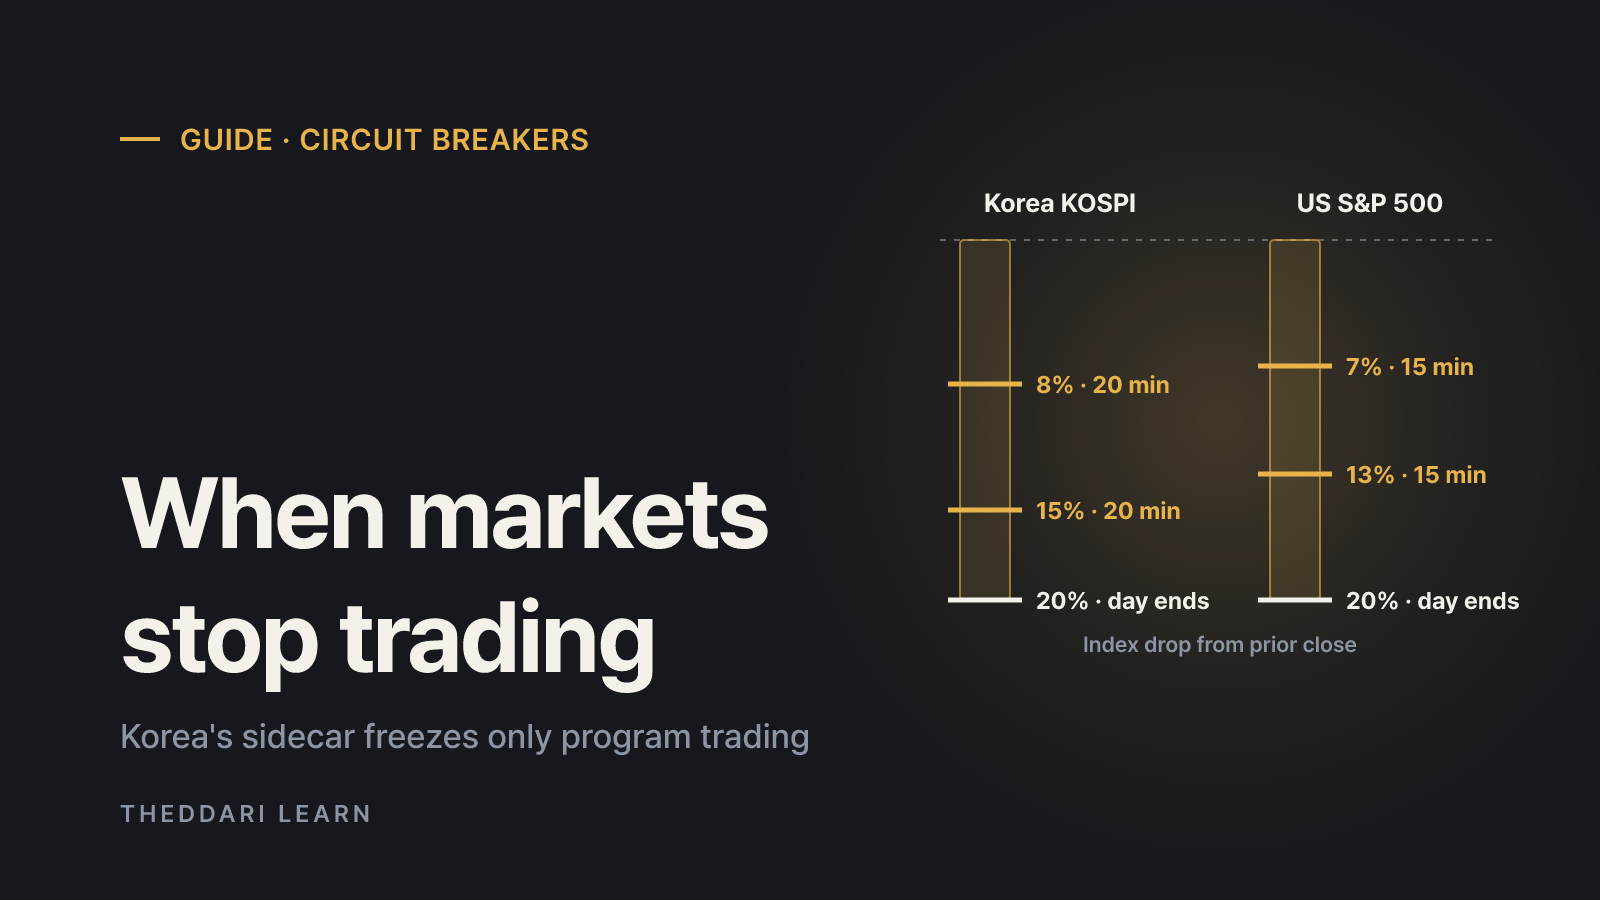
US market-wide circuit breakers halt all trading when the S&P 500 drops 7%, 13% or 20%. Korea uses 8%, 15% and 20% thresholds plus a sidecar that freezes only program trading. Here is how each rule works and what happens to your orders.
 投資ガイド
Pension Withdrawal Order in Korea: How IRP Money Is Taxed
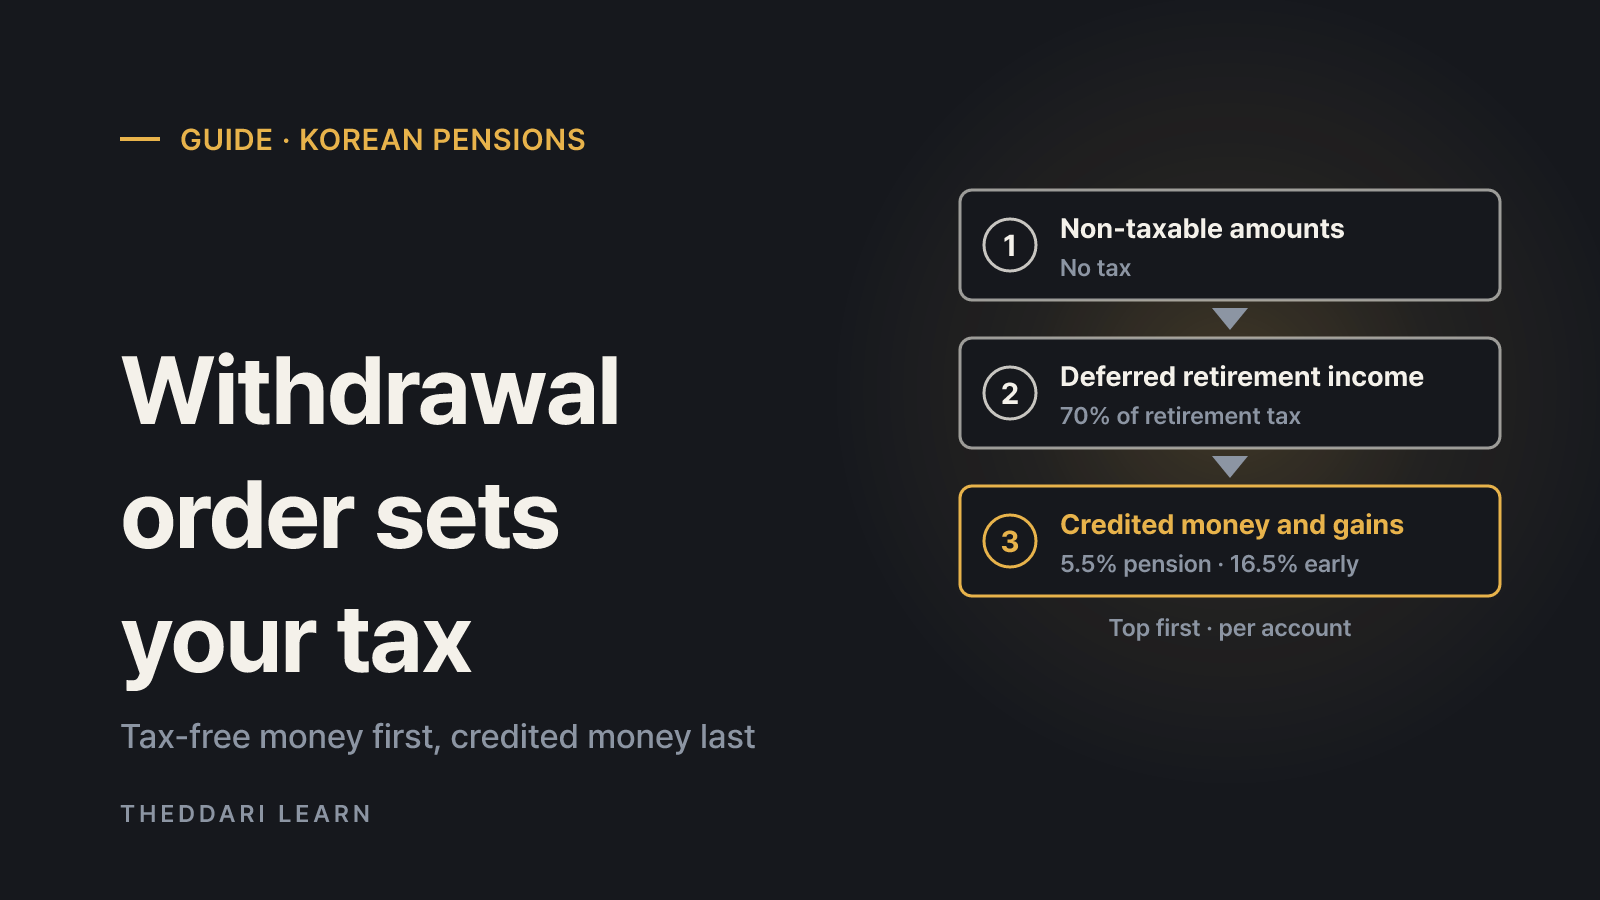
When you take part of the money out of a Korean pension savings account or IRP, the law decides which money left first, and each part is taxed differently. A November 2026 guide to the withdrawal order, rates and exceptions for Korean tax residents.
 投資ガイド
How to Buy ETFs in Singapore: CDP vs Custodian and Fees
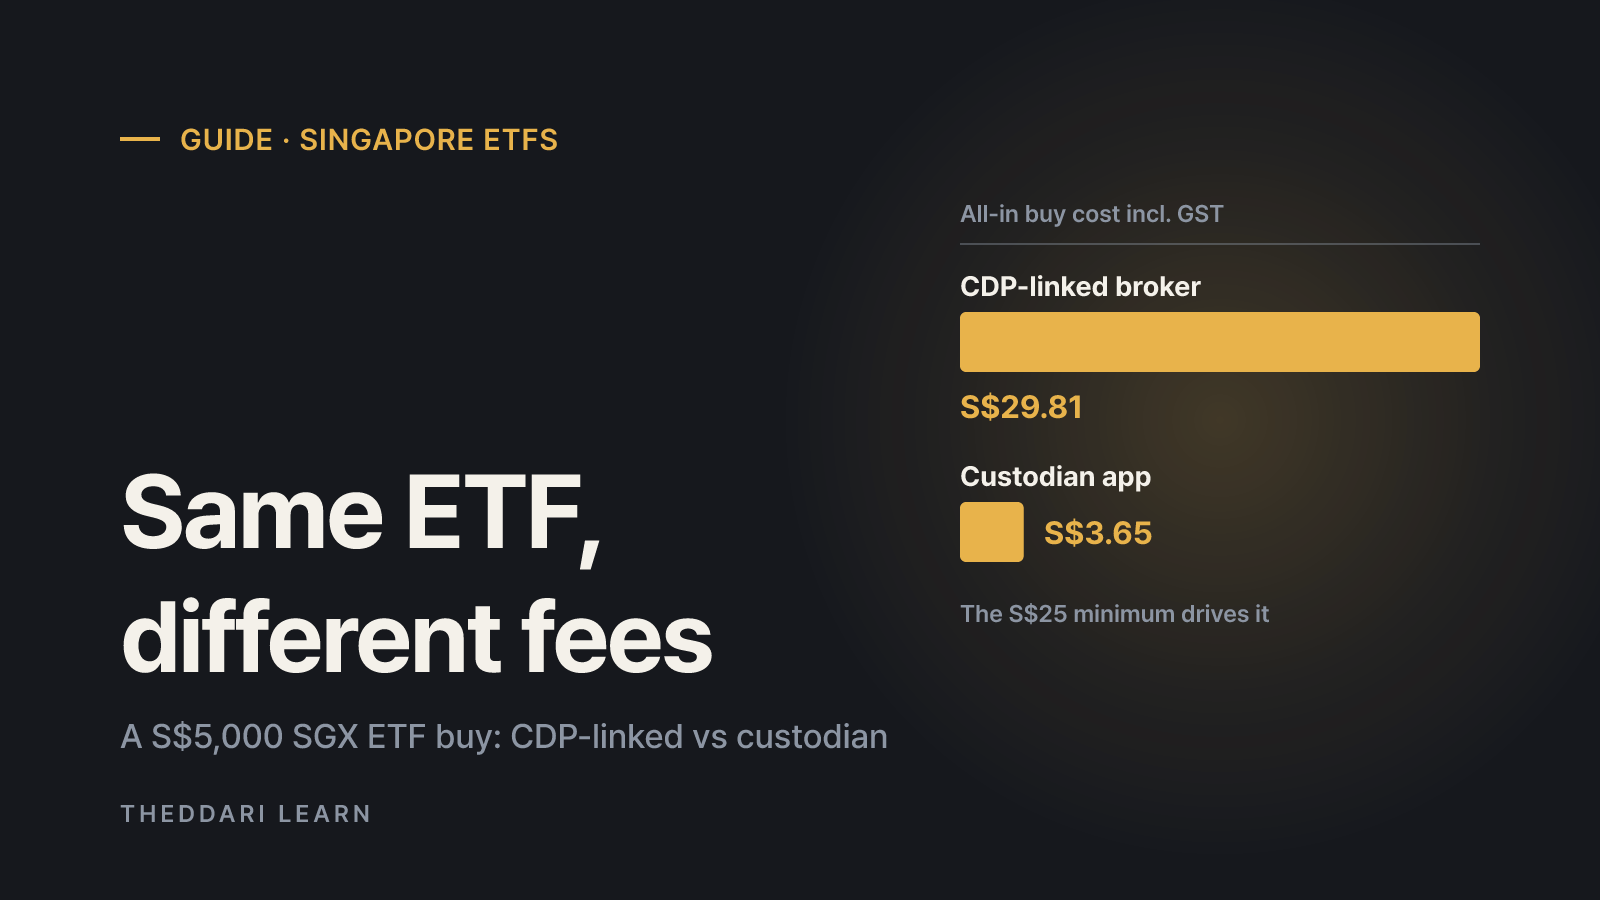
A practical guide for Singapore residents: how SGX-listed and US-listed ETFs are held, what the CDP rule changes of July 2026 mean for custodian accounts, and what a trade really costs at different order sizes.